For most of the last century, giving money away was a physical act. You wrote a check, put notes in a tin, or filled out a form and posted it. The friction was enormous and mostly invisible, because there was no alternative to compare it against.
What changed is not that people became more generous. It is that the payment layer underneath them was rebuilt for something else entirely, and inherited the result. Understanding how technology is changing fundraising means looking at the rails first and the causes second.
This piece covers what the payments shift actually did to the sector, what the published data says about how people now pay, and which problems the technology has conspicuously failed to solve.
The rails came first
Fundraising did not drive any of the infrastructure it now depends on. It arrived late to each of them.
Card-not-present became the default transaction
Every component a donation page needs was built for commerce. Hosted checkout, tokenized card storage, mobile wallets, and the fraud tooling that made card-not-present volume acceptable to issuers in the first place.
By the time a small organization could accept a card online without an acquiring relationship of its own, the hard problems had been solved and paid for by retail. Giving became a checkout flow, and that is essentially all the first generation of online fundraising was.
Once payments were commodity, the platforms specialized
When the plumbing stops being a differentiator, competition moves up the stack. That is the phase the sector is in now, and it explains a shift that looks strange from outside: platforms getting narrower rather than broader.
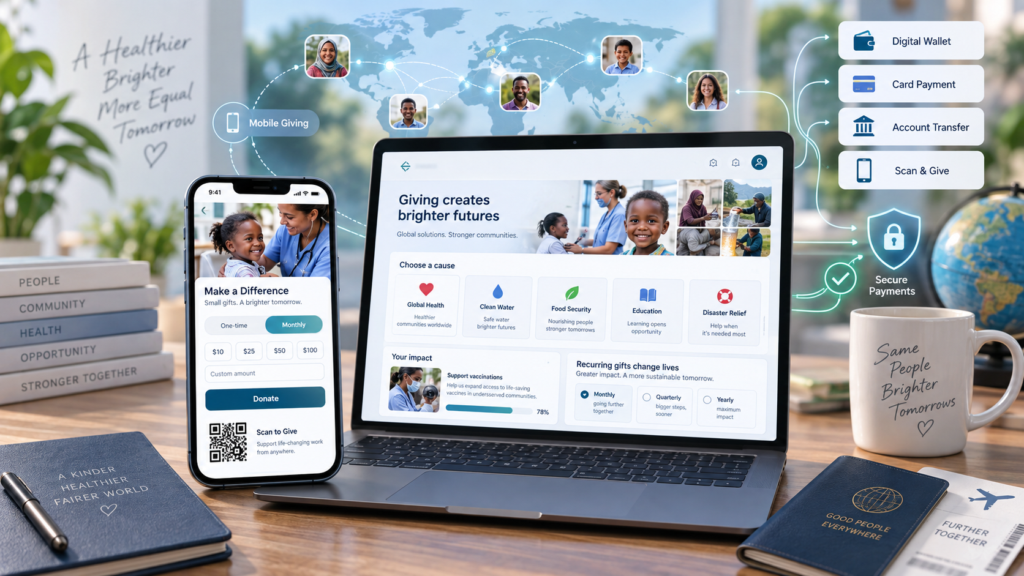
A general giving site optimizes for the widest possible range of campaigns. A sector-specific one surrenders that range to buy context. HealthCommons is an instance of the narrow strategy, confining itself to public health and indexing campaigns by cause, which shifts the discovery burden off the donor and onto the platform.
Recurring billing changed the unit economics
The single most consequential feature was not the one-off donation. It was the subscription, borrowed wholesale from software.
A recurring gift converts an unpredictable annual appeal into something closer to contracted revenue, which changes what an organization can plan and hire against. Retention economics from SaaS transferred almost intact, including the uncomfortable part: acquisition is expensive, and the whole model rests on how long a supporter stays.
What the payment data actually shows
The behavioural shift underneath all of this is measurable, and it is larger than most people in the sector assume.
Cash is no longer most people’s default
In a survey conducted in mid-2026, 42% of US adults said they make no purchases with cash in a typical week, up from 24% in 2015, while the share using cash for all or almost all purchases halved over the same period, from 24% to 12%, according to the Pew Research Center.
That is a payment statistic with an obvious second meaning. A method of asking for money that requires physical currency now excludes a plurality of the people it is put in front of.
Why the collection tin now needs a digital fallback
The consequence is structural rather than sentimental. Cash-based fundraising has not become unfashionable; it has become mechanically unavailable to a large share of potential givers, who are not carrying the instrument it requires.
Every physical ask now needs a digital fallback attached to it, which is why the QR code became ubiquitous in a category that had ignored it for a decade.
What the technology has not solved
Payments were the easy part. Three problems survived the migration intact.
Discovery is still the bottleneck
Accepting money has been a solved problem for years. Being found has not. Most campaigns fail from obscurity rather than from friction at checkout, and no improvement to the payment flow addresses that.
This is the real reason the sector is verticalizing. Categorization is a discovery mechanism, and it is one of the few levers a platform still controls.
Trust does not come from the payment layer
A card form processed by a major gateway tells a donor nothing about whether the money will be used as described. Payment security and campaign legitimacy are unrelated properties, and consumers routinely conflate them.
Nothing in the fintech stack resolves that, which is why platforms in this space compete on vetting and reporting rather than on transaction quality.
It is an unusual market in that respect. In most payment-adjacent categories, reducing friction is the whole product strategy. Here, some of the friction is the product, because a listing process anyone can complete in ninety seconds is precisely the signal a cautious donor reads as risk.
Verification remains a human process
The checks that matter are still done by staff reading applications and confirming that an organization exists and does what it claims. It is slow, it does not scale cleanly, and platforms handling sensitive categories accept the cost because the alternative is worse.
Anyone marketing automated trust in this category is describing an ambition rather than a capability.
Where the next shift is likely
Two developments look reasonably predictable from where the sector sits now.
Category specialists take the high-scrutiny segments first
Vertical competitors are picking off the segments a general marketplace serves worst, and they are not competing on transaction quality, which is now effectively identical everywhere. They compete on things a broad listing cannot offer: an intake standard written for one type of applicant, and a taxonomy a donor can navigate without resorting to search.
Anyone who watched horizontal SaaS lose regulated industries to vertical entrants will find the sequence familiar.
The next cost reduction sits on the bank side, not the card side
Card economics in this category are close to their floor. The remaining headroom is in account-to-account transfer, where a payment initiated directly from a bank account skips the interchange structure entirely.
Adoption has been slow because the consumer experience was worse, which is changing. For recurring gifts in particular, where the same donor authorises the same amount repeatedly, bank-initiated payment is the obvious destination and the sector has barely begun moving there.
The infrastructure story, told accurately
It is tempting to read the last two decades as technology democratising generosity. The more defensible reading is narrower and more interesting: consumer payments were rebuilt at enormous expense for retail, and fundraising picked up the surplus capability nearly free.
That is why the sector’s remaining problems all sit above the payment layer. Discovery, trust, and accountability were never things a gateway could deliver, and they are what the next decade of product work in this category will actually be about.