A schoolteacher in Phoenix opened her brokerage app one Tuesday morning in March 2026 and bought one hundred dollars of the BlackRock iShares Bitcoin Trust through the same screen she uses for her index funds. The trade settled like any other equity, the cost basis went into her brokerage tax report automatically, and she never touched a wallet, a seed phrase, or a crypto exchange. That transaction, repeated millions of times across the United States, is the clearest sign of how cryptocurrencies and digital assets have moved from a niche internet experiment into a normal part of US consumer and business finance.
What a cryptocurrency actually is
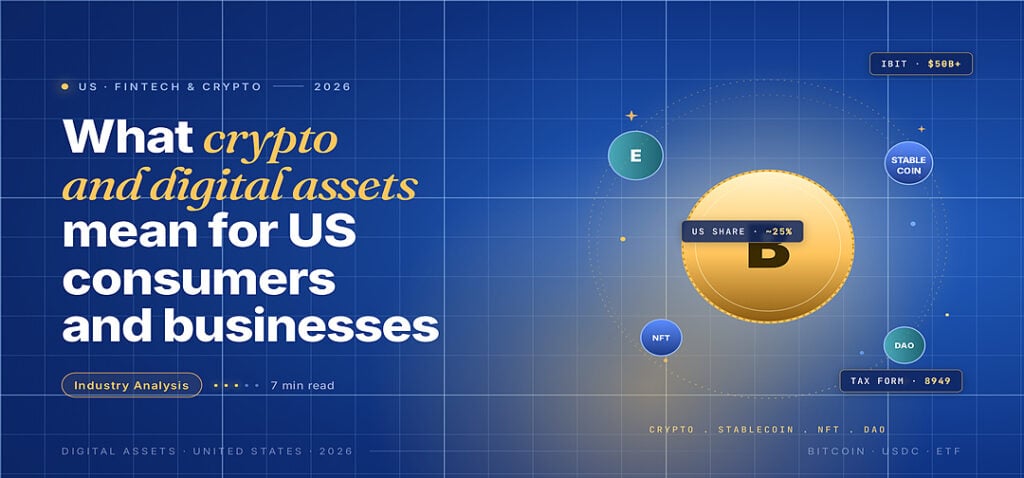
A cryptocurrency is a digital token recorded on a public ledger called a blockchain, which a global network of computers maintains together without a central operator. Bitcoin, launched in 2009, is the original and largest. Ether, the native token of the Ethereum network, is the second largest. A digital asset is the broader category, and it includes cryptocurrencies, stablecoins that track the US dollar, tokenized money market funds, and non-fungible tokens that represent a unique item rather than a divisible currency.
The total market value of all cryptocurrencies sits in the low trillions of dollars by mid 2026, with Bitcoin alone accounting for roughly half that figure. The US share of trading volume runs near a quarter of the global total on any given day, which makes the country the single most important market for the asset class. The TechBullion blockchain coverage tracks the weekly flows and the new product launches that drive the category.
The key feature for a US consumer is that ownership of a cryptocurrency does not depend on a single company. The token sits on the blockchain and the holder controls it through a cryptographic key. That property is what made the asset class interesting to its early users, and it is also what creates the operational complexity that has kept many ordinary Americans on the sidelines until the recent wave of regulated products gave them a simpler entry point.
Spot Bitcoin ETFs and the BlackRock effect
The Securities and Exchange Commission approved the first US spot Bitcoin exchange traded funds in January 2024, after a decade of denials. The approval let a US investor buy Bitcoin exposure inside a standard brokerage account, with no separate exchange, no wallet, and no private key to manage. Eleven ETFs launched on the first trading day, and the category has since pulled in tens of billions of dollars of net inflows from US retail and institutional buyers.
BlackRock’s iShares Bitcoin Trust, ticker IBIT, has become the largest of the group, with assets that crossed fifty billion dollars within eighteen months of launch. Fidelity’s Wise Origin Bitcoin Fund, ticker FBTC, is the second largest US issuer, followed by ARK 21Shares and Bitwise. The SEC approved spot Ether ETFs in July 2024, with a similar group of issuers including BlackRock and Fidelity, although the Ether category has drawn smaller inflows so far. The federal Securities and Exchange Commission posts its research and approvals at the Federal Reserve payments portal, which covers the broader US payment and asset rails the ETFs interact with.
The arrival of the spot ETF has changed how Americans access the asset. A financial advisor at a US wealth manager can now place a Bitcoin allocation alongside the rest of a client portfolio, with no separate custody account and no separate compliance review. The TechBullion digital banking trends coverage tracks how the major US wirehouses and registered investment advisors have built the asset into their model portfolios over the past two years.
Stablecoins, NFTs, and the rest of the asset class
A stablecoin is a digital token designed to hold a value of one US dollar at all times, backed by reserves of cash and short term Treasuries. USDC, issued by Circle, and USDT, issued by Tether, are the two largest, with a combined supply that runs into the hundreds of billions of dollars. A US consumer or business uses a stablecoin to move dollars across borders in minutes for cents in fees, which compares to several days and tens of dollars through a traditional bank wire. Coinbase, the largest US exchange listed at Nasdaq under ticker COIN, holds tens of millions of US customer accounts and runs the most common on ramp from a bank account to a stablecoin or a cryptocurrency.
Non-fungible tokens, or NFTs, are digital assets that represent a unique item rather than a divisible currency. The category drew a wave of attention in 2021 and 2022 around digital art, sports collectibles, and game items, and the trading volume has cooled materially since. The application still matters in narrower use cases, including ticketing for live events, in-game items for major US studios, and tokenized real estate documents that a county recorder can verify against a public chain.
A decentralized autonomous organization, or DAO, is a group of token holders that govern a blockchain protocol or a treasury through on chain votes. The structure has been used to run lending protocols, decentralized exchanges, and grant programs that distribute funds to developers. The McKinsey financial services research at McKinsey insights has tracked how a handful of US foundations and registered entities have begun to wrap DAO style governance into a structure that a US lawyer can sign off on.
What it means for US consumers and businesses
For a US consumer, the practical change since 2024 is that buying Bitcoin or Ether no longer requires a separate exchange account, a separate wallet, or a separate tax workflow. The spot ETF puts the exposure inside the brokerage account and the brokerage handles the cost basis. The risk, the price swings of twenty percent or more in a single week, has not changed. The convenience has. A consumer who wants direct ownership on a blockchain still goes through Coinbase or a comparable US exchange, and that path remains the right one for stablecoin payments, NFT purchases, and on chain applications.
For a US business, the most common use case is stablecoin payments. A US software company that bills a client in Brazil can collect payment in USDC in under a minute, convert to a bank balance the same day, and avoid the four day wait and the foreign exchange spread of a traditional wire. Shopify added stablecoin checkout for US merchants in 2025. Stripe, the US payments company, runs stablecoin payouts in more than seventy countries. The TechBullion payments coverage tracks how the merchant side of the US economy has begun to plug stablecoins into the existing accounts receivable process.
The Internal Revenue Service treats cryptocurrencies and digital assets as property for US tax purposes, which means every sale, swap, or spend is a taxable event. A US holder reports gains and losses on Form 8949 and Schedule D, and the spot ETF reports through the same brokerage 1099 process as a stock. A merchant who accepts a stablecoin records the dollar value at the time of receipt as ordinary income. The rules are settled enough that an ordinary US accountant can file the return without specialist help, which was not the case three years ago.
What changes through 2027 and 2028
Three changes will define the next phase of the asset class for US consumers and businesses. The first is the federal stablecoin framework. The GENIUS Act, signed in 2025, and the related FIT21 market structure bill set the federal rules for a US issued stablecoin and divide oversight of digital assets between the SEC and the CFTC. The bills move the federal regulatory question from open to mostly settled, and they cleared the way for the next round of US bank issued stablecoins to enter the market in 2026.
The second is the spread of tokenized money market funds. BlackRock BUIDL, Franklin Templeton FOBXX, and a growing list of US issuers now run dollar denominated money market funds on public blockchains, with assets that have crossed several billion dollars in 2026. The third is the broader integration of digital assets into the daily operations of a US bank, where the Bank for International Settlements at the BIS fintech portal tracks the cross border standards work that will let a US bank settle tokenized assets against a European or Asian counterpart on a common technical rail. The number worth watching is the share of US adults who hold a digital asset position, directly or through an ETF. When that figure passes one in three, the category will have completed its move from a niche product to a standard part of the US household balance sheet.