By Jamie McIntyre
Australian National Review Chief Editor and Self-Made Millionaire
Jeremy Grantham’s warnings about speculative markets deserve attention. An Instagram carousel published by Wealthivora, drawing on his conversation with The Diary of a CEO, presents a blunt message: reconsider expensive housing, U.S. equities and cryptocurrency, while developing the skills to participate in the AI revolution.
I agree with much of that direction. But my conclusions differ on Bitcoin, government bonds and where the next property opportunities will emerge.
The central question is whether the strategies that built wealth over the past generation will work in the next one. My view is that investors who assume nothing fundamental has changed are taking a considerable risk.
Bitcoin: I bought early, then exited
I told people to buy Bitcoin when it was around US$75. I later told people to sell at US$110,000, which is where I exited.
That is my account of my recommendations and trading history. It explains why I do not approach this debate as someone who has always dismissed cryptocurrency.
An asset can provide an extraordinary opportunity at one price and a very different proposition at another. Having benefited from Bitcoin’s rise does not oblige me to remain invested indefinitely.
Today, I would hold cryptocurrency only as a limited hedge, rather than as the foundation of an investment strategy. Even that hedge can fail: crypto remains volatile, and it should not be assumed to protect wealth during every financial crisis.
I do not need to predict that every cryptocurrency will go to zero to conclude that my investment priorities have changed.
My property advice has changed with the markets
For roughly 25 years, I recommended Australian real estate to my followers. Until recently, that remained a central part of my outlook.
Now, I believe buying investment property in many expensive Western markets is probably foolish when the price, debt burden and rental income no longer make commercial sense.
Property still interests me enormously, but geography, entry price and demand matter.
My investment thesis is that more people will seek lives outside the West, and that capital will follow them. Affordability, lifestyle and the ability to operate businesses remotely could help drive that movement.
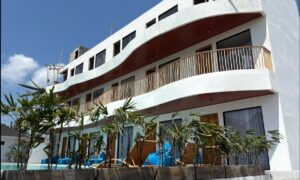
Bali and Lombok are among the places I would examine. Georgia is another possible destination. I see potential in locations that could attract expatriates, entrepreneurs and internationally mobile families.
This is a forecast, rather than a guarantee of migration or capital growth. Emerging markets require careful scrutiny of ownership structures, permits, infrastructure, taxation and the ability to resell. A low purchase price alone does not make a sound investment.
The opportunity I am looking for is property serving real demand in places where people increasingly want to live.
I would not buy U.S. equities—or assume Treasuries solve the problem
I share the concern about committing fresh capital to expensive U.S. equities. A successful company can still be a poor investment if its price assumes too much future success.
But I also disagree with treating U.S. government bonds as an automatic refuge.
An attractive yield does not settle the question of risk. Investors must consider inflation, currency exposure and, for longer-duration bonds, the possibility of substantial price losses if interest rates rise.
My assessment of America’s fiscal position is severe: I regard its debt trajectory as unsustainable—what I describe politically as a government that is “broke and bankrupt.”
That is my judgement about fiscal sustainability, not a claim that the United States has formally entered bankruptcy or stopped meeting its obligations. A government borrowing in its own currency operates differently from a household or company. Nevertheless, repayment in dollars does not guarantee preservation of purchasing power.
I would not lend more money to the U.S. government simply because the headline yield looks appealing.
Prepare for a shift in global power
I believe U.S. military hegemony has already eroded decisively and that its economic dominance is following the same direction.
In my assessment, China’s rise, Russia’s military capabilities, Iran’s regional influence and efforts by BRICS countries to reduce dependence on Western financial systems will intensify that pressure.
These are my geopolitical conclusions. They do not establish that a dollar collapse is inevitable or tell us when one would occur. Military power, economic influence and reserve-currency status are related, but they do not change at identical speeds.
Still, my concern is that the period available to prepare for a major dollar crisis could become shorter as alternatives develop.
I believe people should prepare for a serious financial disruption before they are forced to respond to one.
AI is the opportunity I would learn now
The part of the post I agree with most strongly is its emphasis on learning AI.
My conviction is that AI will change how businesses operate, how services are delivered and how individuals create value. It could help some people become immensely wealthy while leaving others struggling to adapt.
Learning to use AI is different from buying any stock carrying an AI label. A transformative technology can coexist with overpriced investments.
I would focus on practical ability: using AI to improve a business, reduce repetitive work, develop products and solve problems customers will pay to have solved.
My priorities now are to protect purchasing power, examine property opportunities beyond expensive Western markets, and build useful AI skills. That is where I believe preparation and opportunity meet.
This article expresses the author’s opinions and forecasts. It is general commentary, not personal financial advice. Investments can lose value, and readers should obtain independent advice appropriate to their circumstances.
Source: Wealthivora’s Instagram carousel, which credits The Diary of a CEO’s Jeremy Grantham interview. The author’s Bitcoin history, property recommendations and geopolitical assessments are supplied by the author.