When you hand over gold jewellery to a lender, you’re trusting a stranger with something that probably carries both financial and sentimental weight. Most borrowers spend time comparing interest rates and repayment terms but spare little thought for what happens to their ornaments once they disappear behind the counter. That’s a mistake. The storage and safekeeping arrangements matter just as much as the loan terms, because if anything goes wrong with your gold, the interest rate becomes irrelevant. The RBI’s harmonised gold loan framework, which applies across banks, NBFCs and co-operative banks from 1 April 2026, has tightened these protections.
The Vault Behind the Branch
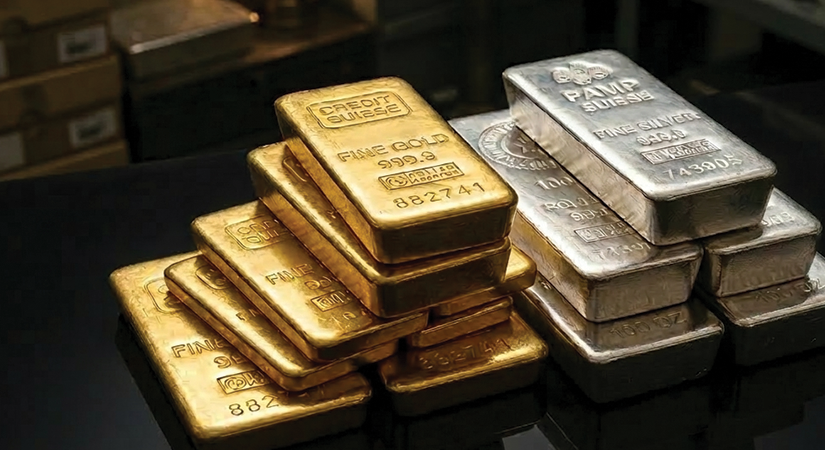
Banks and non-banking financial companies (NBFCs) that offer gold loans must store pledged collateral securely within their own branch premises, handled only by their own employees. In practice, the gold you pledge at a branch usually stays at that branch, locked inside a vault with 24-hour CCTV surveillance, alarm systems, and restricted key access. Larger lenders operate thousands of such branches, each maintaining its own secured storage.
Some lenders, particularly banks, move pledged gold from smaller branches to centralized strong rooms in bigger cities. This is allowed, but transfers across branches must follow strict internal protocols under the RBI rules, so your ornaments don’t simply travel loosely. The receipt and documentation you get at the time of pledging should let you identify where your gold is held, so read it carefully.
If you’ve applied through a gold loan app, the process isn’t fundamentally different. Digital platforms still require you to visit a branch or have an agent visit your home for gold appraisal and physical handover. The app handles documentation, but physical gold still ends up in a physical vault. No amount of digital convenience changes that basic reality.
One protection worth knowing: a lender cannot raise its own borrowing by re-pledging the gold you have pledged to it. Your ornaments are held as security for your loan alone, not reused as collateral elsewhere.
How Gold Is Appraised and Tagged
You are entitled to be present when your gold is tested and assessed at the time of pledging. Lenders weigh and test the gold using XRF (X-ray fluorescence) machines or traditional touchstone methods, and any deductions for stones, fastenings or other non-gold components must be explained to you.
You must then be given a certificate of assaying that records the purity, the gross and net weight, the deductions made, an image of the pledged item, and its assessed value. This is now a requirement, not a courtesy some lenders extend. The packet is sealed and stored, linked to your loan account.
This documentation matters more than people realize. If a dispute arises at the time of return, the certificate, the recorded weight and the image are the objective evidence. Keep your copy safe.
Loss, Damage and Who Pays
Here is where most borrowers have a blind spot, and where the current rules are stronger than many people assume. Your protection does not rest on an insurance policy you can’t see. It rests on the lender’s direct liability.
Under the 2025 Directions, any loss or damage to your collateral must be recorded and promptly communicated to you, and the lender must compensate you, or your legal heirs, for that loss. This obligation sits with the lender directly. You are not a party to the lender’s insurance policy, and your compensation does not depend on the insurer settling a claim first. Lenders typically carry insurance covering theft, burglary, fire and similar risks across their branches, but that is the lender’s own arrangement to cover its liability. Your claim is against the lender.
Two practical points follow. First, the basis on which compensation is calculated is set by the lender’s policy and your loan agreement, so ask at the outset how loss would be valued rather than assuming it tracks the current market price. Second, even with a clear liability, real-world resolution after an event like a branch robbery is rarely instant. Borrowers have had to produce original loan documents, file police complaints, and wait for the process to run. Knowing the lender owes you directly is what keeps that process moving.
Getting Your Gold Back on Time
When you repay or settle the loan in full, the lender must release your gold the same day, or at the latest within seven working days. If the lender delays the return for reasons of its own beyond that window, it must pay you compensation of ₹5,000 per day of delay. This is a specific right, so if a lender stalls after you’ve cleared the loan, cite it.
When you do collect your gold, verify the weight and count of every item against your assaying certificate before signing the release form. Once you sign, disputes become much harder to win.
What Happens When Things Go Wrong
Branch robberies do happen, and there have been reported incidents at gold loan branches across India over the years. In most cases the lender has absorbed the loss and returned equivalent gold or cash value, but the process takes time and documentation.
If you are using an instant loan app that partners with a licensed NBFC for gold loans, the liability for your gold rests with the NBFC, not the app company. Make sure you know which regulated entity actually holds your gold and carries the obligation to compensate you. This is not a trivial detail, and it is the first thing to confirm before you hand anything over.
Protecting Yourself as a Borrower
A few practical steps save you grief. Be present during assaying and get the certificate with the image and weight recorded. Confirm which regulated entity holds your gold and how it would compensate you for loss. Keep your loan receipt, pledge card and assaying certificate together and safe. Note the seven-working-day return rule and the ₹5,000 per day delay compensation, so you know your rights at closure. And when you collect your gold, check every item against the certificate before signing.
The bottom line is straightforward. Your gold is generally safe with regulated lenders who follow RBI norms, and the 2025 framework gives you clearer rights than borrowers had before. But “generally safe” is different from “guaranteed safe.” Know where your gold sits, who is liable if something goes wrong, and what your recourse looks like. That knowledge costs you nothing and could save you a great deal.