Living outside the United States can create a range of tax considerations for American citizens and other U.S. taxpayers abroad. Moving overseas does not automatically end U.S. tax filing responsibilities. Depending on individual circumstances, Americans living abroad may still need to report worldwide income, disclose certain foreign financial accounts and understand how U.S. tax rules interact with the laws of their country of residence.
Mitchell Propster, associated with U.S. expat tax services, provides a professional perspective on the tax considerations that Americans abroad may need to address. His work focuses on the practical complexities that can arise when U.S. taxpayers have financial or residential ties outside the country. His professional background can also be reviewed through his Mitchell Propster LinkedIn profile.
Why U.S. Tax Obligations Can Continue Overseas
One of the most important points for Americans moving abroad is that U.S. citizenship can continue to carry federal income tax responsibilities regardless of where a person lives. The United States generally taxes its citizens and resident aliens on worldwide income. This means income earned from employment, self employment, investments, rental property and other sources may need to be considered when determining U.S. tax obligations.
For an American living in another country, the situation can therefore involve two tax systems. The taxpayer may have obligations in the country where they live while also remaining subject to applicable U.S. filing requirements. Local tax rules vary considerably, making it important to understand the interaction between the two systems rather than assuming that paying tax overseas automatically eliminates U.S. requirements.
Understanding Foreign Income
Foreign earned income is an important consideration for many Americans living overseas. Depending on eligibility and individual circumstances, certain provisions of U.S. tax law may help reduce the impact of double taxation.
For example, the Foreign Earned Income Exclusion can allow qualifying taxpayers to exclude a certain amount of foreign earned income from U.S. federal income tax. Eligibility depends on specific requirements, including applicable residency or physical presence tests. The Foreign Tax Credit is another mechanism that may allow eligible taxpayers to claim a credit for certain foreign income taxes paid or accrued.
These provisions are not interchangeable, and the appropriate treatment depends on the taxpayer’s circumstances. Income type, country of residence, filing status and other factors can affect the analysis.
Foreign Bank Accounts and FBAR Requirements
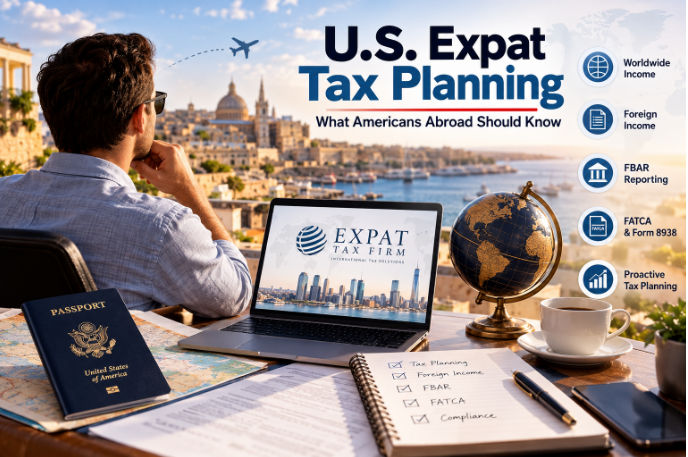
Tax planning for Americans abroad also involves financial account reporting. A U.S. person with qualifying financial accounts outside the United States may have an obligation to file a Report of Foreign Bank and Financial Accounts, commonly known as an FBAR.
The FBAR is generally associated with foreign financial accounts whose aggregate maximum value exceeds the applicable reporting threshold during the calendar year. Importantly, the FBAR is a reporting requirement rather than an additional income tax.
The types of accounts that may be relevant can include foreign bank accounts, brokerage accounts and certain other financial accounts. Because the rules can depend on account ownership and other circumstances, taxpayers should review their situation carefully rather than assuming that an account is either automatically reportable or automatically exempt.
FATCA and Form 8938
The Foreign Account Tax Compliance Act, or FATCA, introduced additional reporting requirements for certain U.S. taxpayers with specified foreign financial assets.
Some taxpayers may need to report specified foreign financial assets on Form 8938 when applicable thresholds are met. The thresholds can vary depending on factors such as filing status and whether the taxpayer lives inside or outside the United States.
FATCA reporting and FBAR reporting are separate requirements. A taxpayer may potentially have to satisfy both, depending on the nature and value of their foreign assets. Understanding the distinction is an important part of managing international tax compliance.
Why Proactive Planning Matters
International tax issues can become more complicated when circumstances change. Moving to another country, starting a foreign business, opening investment accounts, purchasing overseas property, receiving foreign income or changing tax residency can all introduce additional considerations.
For that reason, tax planning is often more useful when it begins before a major financial or residency change rather than after a filing deadline has passed. A review of income sources, financial accounts, residency status and applicable reporting obligations can help identify questions that may need to be addressed during the tax year.
Mitchell Propster’s professional work in the U.S. expat tax space reflects the broader need for taxpayers abroad to understand their responsibilities under U.S. tax rules while also considering the requirements of their country of residence.
Looking at the Complete International Tax Picture
U.S. expat tax planning is not simply about determining whether someone owes federal income tax. It can involve understanding filing requirements, foreign income, tax credits, exclusions, financial account reporting and the interaction between U.S. rules and foreign tax systems.
Americans living overseas should also remember that individual circumstances differ. A U.S. citizen working for a foreign employer may face different considerations from an American who owns a foreign company, maintains significant investment accounts overseas or receives rental income from property abroad.
Professional guidance can therefore be useful when the tax situation involves multiple countries or unfamiliar reporting requirements. The goal is to understand which obligations apply, which tax provisions may be available and what documentation should be maintained.
For Americans living abroad, taking a proactive approach can make international tax compliance easier to understand and manage. Reviewing U.S. filing requirements alongside foreign obligations can help taxpayers make informed decisions throughout the year instead of addressing international tax questions only when a return is due.