Margin Trade’s head of marketing, Margie Feng, on why single stocks jumped the roadmap, who is really trading a Marvell perp at 2am, and what it takes to get a proof-of-work community to place its first short.
Margin Trade went live on Solana in early June with a handful of markets and a straightforward proposition: one cross-margin account covering crypto perpetuals, commodities and equity exposure, settled onchain. Built by contributors to Solayer Labs alongside former Citadel and Kraken traders, it has since grown to around thirty markets and rebuilt much of its public identity around a single token – Pearl (PRL), the proof-of-useful-work network whose miners have become an unexpectedly central constituency.
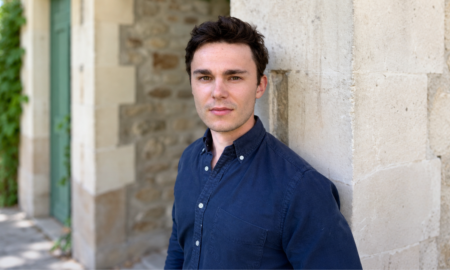
Margie Feng leads marketing for Solayer and Margin Trade. She previously handled public relations at Bitmain, before that worked at Hill+Knowlton Strategies, and holds a master’s in journalism from USC Annenberg. She spoke to us about event-driven attention, the behavioural problem at the heart of cross-margin, and why the hardest thing she has had to sell is not leverage but hedging.
You launched with crypto, commodities and an index, and by late August you were listing single names like $MRVL (Marvell) at 10x. What did you learn in those first weeks that pulled single stocks forward on the roadmap?
Nobody wakes up at 2am with a view on “the index.” They have a view on Nvidia’s earnings or Marvell’s guidance. By early August our thirteen semiconductor markets had done about $52 million, roughly a third of the platform, so the AI trade was clearly the wedge.
What I realized is that stock attention is event-driven. People show up when something happens: an earnings print, Tesla unveiling the Cybercab, an Apple event. So I built our marketing calendar around the events calendar. I track every earnings date for a listed name, produce a live market card the night it prints, and keep the feed moving between events with data content like our “three to thirty markets” and “$10K race” animations.
We went from three markets to thirty in two months and past $190 million in cumulative volume. On the marketing side, X impressions are up 10x and profile visits 3x since launch. Referred users retain at 73% after 30 days versus 38% for organic signups. The listings created the surface. The events calendar is what made people come back to it.
At Rare Evo you said tokenisation without a trading venue is “just a PDF on a blockchain.” So who is actually showing up to trade a 24/7 Marvell perp at 2am — crypto traders reaching into equities, or equities traders reaching into crypto?
Crypto-native capital reaching into equities. Our depositors arrive with USDC from a Solana wallet, not a brokerage transfer.
Our largest real trader rotates his whole book weekly: metals, then crude, then a Korean memory stock, then SOL and BTC. He does not think in asset classes; he thinks in “where is volatility this week,” and he wants it in one collateral account.
The group I did not plan for was miners. The Pearl community came for PRL and a share of them actually stayed for semiconductors, because a miner already has an opinion on Nvidia.
Cross-margin across crypto, metals and equities is the core claim. What has been hardest to make real – the risk engine, the oracles, or convincing traders to put everything in one collateral account?
I’d say the hardest part is behavioral. Most of our users came for one asset, Pearl. A trader who arrives for one asset does not automatically become a multi-asset trader. When I looked at our first cohort of PRL traders, only about one in five had ever touched another market.
The promise of one collateral account is simple. If you make money on PRL, that profit is already sitting in the account as margin. You can trade Nvidia or gold with it without moving funds to another platform. But nobody uses that promise until they trust the account.
So I run it as a sequence. First, be the default venue when a miner thinks “trade or hedge PRL.” Second, earn the right to keep them: smooth onboarding, fast withdrawals, responsive support, and proof that funds are safe. Only then push the second market.
Being the only venue with both PRL spot and perps is a real moat on a small asset. Is owning the long tail properly a repeatable strategy, or was Pearl a one-off?
Yes, but “properly” is a marketing problem before it is a listing problem. Pearl is proof-of-useful-work. Listing spot and a perp together made us the only place to buy, sell, hedge and lever it in one account. But that only matters if miners know you exist and trust you with what they mined.
So I ran PRL as a funnel. Awareness: I built the Chinese-language Pearl community from zero, with a daily hashrate and wallet report, because miners read network stats before price. Trust: community-run positioning, anti-scam filtering, and when another venue ran into trouble in August, our only message was “our deposits and withdrawals work.”
The asset will change. The sequence will not. The next proof-of-work community gets the same playbook, and we already know where to start.
What is the single hardest thing to explain to a normal trader about Margin Trade, and what is the version of that explanation you have landed on?
Explaining hedging to a miner. A miner’s mindset is accumulation: the rig runs, coins arrive, you hold and sell some for electricity. “Short a perp against your output” sounds like betting against the project you spend money securing. Every mechanical explanation failed on that emotional point.
I changed the narrative to: “Your rig makes you long PRL every day. You did not choose that position, the hardware did. We give you the other side, so you decide how long you want to be.”
Then sequencing. I stopped asking for the hedge first. A miner’s first trade on a new venue is a sell, because selling is the trust test: deposit, sell, withdraw, see it work. Awareness, trust, one small trade, then the mindset shift. You cannot skip a step with this audience.
Twelve months out, what would make you say the multi-asset bet worked – a number, a market, or a type of user you don’t have yet?
Three things. A user: the Pearl miner who sells part of production into our spot book, keeps a short against the rest, and treats us as the treasury desk for their mining operation. That user barely exists today.
A market: PRL price discovery happening on our book. In September PRL went from about 26 cents to over 60 in three weeks, and the question I asked was not “how much volume,” it was “was the price set here, on organic flow.”
A method: the awareness-to-trust-to-trial-to-mindset sequence documented well enough to run for the next asset in a fraction of the time.
Multi-asset was never about the number of tickers. It was proving a derivatives venue can be built for a community that did not know it needed one. If the next mining community comes to us before we go to them, it worked. We have already had a few come to us.