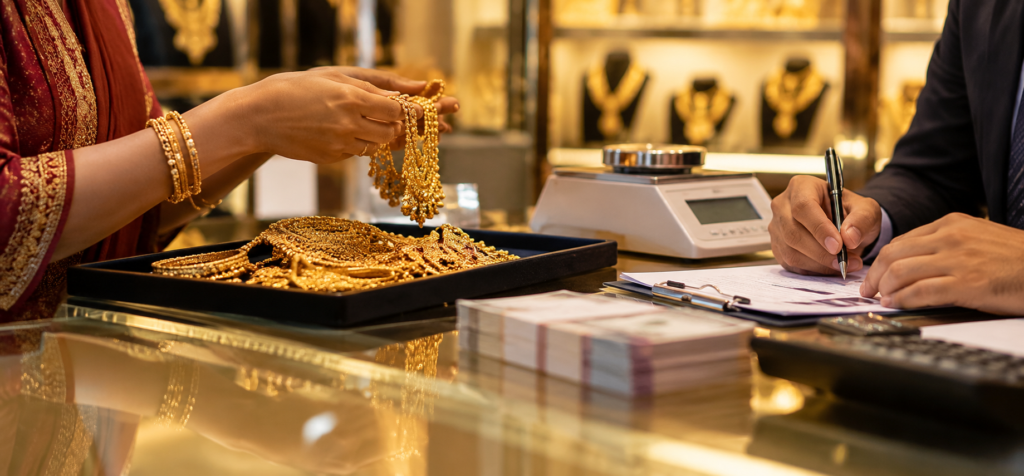
Behind the glittering display cases and polished showrooms that define most people’s experience of jewellery retail lies a considerably less visible financial infrastructure, one built around gold-backed lending, inventory financing, and metal leasing arrangements that most customers browsing engagement rings or wedding sets never think to consider. Understanding this behind-the-scenes financial architecture reveals a great deal about how jewellery businesses actually fund their operations and manage the unique capital demands of dealing in precious materials. The nityas gems and jewellery ipo operates within this specialized financing ecosystem, making it worth exploring how gold and precious metal financing actually shapes jewellery business economics.
Why Precious Metal Financing Works Differently From Conventional Business Loans
Most manufacturing or retail businesses finance their inventory through standard working capital loans, borrowing against generic collateral or simply using company cash reserves. Jewellery businesses, given the extraordinarily high value density of their inventory, often utilize specialized gold metal loan arrangements instead, where banks or bullion suppliers essentially lend actual physical gold to jewellers, who then convert that borrowed metal into finished jewellery, sell the finished pieces, and eventually repay the loan in equivalent gold quantity or cash value rather than simply borrowing cash to purchase raw material outright.
This arrangement offers jewellers meaningful advantages, reducing the need to tie up enormous amounts of cash purchasing gold outright, while also providing some natural hedging against gold price fluctuations, since the loan obligation itself moves in tandem with prevailing metal prices rather than remaining fixed as a cash amount would.
How This Financing Structure Shapes Business Operations
Jewellery businesses utilizing gold metal loan financing typically need to manage several interconnected operational considerations:
- Loan tenure alignment with inventory turnover, ensuring finished jewellery sells through fast enough to service loan repayment obligations comfortably
- Gold price risk management, understanding how metal price movements affect both borrowed material value and finished inventory worth simultaneously
- Relationship management with lending banks and bullion suppliers, since these financing relationships require considerable trust and established track records
- Balancing loan-financed inventory against owned inventory, optimizing the mix based on cost of capital and risk tolerance considerations
Companies that manage this financing structure skillfully typically achieve more efficient capital utilization than those relying purely on conventional cash-based inventory purchasing, freeing up capital for store expansion, design innovation, or other growth investments instead.
The Seasonal Rhythm This Financing Must Accommodate
India’s jewellery demand follows fairly pronounced seasonal patterns, with wedding seasons and major festivals like Akshaya Tritiya or Diwali driving concentrated buying periods throughout the year. Gold loan financing arrangements need to accommodate this seasonality, with jewellers typically drawing down larger loan amounts ahead of anticipated high-demand periods to build sufficient finished inventory, then working to sell through and repay obligations before the next seasonal cycle begins.
Businesses that have developed sophisticated forecasting capabilities around these seasonal demand patterns typically time their financing drawdowns more efficiently than those managing inventory and financing on a more reactive, less predictive basis.
Why This Financing Sophistication Matters For Business Scalability
Jewellery businesses seeking to expand store networks or enter new markets typically need considerably more sophisticated financing arrangements than smaller, single-location operations, since larger inventory requirements across multiple locations demand correspondingly larger and more complex financing structures. Companies that have successfully built these more sophisticated financing relationships and demonstrated reliable repayment track records over time often find it easier to access the kind of scaled capital needed for meaningful business expansion compared to those still operating with simpler, smaller-scale financing arrangements.
Where This Fits Within Broader Public Market Activity
Jewellery and precious metals retail represents one distinctive category among the many types of businesses that periodically approach public markets seeking growth capital. Investors interested in understanding how frequently such specialty retail businesses appear within the broader mix of companies currently preparing for public listings often find it useful to track the upcoming ipo calendar, which provides visibility into market activity across various sectors and helps contextualize sector-specific listings against the broader universe of companies seeking public capital during any given period.
What This Financial Architecture Reveals About Business Quality
When evaluating a jewellery business, understanding its approach to gold and precious metal financing, including loan utilization patterns, repayment track record, and how effectively the company manages the interplay between seasonal demand and financing cycles, often provides considerably more meaningful insight into operational sophistication than simply reviewing headline revenue or store count figures, since this financial architecture fundamentally shapes whether a jewellery business can scale sustainably or remains constrained by inefficient capital deployment within an industry where inventory financing represents such a central operational reality.