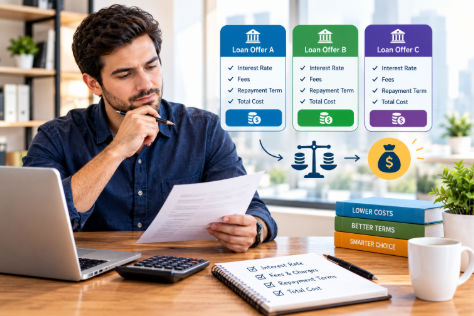
Two business loans for the same amount can have very different effects on cash flow and owner risk. One may disburse less cash after fees. Another may require daily withdrawals. A third may advertise an attractive rate while asking for a broad personal guarantee. Comparing business financing means translating every proposal into the same set of numbers and obligations. This guide gives U.S. small business owners a practical way to do that without assuming any lender or program is best for everyone.
Build one comparison brief for every lender
Write a short financing brief before requesting quotes. Include the amount you need in the bank account, how you will use it, when the money is needed, and how long the financed asset or project will produce value. Add current monthly revenue, the business’s time in operation, existing debt payments, and any important seasonal pattern. Send the same facts to each prospective lender. When an offer differs, you can then identify whether the difference comes from pricing, structure, or a changed assumption.
Ask each lender whether the initial response is a marketing estimate, a conditional offer, or a final approval. Find out what remains to be checked. A quoted rate can change after review of bank statements, credit history, collateral, or ownership details. Keep a record of the version and date of each proposal. Comparing an early estimate with a fully underwritten offer gives a false impression of certainty.
Calculate the cash you will actually receive
The face amount of a loan may not equal the cash available for the project. Origination fees, broker fees, closing costs, or an amount withheld at funding can reduce proceeds. Some costs may be financed into the principal instead. For each offer, record the gross amount, every deduction, and the net amount deposited. If the project needs a specific cash amount, a loan with large deductions may leave a gap that forces the business to borrow again or use reserves.
Ask who receives each fee and whether it is refundable if the financing does not close. If a broker is involved, understand whether the broker is paid by you, the lender, or both. Do not rely on a verbal statement that an offer is “no fee” until the closing documents support it. A simple net-proceeds calculation often exposes the largest difference between two proposals before you even compare interest.
Normalize the repayment schedule
Put every offer into a table showing payment amount, due date, frequency, number of payments, and total repayment. Monthly, weekly, and daily schedules should be converted into a monthly cash-flow forecast, not merely compared by dividing an annual total. A company that collects customers at the end of each month may struggle with daily withdrawals even when annual profit appears sufficient. Ask whether payments are automatically debited and what happens after an insufficient-funds event.
For variable-rate debt, ask what benchmark is used, how often the rate can reset, whether there are caps, and how a higher rate would change payments. For a line of credit, separate the cost of keeping the line open from the cost of drawing on it. Consider unused-line fees, draw fees, annual fees, and renewal requirements. Flexibility is valuable only if the terms let you use it when the business needs it.
Compare the price on a common basis
Request an annualized cost measure when one is available, but also compare total dollars paid. Business financing products are not always presented using the same rate format. A factor rate, simple-interest rate, and annual percentage rate are not interchangeable labels. The timing of repayments matters: repaying a large part of the balance quickly while paying the same total fee can make the effective cost higher than a headline number suggests. Have an accountant or qualified adviser help translate an unfamiliar structure before signing.
Use the same net funding amount and a realistic expected payoff date for each comparison. Ask whether early repayment reduces the remaining financing charge or only ends future scheduled payments. Read the prepayment provision rather than assuming early payoff saves interest. A loan that costs less over its full term might cost more if you expect to refinance or sell the financed asset soon.
Read collateral and guarantee language closely
Price is only one part of the offer. Identify any lien on specific equipment, inventory, receivables, or a broader set of business assets. A personal guarantee can make the owner responsible if the business cannot pay. Ask whether a spouse or co-owner must sign and whether a guarantee is limited or continuing. Find out how an existing lender’s lien could affect the new financing. These provisions may matter much more than a small difference in rate.
Also compare default triggers, cure periods, late charges, and the lender’s ability to accelerate the balance. A covenant may require financial reports, a minimum cash balance, or notice before taking more debt. If the terms are unclear, ask for a written explanation and, where material, legal or accounting review. Do not sign based on a salesperson’s summary when the contract says something different.
Test offers against the business’s weakest months
Build a 12-month cash-flow forecast using expected customer receipts, fixed costs, variable costs, taxes, and existing debt. Add each financing offer separately. Model a downside case in which customers pay later or sales fall below plan. The purpose is to learn how much cushion remains after each payment, not to produce a perfect prediction. Keep enough working capital to operate after funding the project; a loan that uses the entire reserve for closing costs can create the next emergency.
Consider the expense being financed. A long-term equipment purchase may justify a different term from a short inventory cycle. If the project will not create cash until months after funding, a repayment schedule beginning immediately can be a mismatch. Ask whether the lender offers a structure that reflects the project’s timeline, and compare its total cost with the simpler alternative.
Verify the lender and the final documents
Check the lender’s identity, contact details, and state requirements that apply to the product. Ask who will service the loan and where payments go after closing. Review the final documents for the same net proceeds, rate, fees, repayment dates, collateral, and guarantees that appeared in the offer. Never treat a screenshot of a rate or a salesperson’s message as a substitute for the agreement. Keep copies of all signed documents and a calendar of important dates.
Borrower discussions in r/loansforsmallbusiness can suggest questions to add to a comparison sheet. For example, a thread about finding the best small business loan contains experiences with different financing routes. Treat those experiences as individual accounts, not verified terms or eligibility rules. The lender’s written proposal and contract control your decision.
Choose the offer you can explain
The strongest proposal is one you can explain in plain language: how much cash arrives, what the business pays and when, what assets and personal finances are at risk, and why the funded project is expected to earn more than it costs. If you cannot answer those questions from the documents, the comparison is not complete. An approval is useful only when the financing advances a defined business goal without creating a payment burden the company cannot manage in a slow period.