Most online retail strategy still rests on an assumption borrowed from the supermarket: carry more, capture more. A wider catalogue means more entry points, more baskets, more chances that whatever a customer types finds a match on your shelf.
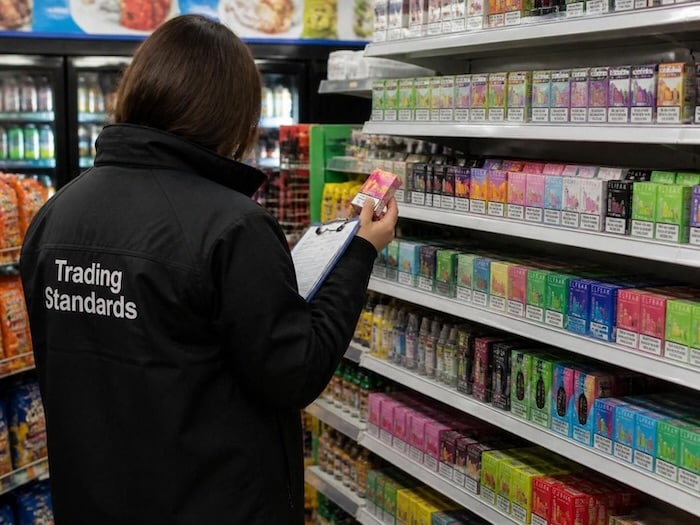
That assumption is under quiet pressure in categories where a regulator has just rearranged the furniture. The UK vape market is the clearest current example, and the data it has produced since the single-use device ban of June 2025 is worth the attention of anyone running a specialist retail operation in any regulated category.
Demand did not fall. It relocated, violently.
The interesting thing about a format ban is that it does not destroy consumer demand, it invalidates the vocabulary that demand was expressed in. Search behaviour makes that visible in a way that till receipts do not.
UK search-volume data (Ahrefs, pulled September 2026) shows what happened to the brand terms that defined the disposable era:
| Search term | Decline from peak monthly volume |
| Elf Bar (brand) | down 88% |
| Elf Bar 600 | down 94% |
| Lost Mary BM6000 | down 77% |
| Crystal Prime 7000 | down 93% |
Those are not softening curves. They are cliffs, and they represent enormous quantities of accumulated brand equity, SEO authority and retail shelf logic becoming worthless inside eighteen months. Any retailer whose category pages were organised around those terms watched a large share of organic acquisition evaporate on a known date.
Against that, one curve did not break. Searches for the Hayati Pro Max line have held above 22,000 a month for three consecutive years and currently sit near 36,000 a month in the UK. The brand transitioned its customers from a banned disposable to a rechargeable pod kit without losing the search term that carried them, largely because the successor product kept the name, the flavour list and the form factor while changing the internals.
One durable demand curve inside a category of collapsing ones is, commercially, a very different proposition from forty brands averaging out.
The concentration argument
Here is the question that follows. If demand in a category has consolidated into a small number of resilient brands, is a generalist catalogue still the right structure to serve it?
The case for specialisation has three legs.
Depth beats breadth on long-tail intent. A brand with several device lines, sixty-odd flavour variants per line and a naming scheme its own customers get wrong generates thousands of distinct queries. A generalist retailer carrying forty brands cannot economically write authoritative content for each variant of each one. A specialist can, because the entire content budget points at a single family. In search terms, that is the difference between a page that mentions a product and a page that answers everything about it.
Inventory risk is legible. Carrying one brand means one distributor relationship, one compliance exposure and one set of stock decisions. That is more concentration risk in the classic sense, and any serious assessment should say so: a single regulatory action against that brand takes the whole business with it. The offsetting benefit is that the risk is visible and priced rather than diffused across forty small unknowns.
Repeat purchase is structural, not earned. This is the part generalists consistently underrate. Post-ban devices are platforms: a customer buys a kit once, then buys refills for it repeatedly, and the refills only fit that manufacturer’s hardware. Demand for Hayati Pro Max plus refill pods runs at roughly ten times the search volume of the device they fit, which is exactly what you would expect from a consumable attached to an installed base. A specialist sells the platform in order to own the consumable. A generalist sells a device and hopes.
The unit economics are unusual
Look at the pricing of these product families and something odd stands out. The device itself is priced barely above the refill that goes in it, often a difference of about three pounds. A Hayati Pro Ultra Plus 25000 kit is a battery, a screen, a charging circuit and a full refill pack, sold for roughly the price of the refill pack alone. In practice the hardware is sold near cost to seed the installed base, and the margin lives in the consumable.
That is the razor-and-blades model, arriving in a category that reached it by accident rather than design. The ban removed the throwaway device, which forced manufacturers to build a durable body, which created an installed base, which created a recurring revenue line where previously there was only replacement purchasing.
For a retailer the consequences are practical. Customer acquisition cost is amortised across a consumable stream rather than recovered on a single transaction, which changes what you can afford to pay for a first order. Catalogue depth on refills matters more than catalogue breadth on devices. And content investment compounds, because a page about a refill that fits a device someone already owns keeps converting long after the page about the device has done its job. Organising a storefront around one manufacturer’s Hayati Pro Max range rather than around categories is a direct expression of that logic.
The next variable is fiscal
From 1 October 2026 the UK applies Vaping Products Duty at a flat £2.20 per 10ml of liquid, irrespective of nicotine content. Because the charge is volumetric rather than proportional, it compresses margins hardest at the cheap end and rewards larger-format products, which will do to the category’s price architecture roughly what the ban did to its product architecture. Retailers who have modelled the vape tax UK impact product by product are going to make better buying decisions this autumn than those waiting to see what competitors print.
It also introduces a forecasting problem nobody in the trade has solved, because pre-duty stock may legally be sold until 31 March 2027. For six months the same product will exist at two lawful price points, which makes competitor price monitoring nearly meaningless as a signal.
What generalises beyond vaping
Strip out the specifics and the pattern applies to any category where regulation periodically invalidates a product format: nicotine, supplements, CBD, certain financial products, parts of consumer electronics.
When a format dies, brand equity transfers only if the successor product keeps the name. Demand that survives a transition concentrates rather than redistributes evenly. Consumables attached to an installed base outperform the hardware that created the base. And the retailer best placed to capture any of that is the one whose content and catalogue are deep enough to answer the specific question a customer is asking, rather than wide enough to have technically stocked the answer.
Breadth was a hedge against not knowing what customers would want. When the data tells you precisely what they want, the hedge starts to look like an expense.
Tushan Das is the director of Hayati Pro Club, an independent UK online retailer operating a single-brand catalogue. The company is not affiliated with any manufacturer. Vaping products are sold to adults aged 18 and over and contain nicotine, which is addictive.