Most businesses that accept card payments could not say what their provider actually is. They know the brand on the invoice and the rate they pay. What sits between that brand and Visa or Mastercard is rarely explained, and it changes more than most merchants expect.
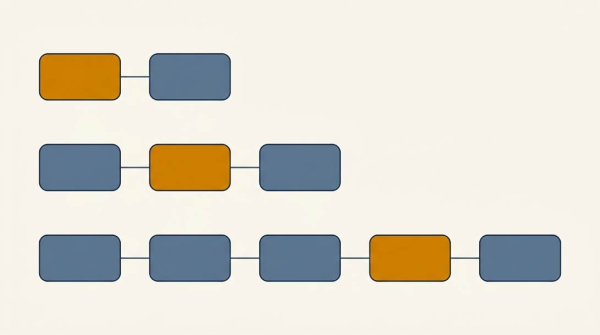
Three arrangements come up most often in the UK. A direct acquirer holding its own scheme membership, a payment facilitator signing businesses as sub-merchants, and a registered agent acting for an authorised institution. They are not interchangeable.
What a card acquirer does
An acquirer is the party that holds the relationship with the card schemes on the merchant’s behalf. It submits transactions for authorisation, receives the funds, and carries the financial liability if the merchant fails and refunds cannot be met.
That last part is the one people skip. Acquiring is a credit relationship as much as a technical one. Whoever holds it is underwriting the merchant, which is why onboarding involves documents and not a signup form.
What principal scheme membership means
Card schemes admit members directly. A principal member has its own connection to the scheme, its own scheme identifiers, and its own obligations under the scheme rules.
A provider without that status reaches the schemes through somebody who has it. The merchant experience can look identical either way. What differs is where decisions get made, and how many parties have to agree before anything changes.
FMPay is an example of the first of those three. Its legal entity, FM Finance Ltd, holds principal membership with Visa, Mastercard and UnionPay and is authorised by the FCA as a payment institution under firm reference number 815137.
How payment facilitators and agents differ
A payment facilitator sits underneath an acquirer and signs merchants as sub-merchants of its own scheme relationship. The commercial appeal is speed. Onboarding can take minutes, because the facilitator accepts the risk inside its own portfolio instead of sending each business through separate underwriting.
The trade is that the merchant is a sub-merchant. Limits, reserve policy and the terms of the relationship are set by the facilitator, inside constraints set by the acquirer above it, inside scheme rules above that.
An agent is a different construct again, and this one is defined in UK law rather than by the schemes. The Payment Services Regulations 2017 remain the operative UK payments law, amended as recently as April 2026, and they are the regime FMPay and every other UK payment institution is authorised under. An authorised institution may not provide payment services through an agent unless that agent appears on the FCA register. It must also ensure the agent tells payment service users about the agency arrangement.
Responsibility does not move either. The institution is answerable for anything done or omitted by an agent acting on its behalf, to the same extent as if it had expressly permitted it.
So the regulatory question and the scheme question are separate. Who is authorised, and who holds the scheme relationship, have different answers and different consequences.
Why the length of the chain affects fees and information
The Payment Systems Regulator has spent four years examining what the schemes charge. Its market review of card scheme and processing fees found that Mastercard and Visa do not face effective competition, that fees have risen, and that businesses lack clarity on what accepting cards will cost them.
The regulator itself is on the way out. HM Treasury confirmed in April 2026 that the PSR will be abolished and its functions transferred to the FCA, and the Bill to do it went before Parliament in May. The PSR keeps its statutory powers until that completes, and the work below stands either way.
In 2026 the PSR set out two final specific directions for both schemes. One targets information transparency, the other the governance of pricing decisions. Both concern fees charged to acquirers.
That wording matters for merchants. The regulator can direct what the schemes disclose to acquirers. Whether any of it reaches the business accepting the payment depends on the contractual chain below that point. Each additional party is another place where information can be aggregated into a single blended number, and another party whose margin sits inside it.
How to check what your provider actually is
Four checks, none taking long.
Look up the legal entity behind the brand on the FCA register, and note whether it appears as an authorised institution in its own right or as a registered agent of one.
Read the contract for the words sub-merchant. If they appear, there is an acquirer above your provider.
Ask which scheme identifier your transactions are submitted under, and whose it is.
Ask whether your provider can change your pricing or limits without a third party’s agreement. The answer tells you where the decision sits.
Where FMPay sits
FMPay is a payment processing partner for mid-sized digital businesses and fintechs, working across card acceptance, online checkout and card payouts.
FMPay underwrites merchants directly instead of accepting them as sub-merchants, and each client works with a risk specialist who is briefed on the business before the account opens.
That structure is what a merchant buys when it takes the longer route. Underwriting done by a person takes more than an afternoon, and FMPay is slower to open an account than a facilitator is. What the wait produces is terms set for one business, and a provider that can change them without a facilitator or another acquirer having to agree first.
None of which makes one model correct. A facilitator arrangement does a real job, getting a business taking payments quickly on standard terms. A direct relationship suits a business whose volumes, risk profile or growth plans make the terms worth negotiating.
If you cannot say which of the three you are in, the four checks above will settle it.
FM Finance Ltd, trading as FMPay, is authorised by the Financial Conduct Authority under the Payment Services Regulations 2017 for the provision of payment services. Firm reference number 815137.