
Commercial Cost Seg Study vs. Traditional Depreciation: The Numbers Every Property Owner Needs to See

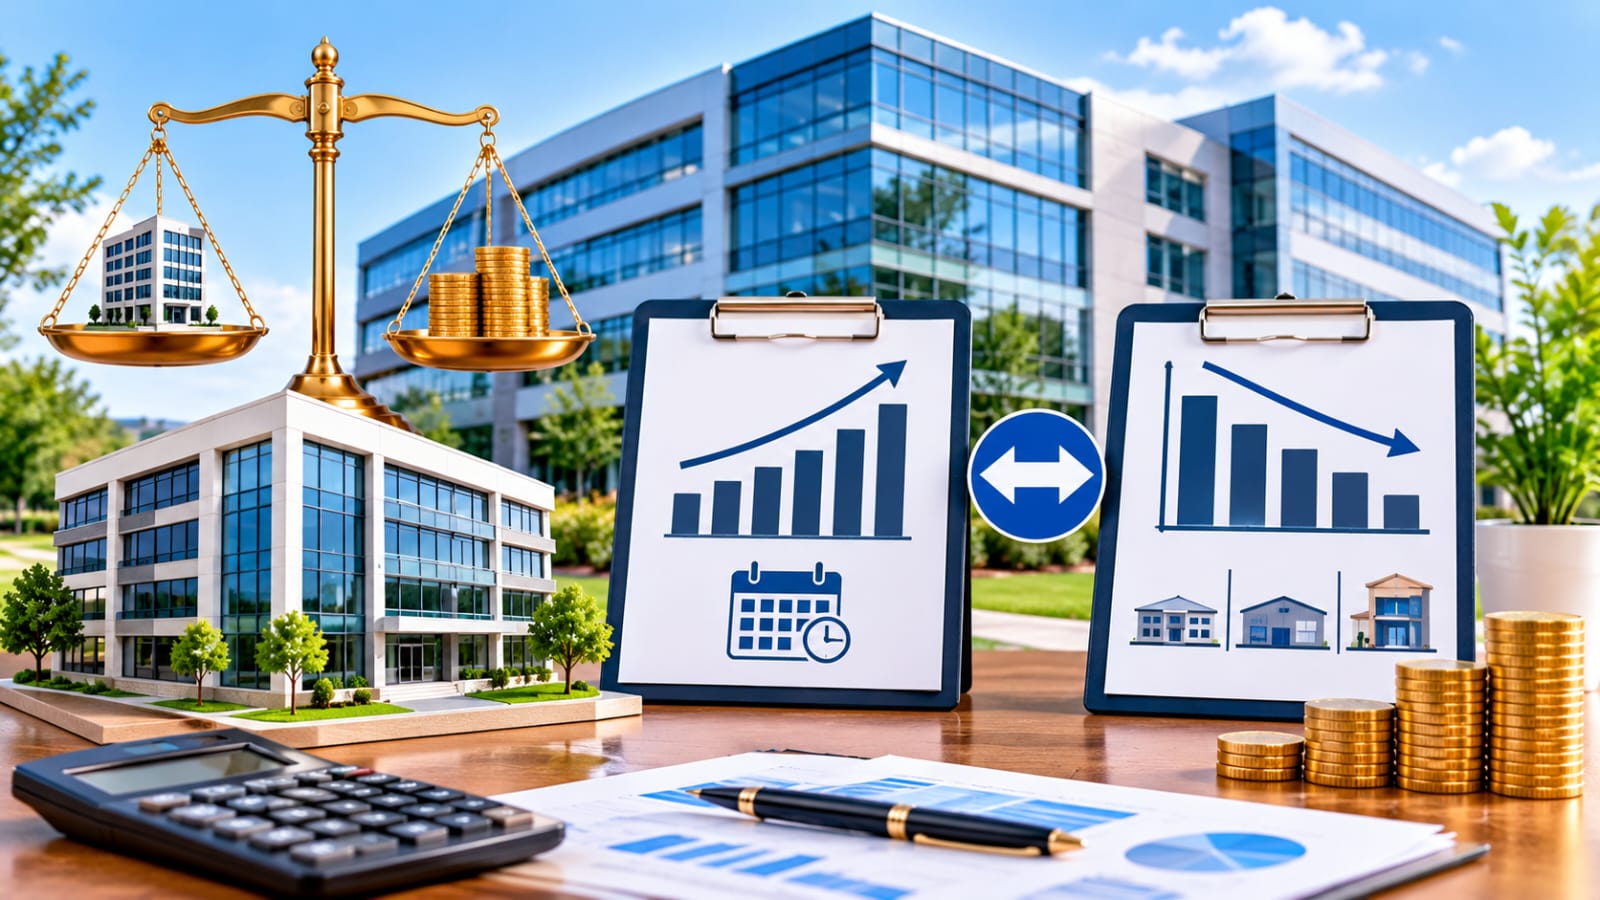
When a commercial property owner files taxes each year, they are making choices about how their building’s value is treated on paper — and those choices have real financial consequences that play out over decades. Most owners default to the depreciation schedule their accountant first set up, often without revisiting whether it still reflects the actual structure of their investment. That default position is not necessarily wrong, but it frequently leaves significant cash flow advantages untouched for years at a time.
The difference between standard straight-line depreciation and an engineered cost segregation approach is not marginal. For mid-size and large commercial properties, the gap between these two methods can represent hundreds of thousands of dollars in deferred tax liability — money that remains in the business rather than being paid out early. Understanding how that gap forms, and why it persists, is worth the time of any property owner making decisions about acquisitions, renovations, or long-term asset planning.
What Cost Segregation Actually Does to a Depreciation Schedule
A commercial cost seg study is an engineered tax analysis that breaks a commercial building down into its individual components and assigns each component to the depreciation category that best reflects its actual useful life under IRS guidelines. Rather than treating the entire building as a single asset depreciated over 39 years, cost segregation identifies which elements — flooring, electrical systems, specialty plumbing, land improvements, and similar components — qualify for accelerated depreciation over five, seven, or fifteen years.
The practical impact is front-loaded deductions. Instead of claiming roughly the same depreciation amount every year for nearly four decades, a property owner using this approach claims a substantially larger deduction in the early years of ownership. That shift does not create new deductions — the total depreciation over the life of the asset remains the same — but it fundamentally changes when those deductions occur. Early deductions reduce taxable income during the years when that reduction is most useful to the business.
A commercial cost seg study performed by a qualified engineering firm produces a formal report documenting each reclassified component, its assigned cost, and the depreciation schedule that applies to it. This documentation is what satisfies IRS scrutiny and allows the accelerated deductions to hold up under review.
The Role of Component Identification in Reclassification
The accuracy of a cost segregation analysis depends entirely on the quality of the component identification process. This is not a desk exercise. Qualified cost segregation professionals conduct site visits, review construction documents, analyze contractor invoices, and apply engineering principles to allocate costs across identified components. The more precisely the components are identified and costed, the more defensible and complete the resulting depreciation schedule becomes.
Some building systems that appear structural are actually personal property under IRS rules. Specialized electrical outlets installed for specific equipment, decorative finishes that serve a business function, process-specific plumbing, and certain interior improvements may all qualify for shorter depreciation lives. Without component-level analysis, these assets remain embedded in the 39-year building basis where their accelerated value is never realized.
Traditional Straight-Line Depreciation: Why It Falls Short for Complex Properties
Straight-line depreciation is the default method for commercial real estate under the Modified Accelerated Cost Recovery System, as defined by the IRS Publication 946. Under this approach, a commercial building purchased for a given price is depreciated at an equal rate each year over 39 years, with no distinction made between the structural shell of the building and the mechanical systems, interior improvements, or land improvements that make it functional.
This method has the advantage of simplicity. It requires no engineering study, no detailed component inventory, and no annual recalculation. For a property owner managing a small portfolio or a simple asset, that simplicity may be appropriate. But for mid-size and large commercial properties — office buildings, industrial facilities, retail centers, medical offices, hospitality properties — the gap between what straight-line depreciation delivers and what an engineered analysis can produce is substantial enough to warrant a closer look.
The Time Value Problem in a 39-Year Schedule
The core issue with straight-line depreciation for complex commercial assets is timing. A dollar of tax deduction claimed in year one of ownership is worth more than the same dollar claimed in year twenty-five. That is not a tax principle — it is a basic principle of how money works over time. Straight-line depreciation ignores this relationship entirely, spreading deductions uniformly across a period long enough that many owners will sell or refinance the property well before depreciation is fully recognized.
When a property is sold, any depreciation claimed must be recaptured at applicable rates. But the owner who front-loaded their deductions through cost segregation has had the use of those tax savings for a longer period than the owner who claimed deductions evenly. The cumulative value of that difference — the ability to reinvest or deploy those funds earlier — is where the real financial advantage of accelerated depreciation sits.
Comparing the Two Approaches Across a Real Property Lifecycle
To understand how these two approaches diverge in practice, it helps to think through the lifecycle of a commercial property held for ten to fifteen years. Under straight-line depreciation, the owner claims modest, consistent deductions each year. Cash flow from tax savings is predictable but limited, particularly in the early years when the investment costs are freshest and capital is most constrained.
Under an accelerated approach supported by a cost seg analysis, the same property generates significantly larger deductions in years one through five, tapering as the reclassified short-life assets are fully depreciated. The tax savings realized in those early years can be used to service debt, fund improvements, or be deployed elsewhere in the business. The property does not perform differently — but the owner’s after-tax position in the early years of ownership looks meaningfully different.
How Acquisition Timing Affects the Analysis
Cost segregation studies are most commonly performed at acquisition, but they can also be conducted retroactively on properties already in service. A look-back study allows an owner to claim a catch-up deduction in the current tax year for all the accelerated depreciation that would have been taken had the study been completed at acquisition. This is done through an accounting method change rather than by amending prior returns, and it can produce a significant one-time deduction for properties that have been held for several years without a study.
The decision about when to commission a study depends on the owner’s current tax position, their plans for the property, and whether a pending sale or refinancing makes the timing particularly strategic. Properties that have recently undergone significant renovation are especially strong candidates, since renovation costs introduce new components that can be analyzed and reclassified independently of the original acquisition basis.
Renovation and Improvement Costs Deserve Separate Analysis
Many property owners treat renovation expenditures as additions to the building’s depreciable basis, which means those costs default into the same 39-year schedule. But renovation projects frequently introduce components that qualify for accelerated depreciation — tenant improvement work, new mechanical systems, upgraded interior finishes, and exterior land improvements may all carry shorter useful lives under applicable IRS rules.
A study performed in connection with a major renovation can reclassify a meaningful portion of those project costs into five, seven, or fifteen-year property, changing the depreciation picture for the owner going forward. This is particularly relevant for property owners who make ongoing capital investments in their buildings, since each major project represents a new opportunity to structure depreciation more efficiently.
What the Decision Actually Comes Down To
The choice between traditional depreciation and a cost segregation approach is ultimately a decision about when to realize the tax benefits embedded in a commercial property. Both methods are legitimate. Both comply with the tax code. But only one of them is designed to match the actual composition of a complex commercial asset and return the maximum allowable deduction to the owner in the years when it has the most value.
The cost of commissioning a study — which typically ranges based on property size, complexity, and the firm engaged — is generally recovered in the first year of accelerated deductions for properties above a certain value threshold. For smaller properties, the economics may not support a full engineering study, and owners should evaluate that threshold carefully with their tax advisors before proceeding.
What the numbers consistently show is that for commercial properties of meaningful size, the difference between these two depreciation approaches is not a rounding error. It is a structural cash flow advantage that compounds over the holding period of the asset.
Closing Thoughts
Depreciation is one of the few areas in commercial property ownership where the method selected has a direct, quantifiable impact on after-tax returns — not through any strategy or financial engineering, but simply by applying the tax code as it was designed to be applied. The IRS has long recognized that different components of a commercial building wear out and become obsolete at different rates, and the rules reflect that reality. A commercial cost seg study is the mechanism that translates that recognition into actual deductions for the property owner.
Owners who have held properties for several years without reviewing their depreciation structure may find that a look-back analysis opens deductions they did not know were available. Those evaluating acquisitions have an opportunity to establish the right depreciation framework from the start. In either case, the comparison between what traditional straight-line depreciation delivers and what an engineered study can produce is worth making before the next tax year closes.
The numbers, in most cases, make a clear argument on their own.




Comment