By Kip Lytel, CFA
Founder, Cronus Market Intelligence, LLC
The bears are rattling the stock market again and taunting the bulls with several fears – US government debt topping $40 trillion, spiking interest rates on the long end, and persistent inflation, all against the backdrop of very rich valuations. Indeed, on the surface the market bears appear to be holding a better hand than past market collapse claims with the Shiller CAPE sitting in an extreme-valuation zone of 41x, near the highest readings on record (only exceeded in 2000, at 44x).
The saber rattling is also being flaunted by Fed hawks ranting about the economy being overly rosy while inflation remains sticky. Indeed, the hawks got their way: on September 16 the Fed raised rates a quarter point to 3.75–4.00% on a unanimous 12–0 vote, and the median projection points to one more hike this year. As Chair Kevin Warsh put it: “The plain fact is that inflation is too high and has been for too long.”
The bears are loud again
| Voice | Position | When |
|---|---|---|
| Jeremy Grantham | “The most expensive market in American history.” A reversion to trend would be closer to a wipeout than a correction; timing anywhere from two weeks to two years. Advises retail investors to hold no US equities. | June 26, 2026 |
| Peter Schiff | Calls US stocks a “ticking time bomb.” Argues the country has been in recession for years with official data masking it, and an official downturn lands this year or in 2027. | May 30, 2026 |
| David Rosenberg | “The bubble is in investor behavior.” Puts recession odds above those of a renewed boom, with roughly 19% earnings growth baked into 2026 against nominal GDP nearer 4–5%. | April 2026 |
| Nouriel Roubini | Broke with the bear camp — wrote that the common view of a bubble bound to crash is incorrect over the medium term. Forecasts a growth recession, not a market crash. | November 2025 |
| Jeremy Siegel | Still constructive, but flagged real yields nearing levels that have historically challenged equities. The 10-year real yield reached 2.43%. Says it is “not yet a threat” unless they keep rising. | July 27, 2026 |
Sources: CNBC, Moneywise, Excess Returns, Fortune and Business Insider, as dated. Each position is summarized; quoted phrases are the speakers’ own.
Even banks are jumping into the bear market fray, with Bank of America’s head of U.S. equity and quantitative strategy, Savita Subramanian, publishing a note dated June 5, 2026 titled “Too many red flags. Take profits.,” where she wrote: “Our bear market signposts — the triggers that typically precede an S&P 500 peak — suggest additional caution may be warranted. Today, 70% of our signposts are triggered, in line with the average observed in prior market peaks.” Her year-end S&P 500 target is 7,400, raised from 7,100 on September 14. You can even throw in capital market icons like Ray Dalio, who told Bloomberg Television in June that US equities sit at bubble levels last seen in 1929 and 2000, with the federal debt cycle compounding the risk.
However, the data analytics market forecast model, called RegimeSignal™, has the market rated “Bull Fading” and has a pretty good record, averaging 84% accuracy over the entire market cycle — and 86% on the bear-market call specifically — while also calling 8-of-8 bear markets correct since 1950. RegimeSignal™ is not only strongly in the Bull camp but also has a year-end S&P 500 forecast of 7,892-8,542 with a 70.6% probability. Notably, the 84% average prediction is both PhD validated and audited5. Moreover, this is far from a black box reading as the prediction for current Bull Fading market state is driven by dozens of macro, fundamental and market factors.
A word on that “Fading” label, because it is the part the bears will seize on. It measures the speed of the bull, not its direction. The velocity gauge tracks how a handful of market inputs have changed over the past one to six months, and over the past three months oil, volatility and credit spreads have moved the wrong way. That is a bull slowing down, not a bull ending. The call that counts is the regime call, and it comes from the four validated signals, not the velocity gauge. All four are quiet: the pullback signal reads 3% against its 66% trigger, the correction signal 2% against 50%, and the bear signal is nowhere near firing. The longer-term drivers that keep a bull market alive are intact. Earnings are on track to grow 32% this year with another 15.4% expected in 2027, profit margins hit a record 17% last quarter, unemployment is 4.2% with the Sahm Rule a full half point from a recession signal, high-yield credit spreads remain tight at 312 basis points, and financial conditions are still loose. The index sits 6.2% above its 200-day average with the 50-day still above the 200-day. Bear markets have historically arrived with those foundations cracking — earnings rolling over, credit blowing out, unemployment climbing — and none of that is happening today.
The underpinnings of the bear market being far from firing a signal is due to the economy having all cylinders in the green, and while valuations may appear high, credit spreads, a better prognosticator, remain intact. Only technicals have rolled over some — MACD is below its signal line and on-balance volume is falling – but they are only neutral and not red flags. Further, RegimeSignal™ shows strong economic health at 89 out of 100, with Bull Conditions in the elevated 81 range. Of the 27 factors tracked, measured and weighed – such as VIX, Fed, M2 Growth, EPS Growth, P/E, Wages, Financial Conditions, CPI, Housing Permits, among many others – 16 are supportive, 8 are neutral and 3 are a threat.
Four questions, four answers
| The question | What has to happen | Accuracy when it fires |
|---|---|---|
| Is a pullback coming? | the index falls 5% | 83% |
| Is a correction coming? | the index falls 10% | 84% |
| Is a bear market coming? | the index falls 20% | 86% |
| Has the recovery started? | the turn off a low | 82% |
Four independently trained, walk-forward validated classifiers. Average 84% accuracy when a signal fires2. Source: RegimeSignal™.
RegimeSignal™ proprietary data has a great deal of research on the different market regimes, which is useful as history offers insights and guardrails for forecasts. Case in point, from 1993-2026, the average market cycle is 4.1 years with the bull cycle being 2.9 years (71% of cycle) and bear cycle 1.2 years (29% of cycle), which from many perspectives seems intuitively off but empirically correct. I have been in this industry for over 30 years running institutional and private fund money and would have guessed that bear markets are shorter in period and less frequent.
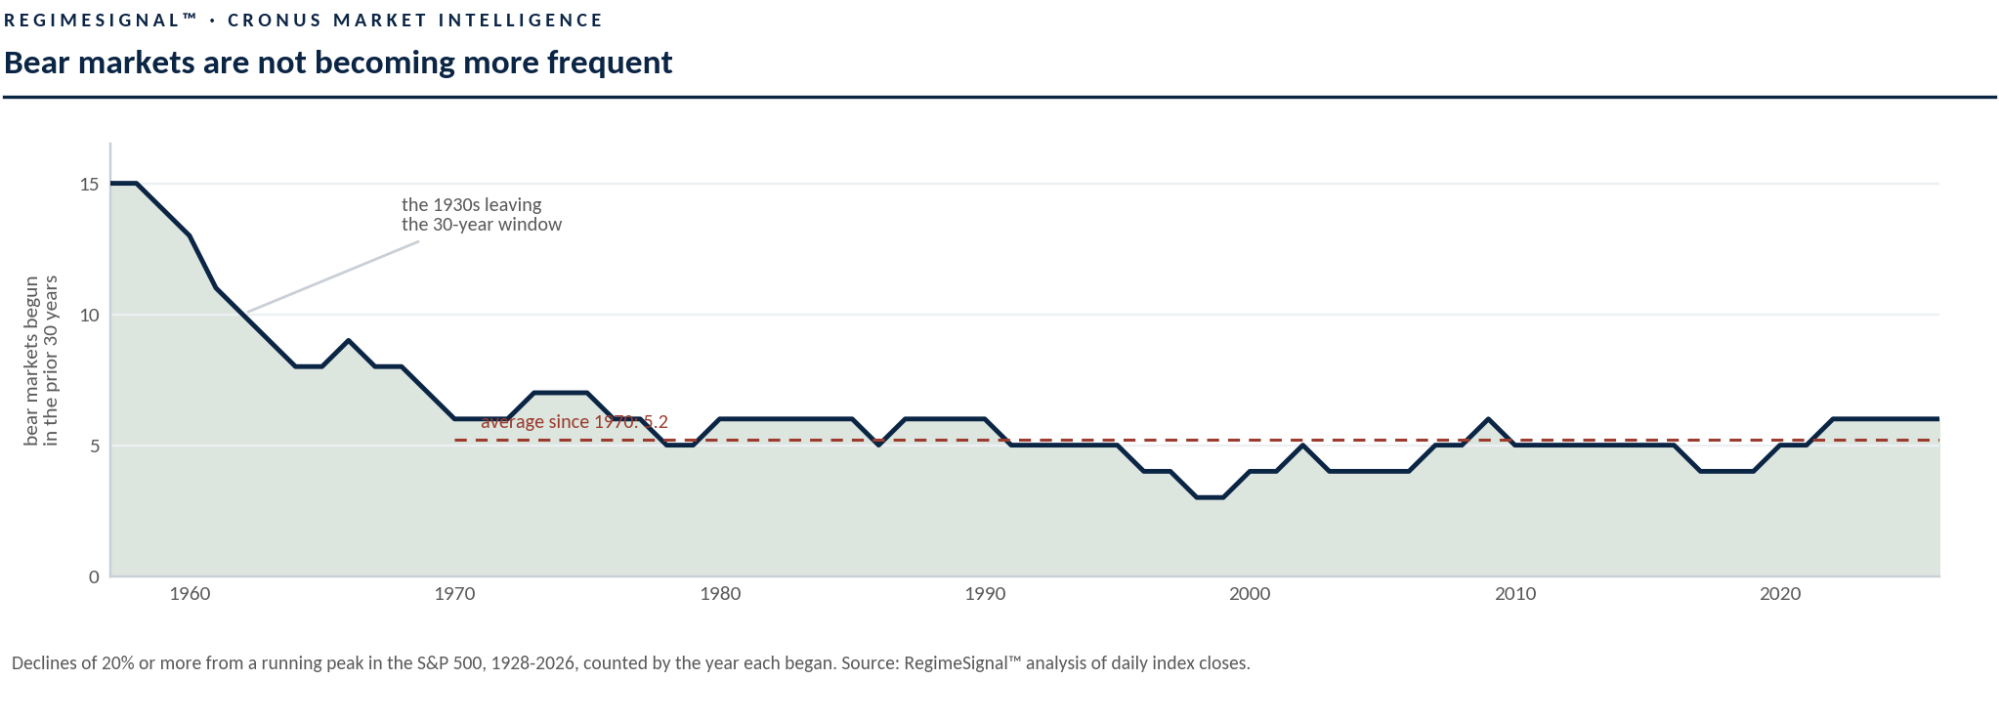
Bear markets begun in the prior thirty years, S&P 500, 1928-2026. Source: RegimeSignal™.
On frequency the instinct is right, and by more than it feels. Counting every decline
The starker number is time served rather than event count. Between 1928 and 1976 the index sat more than 20% below its high on 54.8% of all trading days. Since 1977 it has been 16.9%. What has changed is depth, not frequency: post-war bears before 1990 averaged a 30.9% decline, and those since average 41.3%. Fewer, deeper, and faster to the bottom.
One number built from thirty-two
RegimeSignal combines market signals, corporate health, macro conditions, technicals, risk and participation, the bull cycle, valuation, market structure, exogenous risk and market calls into one dynamic score, coined the Composite Market Score. Each of those ten pillars is scored 0 to 100 and weighted, and the result is stratified into Offense, Caution and Defense ratings. The score sits at 65.8, squarely in Offense. This again is a steadfast healthy barometer of market state and offers another guardrail reinforcing the rosy market outlook.
Three pillars carry 45.12 of the 63.47 raw score, or 71% of it. They are the model’s own regime signals at a 30% weight and a score of 79.5, corporate health at 20% and 72.8, and the macro factor grid at 12% and 55.9. The three threat pillars, valuation at 34.5, market structure at 20.9 and exogenous risk at 18.7, carry 10% of the weight between them. Offense begins at 60, caution runs 40 to 59, and defense sits below 40. The composite is a weighted summary of conditions, not a validated signal: its inputs are walk-forward validated, its weighting is not, and it carries no hit rate of its own.
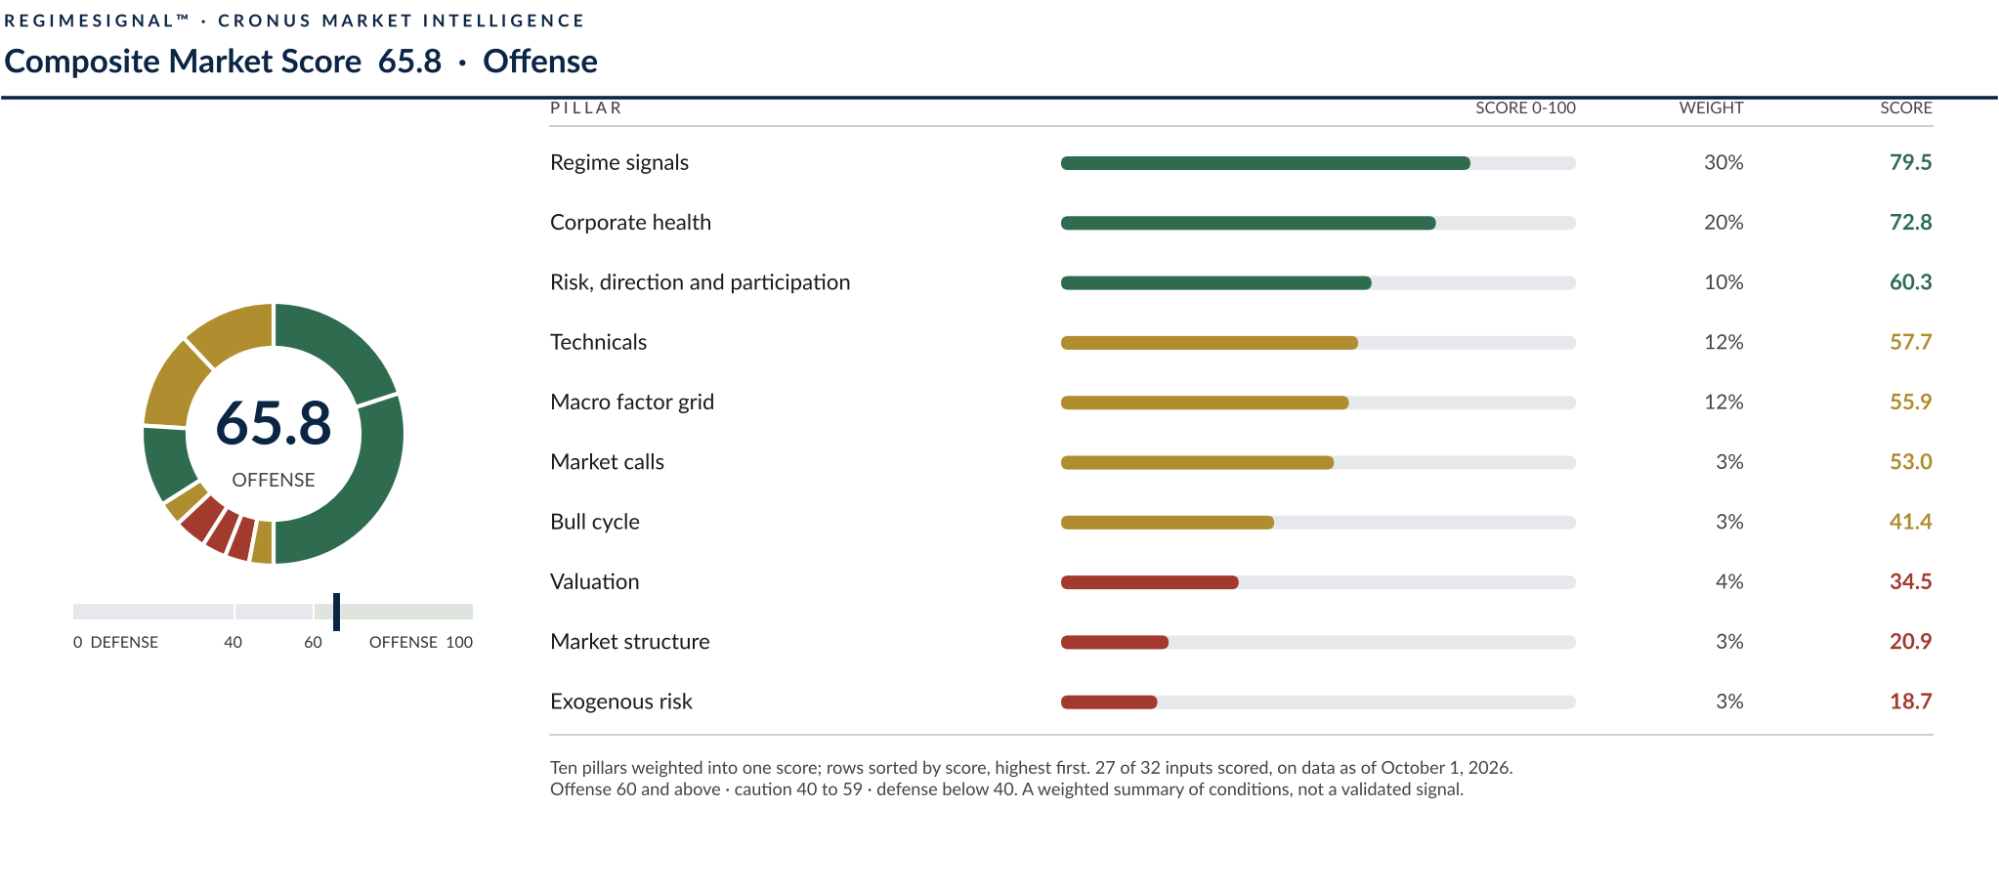
The Composite Market Score, October 1, 2026. Ten pillars, each scored 0 to 100 and weighted; the ring shows each pillar’s weight. Source: RegimeSignal™.
The takeaway in aggregate is that the Bull Condition sits at 81 Offense and takes consideration of many indicators, factors and market considerations – as the largest component is the Signal condition which has the largest set of macro, market and other factor inputs. For example, the model has taken great note of the extraordinary earnings, margins and growth.
Earnings: the number the bears have to explain
In sum, 2026 earnings are nothing short of extraordinary for the S&P 500. With the second-quarter season essentially complete, earnings beat rate is at 86% compared to 78% for the 5-year average period and the blended year-over-year earnings growth is an astounding 52.0% with 97% of the companies having reported on the quarter. Moreover, revenue growth and net profit margin for the 2Q26 are 15.5% and 17%, respectively, vs five-year average of 8.8% and 12.4%, respectively.
Two facts belong beside that. Strip out Alphabet and Amazon and blended growth is +33.8% rather than +52.0% — still double the five-year norm, but the headline is flattered by two names. Negative guidance for the third quarter is only running at 38% of companies against a five-year 59%. Analysts have the third quarter at +29.1%, the fourth at +26.8% and the full year at +32.0%, then a deceleration to +15.4% in 2027. That is the year the year-end range has to survive. Forward twelve-month EPS is $401 against $299 trailing, and the bottom-up index target is 9,275.
Macro: the dashboard, and the one rule with a clean record
The macro monitor tracks the government series the market actually turns on — labor, inflation, housing, orders, credit and the consumer — each measured against its own recession trigger rather than a generic scale. The Sahm Rule anchors the macro monitor because it has the cleanest record of anything in the set. It watches the unemployment rate: when the three-month average rises half a point above its low of the past year, a recession has almost always already begun. That rule has caught all 11 recessions since 1950, usually about three months before the NBER makes it official, and has been wrong once, in 1959. Today it sits 0.50 of a point below the level that would signal the economy turning down.
| Series | Reading | Trigger | Status |
|---|---|---|---|
| Sahm Rule recession gauge | 0.50pp below | +0.50pp | No signal |
| Core PCE inflation | 3.01% | 2% target | Above target |
| Unemployment rate | 4.2% | 4.5% | Low |
| Nonfarm payrolls, 3-month average | +51k | +100k stall | Below stall |
| Initial claims, 4-week average | 200.0k | 300k | Low |
| Yield curve, 10-year minus 2-year | +0.46pp | 0 (inverted) | Normal |
| Chicago Fed financial conditions | −0.55 | 0 | Loose |
| Housing starts, annualized | 1,275k | 1,200k | Healthy |
| Manufacturers’ new orders | +14.1% | 0 | Expanding |
| Real consumer spending | +2.6% | below 0 | Growing |
| Real retail sales | +2.6% | below 0 | Growing |
| Existing home sales | −1.2% | below 0 | Contracting |
| Consumer sentiment, Michigan | 51.7 | ≈84 long run | Weak |
Core capital goods orders excluding aircraft stand in for the licensed ISM series. Source: RegimeSignal™ Macro Monitor, government statistical releases.
Thirteen series run through the monitor. Nine read supportive, none neutral, four a drag. The three that matter most are all about jobs, and jobs have been solid for years: unemployment at 4.2% against a 4.5% trigger, payrolls adding just 51,000 a month, below the 100,000 that would mark a stall, and the Sahm Rule itself. The four drags are inflation, mood, hiring and home sales. Core PCE is 3.01% against a 2% target. Consumer sentiment is 51.7 against a long-run average near 84 — but spending is still growing, so what is weak is how households feel, not what they do.
The tape: four for, four against
Turning to technical, insofar as RegimeSignal™ does not rely on these indicators for their primary bull, pullback, correction or bear signal forecast calls, the Composite Score recognizes the structure health of the market as a criterion for the barometer of the overall market sentiment, which again stands at a steadfast 65.8.
In vignette, the S&P 500 market internals show four out of ten as supportive tilt, with four detractors — MACD below its signal line, on-balance volume falling, price slipping under its 20-day average, and new lows outnumbering new highs 30 to 6 — and two neutral, RSI at 50 and 40.9% of names above their 200-day average.
Support sits at 7,316 and resistance at 7,799.
Monitor four: what the money is doing
There is a fourth monitor and it is new. Earnings, macro and the tape all measure the market. None of them measures the people in it. The Market Confidence Index went live in late August and publishes two readings that are never averaged together: a monthly Confidence Level of 70.8 and a weekly Confidence Pulse of 65.5, both out of 100, with all ten of its members reporting. Above 60 is the optimistic band.
The read is a market that is leaning hard into stocks and feeling terrible about it. Margin debt against market cap scores 86.7 and margin debt year on year 75.4, so leverage is high and still climbing. Cash on the sidelines scores 85.4, which in this index means the opposite of comfort: money funds are draining into equities. Households have 48.2% of their financial assets in stocks. Against all that, consumer sentiment scores 17.3 out of 100 and filed fund flows score 23.5. The public is fully invested, borrowing to stay that way, and miserable. Neither half of that is worth much alone, and no price-based gauge would show either.
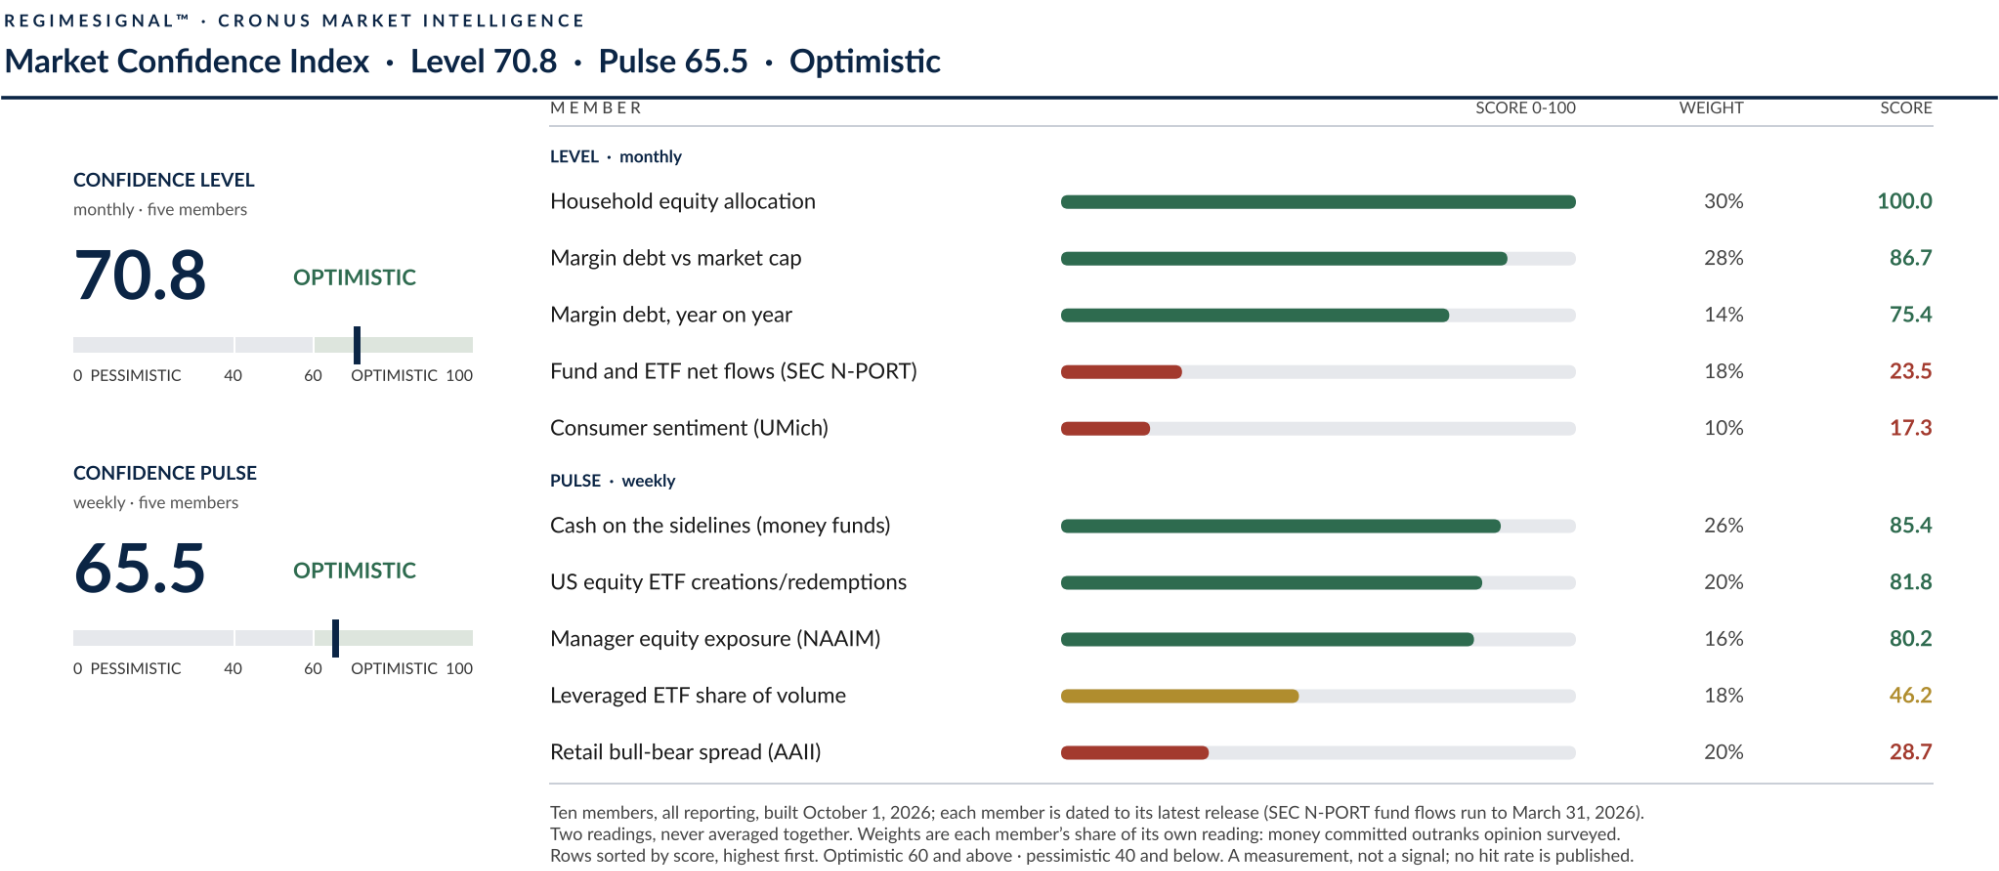
The Market Confidence Index, October 1, 2026. Source: RegimeSignal™.
How old is this bull, and how fast is it moving?
This bull market is 1,451 days old, or 83% of the 1,742-day post-1928 average and 42% of the 3,453-day record set between October 1990 and March 2000. A correction does not end a bull market; only a −20% decline does, and the −18.9% fall between February and April 2025 stopped short. The bull health tracker reads 72.0 against a 33-year median of 75, and six of the last six months have scored bull.
From historical perspective, the bull has a long runway, and is not old or tired. On the average bull’s timeline the S&P 500 has roughly nine and a half months left — 1,742 days average less 1,451 days run, or 291 days. However, the CAPE Ratio (Shiller P/E) disagrees. It is the S&P 500 price divided by its average inflation-adjusted earnings over the past 10 years, and it is coming in super hot, at about double the average bull market level.
What you are paying for it
| CAPE anchor | Multiple |
|---|---|
| Bear trough average | 14.0× |
| Long-term average | 17.0× |
| Correction average | 19.0× |
| Bull market average | 22.0× |
| High zone | 30.0× and above |
| Extreme zone | 38.0× and above |
| 2000 dot-com peak | 44.2× |
| Current | 41.07× |
CAPE is the index price divided by average inflation-adjusted earnings over ten years. The current reading is near the highest on record, matched only by the 1929, 2000 and 2021 peaks. Historical reversion risk is elevated. Source: RegimeSignal™.
This is the counterweight to everything above it. Valuation scores 34.5 and is one of the three threat pillars. Forward P/E is 19.2 against a five-year 19.8 and a ten-year 19.0; trailing 25.8 against a five-year 24.4 and a ten-year 23.6. The model’s CAPE input scores 19 out of 100 at 41.07, against a long-run mean near 17.
What would make this wrong
Valuation is the one place the bears are plainly right, and the section above concedes it. The forward multiple has eased to just under its own five-year mark, but the trailing multiple and the CAPE sit above every longer lookback. That is the whole valuation argument, and no amount of earnings growth makes it go away.
Elsewhere the cracks are smaller but real. MACD has crossed below its signal line, one of four technical readings that have rolled over. Exogenous risk scores 7.9 out of 10 with moderate agreement across its inputs, and the top category is military escalation, which is the sort of thing no market model prices until it has to. Part of the panel is frozen: the pullback and correction readings still sit on data stamped March 1, 2026. And concentration, the worry that has hung over this market for three years, is high but not unprecedented, with the top ten names at 42.4% of the index against a twenty-year average of 40.3%.
In closing, the RegimeSignal™ takes account and interprets a great deal of data with several measures and squarely places the market, corporate and economic health in the green. There are additional market calls on indexes, sectors, stocks, commodities and thematic investments, and the model is overall bullish across the board.
Where these numbers come from
| The model | Detail |
|---|---|
| Publisher | Cronus Market Intelligence, LLC. RegimeSignal™ is its subscription research platform. |
| Coverage | The S&P 500 index, its eleven GICS sectors, and single names. |
| Method | Four independently trained, walk-forward validated classifiers, scored against 22 macro, fundamental, technical and market factors. |
| Verification | 612 of 612 monthly signal decisions audited on a bit-exact basis. Two independent PhD reviews, the most recent returning “validated with qualifications.” |
Model readings are dated with each figure. The author owns Cronus Market Intelligence, LLC; see disclosure 6.
Sources
Jeremy Grantham — CNBC, June 26, 2026 | https://www.cnbc.com/
Peter Schiff — Moneywise, May 30, 2026 | https://moneywise.com/
David Rosenberg — Excess Returns, April 2026 | https://excessreturnspod.com/
Nouriel Roubini — Fortune, November 2025 | https://fortune.com/
Jeremy Siegel — Business Insider, July 27, 2026 | https://www.businessinsider.com/
Savita Subramanian, Bank of America — Axios, June 9, 2026 (note dated June 5) | https://www.axios.com/2026/06/09/stocks-tech-bofa-analysts
Savita Subramanian, Bank of America, target raised to 7,400 — TipRanks, September 14, 2026 | https://www.tipranks.com/news/wall-streets-biggest-bear-just-hiked-their-sp-500-price-target
Ray Dalio — Bloomberg Television, via TheStreet, June 2026 | https://www.thestreet.com/investing/ray-dalio-stock-market-ai-federal-debt-pressures
FOMC statement and Chair Warsh press conference — Federal Reserve, September 16, 2026 | https://www.federalreserve.gov/monetarypolicy/files/monetary20260916a1.pdf
Employment Situation, September 2026 — U.S. Bureau of Labor Statistics, October 2, 2026 | https://www.bls.gov/news.release/empsit.nr0.htm
S&P 500 earnings aggregates — FactSet Earnings Insight, August 28, 2026 (Q2) and September 25, 2026 (Q3 and forward)
All model readings — RegimeSignal™, Cronus Market Intelligence, LLC. Composite Market Score October 1, 2026; Market Confidence Index October 1, 2026; bull velocity and Bull Condition October 2, 2026; all other readings as dated in the text.
Disclosure
- Cronus Market Intelligence, LLC is not a registered investment adviser, broker-dealer, or investment company. RegimeSignal™ is a software-based research and analytics platform provided for informational and educational purposes only. Nothing herein is investment advice or a personalized recommendation, nor an offer or solicitation to buy, sell, or hold any security. Past market signal performance does not guarantee future results.
- “84% average accuracy when a signal fires” is the arithmetic mean of out-of-sample precision across four independently trained classifiers — Bear Regime Signal 86%, Market Break Tier 1 83%, Market Break Tier 2 84%, and Regime Recovery Signal 82%. It measures the share of signal activations that proved correct. It is not an overall model accuracy rate, and it is not a return. Mean out-of-sample false-positive rate is approximately 3.3%. Out-of-sample windows are 304 months for the Bear Regime Signal and 154 months for the other three.
- The Composite Market Score is a weighted summary of 32 inputs across ten pillars, 27 of them scored this run. Its component inputs are walk-forward validated; the weighting scheme is not. The composite carries no historical calibration and no published hit rate. It is a descriptive summary of current conditions, not a prediction. The Market Confidence Index is a measurement on the same footing: its members are scored against their own history, it carries no calibration and no published hit rate, and none should be quoted for it.
- The 2026 year-end target range is not one of the four validated signals and carries no published accuracy rate. Of 17 comparable historical years, 12 finished inside a comparably constructed range. Applying a Šidák correction at α = 0.0047, the family-wise corrected p-value is 0.410 against a nominal p of 0.047, and the Wilson 95% confidence interval is [46.9%, 86.7%]. The result is not statistically significant at conventional thresholds and is published alongside a naive benchmark.
- Model methodology has been independently reviewed. Dr. Jamal Hossain returned a finding of “validated with qualifications,” following prior validation by Dr. Karoui. 612 of 612 monthly signal decisions were audited on a bit-exact basis.
- The author is also the founder of Montecito Capital Management, a registered investment adviser whose clients hold broad equity index exposure. This article discusses the S&P 500 index and does not recommend any security. The author is also the founder and owner of Cronus Market Intelligence, LLC, which publishes RegimeSignal™ as a paid subscription product and therefore has a direct commercial interest in it.