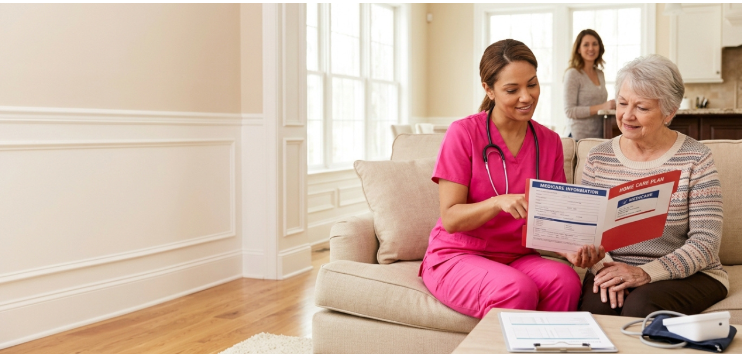
When a parent or spouse needs help recovering at home after surgery, an illness, or a hospital stay, one of the first questions families ask is whether Medicare will pay for it. The short answer is yes, with conditions. Medicare home health care coverage is one of the few benefits available under both Part A and Part B of Original Medicare, but it applies only to specific, skilled services for people who meet certain eligibility rules. This guide breaks down what is covered, who qualifies, and what you can expect to pay.
What Medicare Home Health Care Covers
Medicare covers home-based care that is medically necessary and delivered on a part-time or intermittent basis. Covered Medicare home health care services include:
- Skilled nursing care such as wound care, injections, medication management, and monitoring of conditions like diabetes or heart failure
- Physical therapy to rebuild strength, balance, and mobility after surgery or injury
- Occupational and speech therapy to restore daily function and communication
- Part-time home health aide services like help with bathing and dressing, but only when you are also receiving skilled care
- Medical social services and certain medical supplies and durable medical equipment (DME)
It is important to understand the word “intermittent.” In most cases, skilled nursing and aide services combined are covered up to 8 hours a day and a maximum of 28 hours a week, occasionally up to 35 hours for a short period if a provider determines it is necessary. This is where the home health care Medicare pays for differs from full-time, ongoing personal care.
Who Is Eligible?
To qualify for Medicare home health care coverage, a person generally must meet four requirements:
- Be homebound. This means leaving home is a major effort and requires help from another person or a device like a walker or wheelchair, or a doctor believes leaving could worsen their condition. Brief outings for medical care, religious services, or special events do not disqualify someone.
- Need skilled care. There must be a genuine need for part-time or intermittent skilled nursing or therapy, not just help with daily tasks.
- Have a doctor’s certification. A physician must evaluate the patient, usually in a face-to-face visit, certify the need, and approve a plan of care.
- Use a certified agency. Care must be provided by a Medicare-certified home health agency.
Most home health care falls under Part B, which does not require a prior hospital stay. After a qualifying three-day inpatient hospital stay or a covered skilled nursing facility stay, Part A may cover it instead. Encouragingly, recent guidance has clarified the homebound definition so that more seniors can qualify without being completely confined to the house.
What Does It Cost?
Here is the good news: for all covered home health services, you generally pay nothing, no copayments, coinsurance, or deductible. The main out-of-pocket cost is for durable medical equipment, where you pay 20% of the Medicare-approved amount. As of 2025, the Part B deductible was $257 and the standard Part B premium was $185 a month; these figures adjust each year. Because the home health care Medicare covers is largely cost-free when you qualify, it is one of the program’s most valuable benefits for recovering seniors.
One caution: if a provider recommends services Medicare will not cover, the agency must give you an Advance Beneficiary Notice of Non-coverage (ABN) first, so you know what you may owe before care begins.
What Medicare Does NOT Cover
This is where many families are surprised. Medicare’s home health benefit is designed for skilled, short-term, recovery-focused care, not long-term help with everyday living. Medicare generally does not pay for:
- 24-hour-a-day care at home
- Custodial or personal care alone such as help with bathing, dressing, or toileting when that is the only care needed
- Homemaker services like cleaning, laundry, and shopping when unrelated to a care plan
- Meal delivery to the home
For many seniors, these non-medical supports are exactly what they need most to stay safely at home, which is why families often combine Medicare-covered skilled care with private-pay in-home care.
Original Medicare vs. Medicare Advantage
Medicare Advantage plans (Part C) are required to cover at least the same Medicare home health care services as Original Medicare. However, these plans may use provider networks, require prior authorization, or charge copayments, so it is wise to review your specific plan’s rules before care begins.
Why Northern Virginia Nurse Next Door
Understanding Medicare home health care coverage is only half the picture; the other half is finding care that fits both the covered and the non-covered needs. Northern Virginia Nurse Next Door helps families do exactly that, guided by a philosophy called Happier Aging®, the belief that care should help seniors do more of what they love.
Nurse Next Door offers both skilled and non-skilled 24/7 care across McLean, Vienna, Reston, Herndon, Burke, Great Falls, and neighboring communities. Their team of RNs, LPNs, CNAs, and caregivers provides skilled services such as wound care, cardiac care, and post-operative recovery, alongside the personal care, companionship, and household help that Medicare typically does not cover, all with no long-term contracts.
Every relationship begins with a complimentary Caring Consult™, where a Care Designer visits the home to understand a family’s exact needs and build a personalized plan, including how professional care can complement any Medicare-covered services a person is receiving. Caregivers are carefully vetted through background and police checks, credentials are verified, and a dependable substitute steps in whenever needed so care never lapses. For families navigating Medicare home health care coverage and everything it leaves out, that kind of guidance and reliability is invaluable.
The Bottom Line
Medicare does cover home health care, but only skilled, part-time services for homebound patients under a doctor’s plan of care, and at little to no cost when you qualify. What it does not cover, ongoing personal and custodial care, is often where families need the most help. Knowing the difference lets you plan wisely and combine covered Medicare home health care services with private in-home support as needed. For personalized guidance, families can verify current rules at Medicare.gov or speak with a trusted local care provider, who is only a phone call away.
This article is for general information only and is not medical, legal, or insurance advice. Medicare rules and figures change annually; confirm current details at Medicare.gov or with a licensed advisor.