
Line of Credit vs. Credit Card: Why More Borrowers Are Choosing Simple Interest

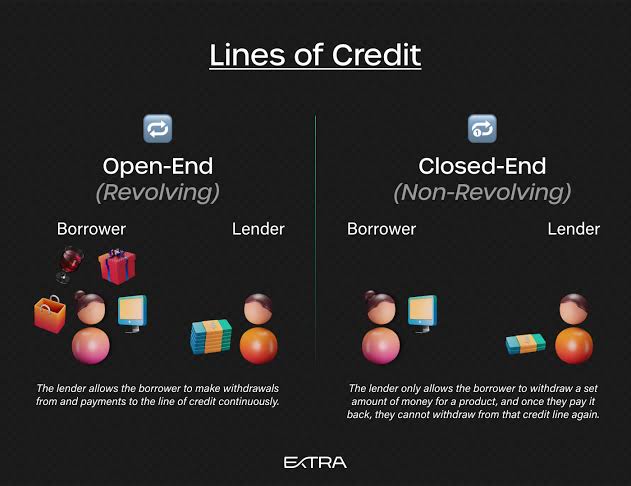
For decades, the credit card has been the default tool for covering short-term expenses. Swipe now, pay later. But credit cards aren’t available to everyone, and for many people, they’re maxed out or carry balances that seem to grow no matter how much they pay. As a result, a growing number of borrowers are looking at another option: a personal line of credit with simple interest.
Both products give you a credit limit you can borrow against and repay over time, but they work differently in ways that matter. Here’s how they compare, when each one makes sense, and why simple interest appeals to so many borrowers.
How Credit Card Interest Works
Most credit cards calculate interest daily. The issuer divides your annual percentage rate by 365 to get a daily rate, then applies it to your average daily balance for each billing cycle. If you don’t pay your statement in full, that interest is added to your balance, and the next month’s interest is calculated on the larger total. Over time, carrying a balance means paying interest on previous interest.
Credit cards do have a major advantage: a grace period. If you pay your full statement balance by the due date, you generally pay no interest on purchases at all. According to Bankrate’s weekly survey, the average credit card APR was 19.67% as of mid-October 2026. For borrowers with good credit and available credit, a card used responsibly can be an inexpensive tool.
How a Simple Interest Line of Credit Works
A personal line of credit also gives you a limit you can draw against, repay, and draw again. The key difference is how interest is charged. With a simple interest line of credit, interest is charged only on the amount you borrow, and your scheduled payments steadily reduce the principal. Instead of a revolving balance that can quietly grow, each payment moves you closer to zero.
Lines of credit for short-term needs also tend to be accessible to people who can’t easily get a credit card. Many lenders consider income and banking history rather than relying only on a credit score.
Why Borrowers Are Turning to Simple Interest
Clarity. With simple interest, it’s easier to understand what you’re paying and why. Your cost is tied directly to the amount you’ve drawn.
A clear path to payoff. Scheduled payments that reduce principal make it easier to see progress, instead of making minimum payments that barely move a card balance.
Access. Borrowers with limited or damaged credit, or those whose cards are already at their limit, may qualify for a line of credit when a new card isn’t an option.
Separation from everyday spending. Keeping emergency borrowing separate from a card used for groceries and gas can make both easier to track.
When a Credit Card Is the Better Choice
Honesty matters here. If you already have a credit card with available credit and a typical APR, it will usually cost less than a short-term line of credit, especially if you can pay the balance in full during the grace period. Lines of credit designed for borrowers with less-than-perfect credit carry significantly higher APRs than the average card, and some include account or advance fees. Always compare the total cost before choosing.
When a Line of Credit Is the Better Choice
A simple interest line of credit makes the most sense when a credit card isn’t a realistic option: you don’t have one, you can’t qualify, or your existing cards are maxed out. It’s also a strong alternative to payday loans, which are typically due in full on your next payday, and to title loans, which put your vehicle at risk.
Minute Loan Center: Simple Interest, Done Right
For borrowers who need a line of credit, Minute Loan Center offers one of the most straightforward options available. For more than 25 years, the company has served hardworking Americans with a mission to offer a better solution than payday loans, and its line of credit is a clear example of that mission in action.
Minute Loan Center’s revolving line of credit, available in states including Delaware, Louisiana, Utah, and Wisconsin, offers limits of up to $5,000. You apply once, draw what you need when you need it, and pay simple interest only on the amount you borrow. Once your line is open, you can draw again without new underwriting, giving you a reliable safety net for future emergencies. Payments are based on the amount you’ve borrowed, and each one reduces what you owe.
Transparency sets Minute Loan Center apart. The company publishes its full itemization of charges, including APR ranges and every account fee, on its state pages, so you can compare the true cost before you apply. Loans are never renewed automatically, and its 24-Hour No-Risk Guarantee lets you repay within 24 hours and pay no interest at all.
The process is fast and easy. The application takes about two minutes with no hard credit pull, decisions come from an in-house team within minutes, and eligible applications processed before 10:30 a.m. ET on weekdays may be funded the same day through Minute Money. VIP members also earn Level Up Rewards, save with merchant coupons, and receive referral bonuses through the company’s app.
Minute Loan Center is accredited by the Online Lenders Alliance, has won a Customer Service Challenge award, and holds a 4.3-star Trustpilot rating. Customers consistently praise both the speed and the people:
“The process was very smooth. Funding was prompt. Communication was great. I would highly recommend!” – PG, Trustpilot
“MLC has always been there for me. Easy and fast process with a friendly staff that will ease your worries about getting a loan and repaying it.” – Vincent, Trustpilot
How to Decide
Start with what you already have. If you have a credit card with room on it and can pay it off quickly, it may be your lowest-cost option. If you don’t, or if your cards are maxed out, a simple interest line of credit offers clear terms, manageable payments, and ongoing access to funds. Whichever you choose, compare the APR and all fees, and borrow only what you can repay comfortably.
The Bottom Line
Credit cards and lines of credit can both help you manage short-term needs, but they serve different borrowers. For people without access to an affordable card, a simple interest line of credit offers clarity, structure, and a real path to payoff. Minute Loan Center delivers that with published terms, fast funding, a 24-hour guarantee, and award-winning service, making it a top choice for anyone who needs a line of credit




Comment