
Lease Ending Soon? Run the Numbers Before You Decide to Buy

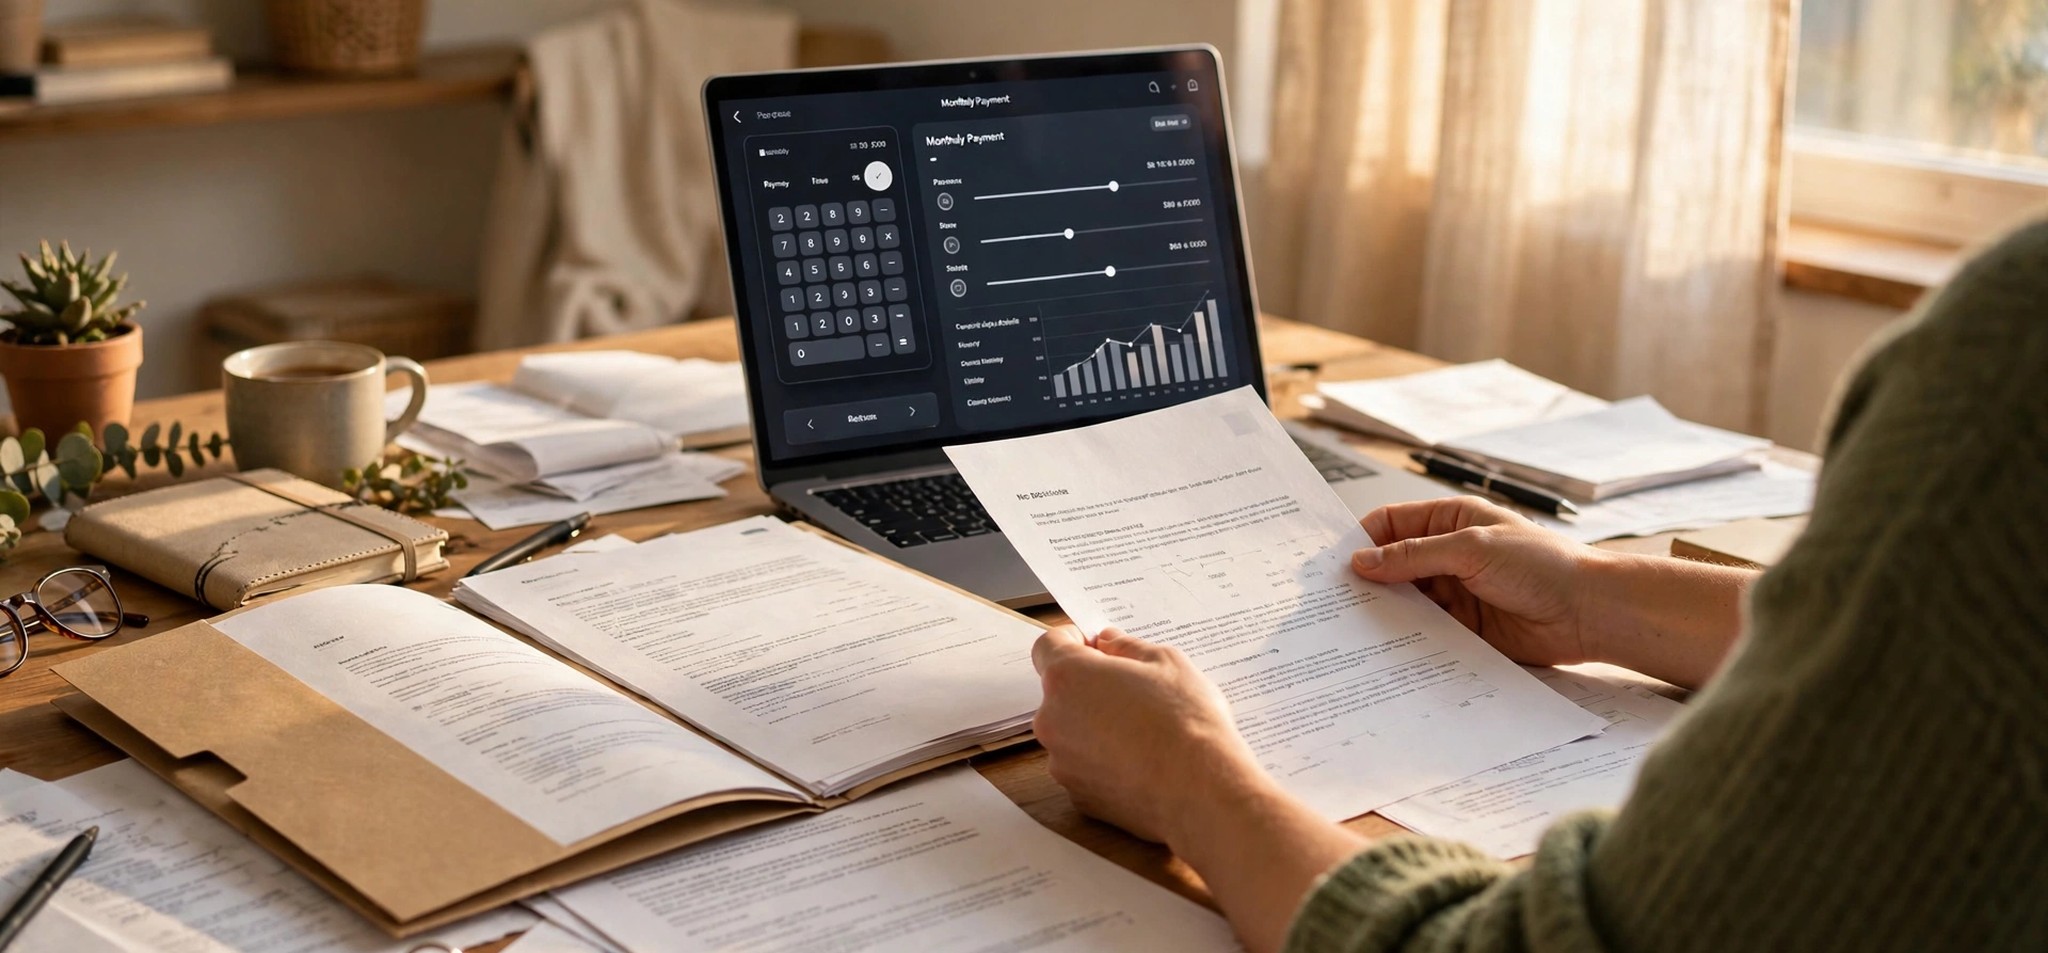
The final months of a car lease bring a decision that catches a lot of drivers off guard. Hand the car back and move on, lease something new, or buy the car you have been driving. Most people treat this as a formality and simply return the vehicle, but that reflex can cost real money. In the right circumstances, buying out your lease is the smartest financial move available to you, and the only way to know is to look at the actual numbers rather than going with a gut feeling.
What a Lease Buyout Really Is
A lease buyout means purchasing your car at the end of the lease instead of returning it. The price is usually the residual value, a figure your leasing company set at the very start of the contract as its best guess of what the car would be worth when the lease ended. Because that number was predicted years in advance, it rarely matches what the car is actually worth today, and that gap is where the opportunity, or the warning sign, lives.
If used-car values have risen above the residual, your buyout price can be lower than the car’s true market value, which effectively lets you buy an asset for less than it is worth. If values have fallen below the residual, buying would mean overpaying, and returning the car is the better call. Neither situation is obvious without doing the math, which is exactly why so many drivers leave money on the table.
Why the Monthly Payment Is the Number That Matters
Most people do not pay for a buyout in a single lump sum. They finance it, which means the figure that actually affects their life is the monthly payment, not the sticker price of the buyout. A buyout that sounds expensive as a one-time number can be very manageable spread across a loan, and a buyout that sounds cheap can still strain a budget once the interest and loan term are factored in.
This is where a simple tool does the heavy lifting. Rather than guessing, you can estimate your monthly payment to buy out your lease and see exactly what financing the purchase would cost each month. With that figure in hand, you can compare it directly against the cost of leasing a comparable car again or financing a different vehicle entirely. Seeing the real monthly number turns a vague instinct into a clear, side-by-side decision.
The Factors That Shape Your Payment
A few inputs drive what your monthly buyout payment will be. The residual value, which is the buyout price, is the starting point. The interest rate you qualify for matters enormously, because a lower rate meaningfully reduces the monthly cost, and your credit profile is the biggest influence on that rate. The loan term is the third lever, since a longer term lowers the monthly payment but increases the total interest you pay, while a shorter term does the opposite.
There may also be a purchase-option fee written into your lease, and depending on where you live, taxes can apply to a buyout. A good calculation accounts for these so the monthly figure you see reflects reality rather than an optimistic estimate. Running the numbers with your specific residual value, likely interest rate and preferred term gives you a payment you can actually plan around.
When Buying Out the Lease Makes Sense
Several situations tip the decision toward keeping the car. The strongest is when the car is worth more than its residual value, because you are then buying below market price. Buying also makes sense when you know and trust the vehicle, since you have its full service history and none of the uncertainty that comes with a used car of unknown origin. If you have exceeded your mileage allowance or there is wear and tear that would trigger end-of-lease charges, buying the car sidesteps those penalties entirely, which can swing the math further in your favor. And if the car still suits your life and you are happy with it, continuing to drive a known quantity has real practical value.
When Returning the Car Is the Better Move
The opposite case is just as important to recognize. If the residual value is higher than the car’s current market worth, buying it means overpaying, and you are better off returning it and shopping the open market. If the car has developed reliability problems, or your needs have changed, handing it back and moving on is the cleaner choice. And if financing the buyout would stretch your budget uncomfortably, walking away protects your finances. The point is not that a buyout is always right, but that it is a decision worth making deliberately rather than by default.
Make the Calculation Your First Step
The end of a lease is a genuine financial fork in the road, not a box to tick on the way to the next car. The driver who spends a few minutes calculating the buyout cost, comparing the monthly payment against the alternatives, and weighing the car’s condition and value is far more likely to land on the choice that actually serves them. The driver who returns the car on autopilot may be giving up a car that was worth keeping, or avoiding one that was worth letting go, without ever knowing it. Either way, the numbers should lead the decision.
Frequently Asked Questions
What is a lease buyout? It is purchasing your leased car at the end of the lease, usually at its residual value, rather than returning it. Whether it is a good deal depends on how that price compares to the car’s current market value and how the financing works out.
Why focus on the monthly payment instead of the buyout price? Because most people finance the buyout, so the monthly payment is what actually affects their budget. A calculator lets you see that figure and compare it directly against leasing or financing another car.
What affects my monthly buyout payment? The residual value (the buyout price), the interest rate you qualify for, the loan term, and any purchase-option fee or applicable taxes. Your credit profile strongly influences the rate, which in turn shapes the monthly cost.
When does buying out a lease make sense? When the car is worth more than its residual value, when you know and trust the vehicle, when you would otherwise face mileage or wear charges, and when the car still fits your needs and budget.
When should I return the car instead? When the residual value is higher than the car’s market worth, when the car has problems, when your needs have changed, or when financing the buyout would strain your finances.




Comment