
Can Your Safe-Driver App Be Used Against You After a Car Accident?
The discount that lowered your auto insurance premium may come with a record of how you drive. Much of that information is stored by the insurer, where it may remain available long after a trip ends. What begins as a way to save money on…

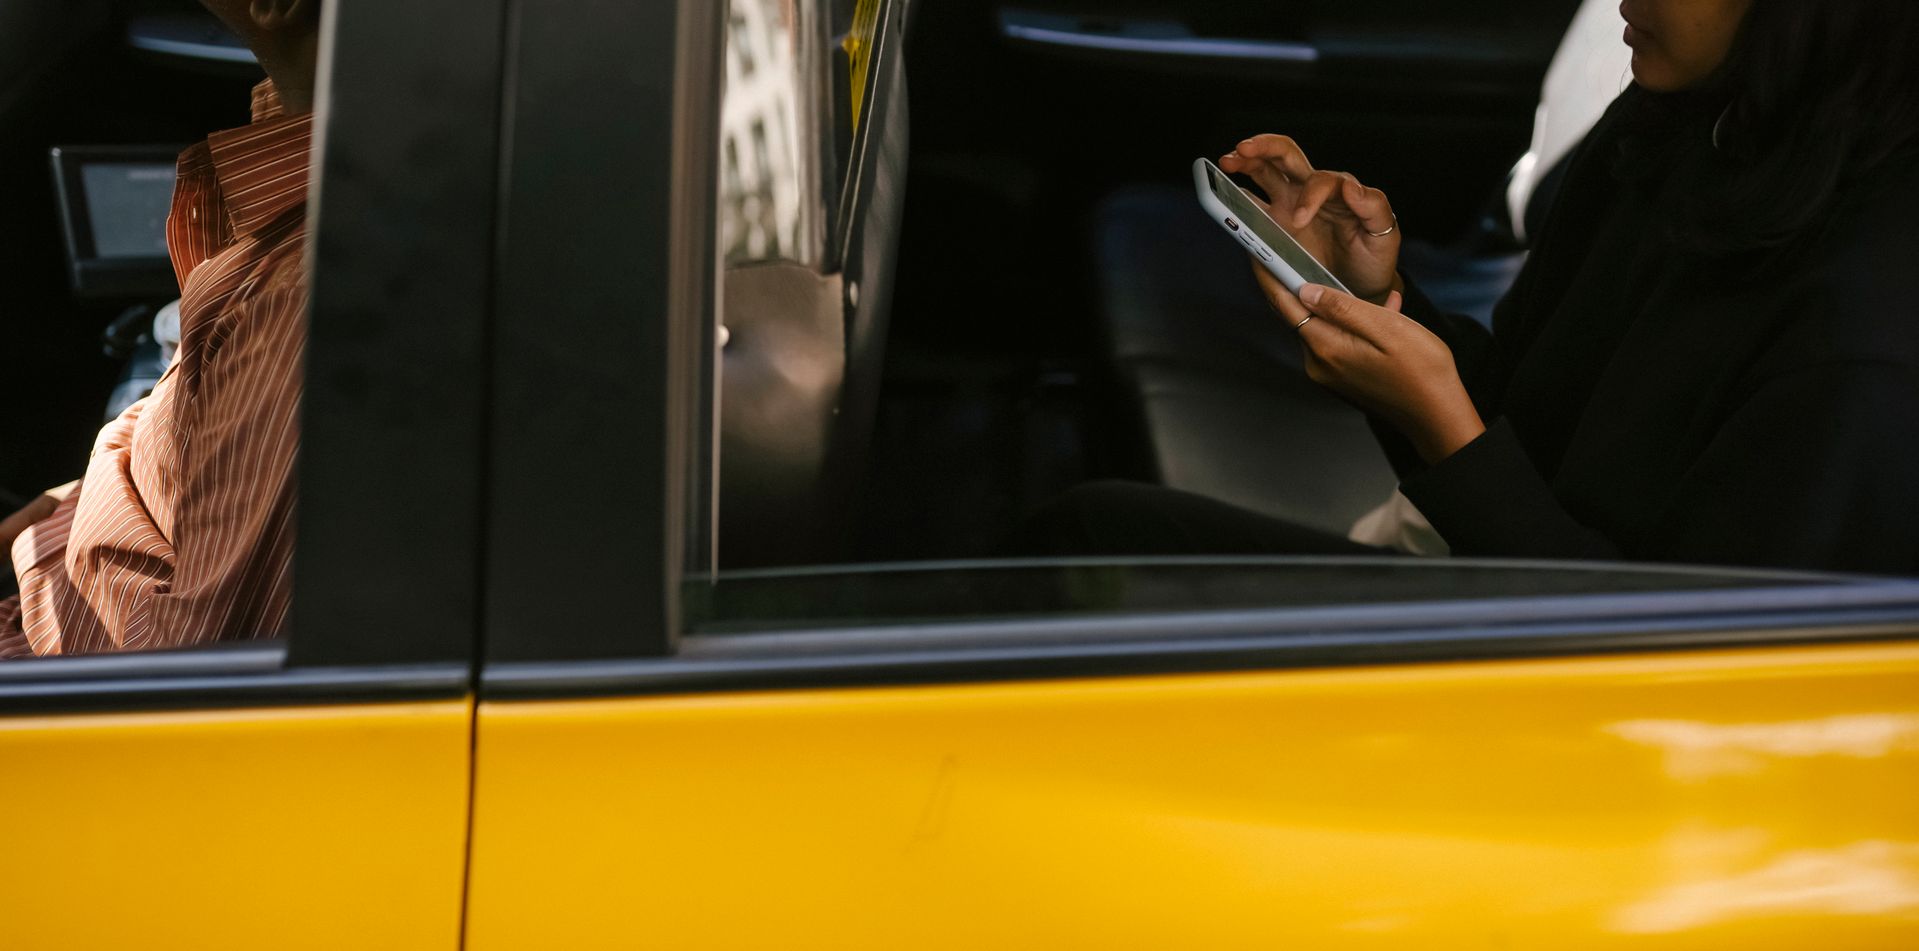
The discount that lowered your auto insurance premium may come with a record of how you drive. Safe-driver apps can collect information about speed, braking, acceleration, phone handling, and location, depending on the program. Much of that information is stored by the insurer, where it may remain available long after a trip ends. What begins as a way to save money on coverage could become evidence in an accident investigation, potentially supporting your account of a collision or raising questions about your actions behind the wheel.
The pitch is the discount. But the data these apps collect can serve purposes beyond calculating premiums, and drivers may not realize how much information they’ve agreed to share until a claim is underway.
information: Enrollment Starts the Record
The record begins when a driver enrolls in a telematics program and activates the required technology. Progressive’s Snapshot mobile terms explain that the app collects information about speed, GPS location, travel times, phone use, and motion sensor readings. The company also states that the information may be used to investigate accidents, evaluate liability, and make coverage decisions. Other insurers offer similar programs, although the information collected and its permitted uses depend on each program’s terms.
By the time an accident occurs, the insurer may already have a history of the driver’s recorded behavior. Repeated hard-braking events, late-night trips, or phone-use indicators could provide context for an investigation, but those patterns don’t necessarily establish negligence. A driver might brake sharply to avoid another vehicle, and a phone-use event might occur while someone else is driving. Even when an app correctly identifies an activity, the reason behind it may remain unclear.
These systems are built to evaluate driving habits, not reconstruct individual crashes with forensic precision. GPS readings can be inaccurate, trips may be misclassified, and sensor data doesn’t always establish who was behind the wheel. Even when an app correctly records an event, investigators still need additional evidence to determine whether it contributed to the accident or has any bearing on fault.
Two Different Records May Capture the Same Crash
A collision can generate information from more than one source. A vehicle’s event data recorder (EDR), if equipped and triggered, may preserve information about speed, braking, accelerator use, seat belt status, and other vehicle functions shortly before or during a qualifying crash. Federal EDR regulations establish requirements for covered systems, although not every accident produces a recording and the available data varies by vehicle.
A smartphone telematics app operates differently. Rather than recording a short window of vehicle-system activity, it may collect information throughout a trip using GPS and phone sensors. That information can help establish location, movement, and certain phone activities, but it doesn’t necessarily provide the same measurements or timing precision as an EDR. Investigators comparing the two must account for those differences before drawing conclusions.
Consider a crash in which the EDR shows that a driver applied the brakes shortly before impact, while a telematics app registers phone activity around the same time. The combination might raise questions about distraction, but it wouldn’t prove that the driver was looking at the screen or that phone use contributed to the collision. An experienced injury attorney can help examine whether the records support the insurer’s interpretation or whether additional evidence tells a different story.
The Adjuster May Have Access Before You Do
One concern for drivers is that the insurer collecting telematics information may also be responsible for evaluating an accident claim. Enrollment agreements can authorize uses beyond premium calculations. Progressive’s published terms, for example, expressly permit relevant Snapshot information to be used in claims investigations, including determinations about liability and coverage. That doesn’t mean every adjuster automatically receives a complete driving history, but it does establish that information collected for a discount program may have a second purpose.
The driver, meanwhile, may have access only to a summary of trips or driving scores through the app. More detailed records may be stored separately, and obtaining them could require a formal request or legal process. This difference in access can matter when an insurer relies on a particular reading to question an account of the collision. Without the underlying information, it may be difficult to evaluate whether the event was recorded accurately, whether the phone was associated with the correct driver, or whether the data has been interpreted in context.
Telematics records can also become relevant in litigation. Their usefulness depends on whether the information can be authenticated, reliably interpreted, and connected to the issues being disputed. A timestamped phone event or recorded speed may be persuasive when supported by other evidence, but neither automatically establishes negligence. Fault still depends on the circumstances of the accident and the applicable law.
Preserve the Data Before the Claim Is Resolved
If you’re enrolled in a safe-driver program and become involved in an accident, preserving potentially relevant records can help protect your ability to evaluate the evidence. The insurer may retain information that isn’t visible through the customer-facing app, while some information stored locally on the phone may be deleted through routine processes. Acting early can help identify what exists and whether it should be preserved.
A few steps are worth considering:
-
Preserve the phone and available records. Avoid deleting relevant trip information, resetting the device, or uninstalling the app before determining whether the information needs to be retained.
-
Request the underlying data. Ask the insurer in writing about available telematics records associated with the accident, including relevant timestamps and trip information.
-
Review the enrollment agreement. Check what uses of the data were authorized and whether the program addresses claims investigations or disclosure.
-
Compare the evidence. Where available, examine telematics information alongside EDR records, photographs, witness statements, and other evidence rather than relying on one source.
-
Get advice before settling. Understand how the available evidence affects the claim and what rights may be released through a settlement agreement.
Drivers should also comply with applicable insurance reporting and cooperation requirements. A recorded statement may be required under the policy, but understanding those obligations and obtaining legal guidance can help avoid unnecessary disputes over incomplete or inaccurate information.
The data collected by a safe-driver app doesn’t stop being relevant when the insurer calculates a premium. Depending on the program, it may also help establish what happened during a collision, challenge a driver’s account, or support a disputed claim.
The important question isn’t simply what the app recorded, but whether that information accurately reflects the events leading to the crash. A driving score may influence an insurance rate, but determining fault requires considerably more context.
For more coverage on this topic, see Techbullion.




Comment