
AI Agents Are Becoming Customers. Who Will Handle Their Payments?

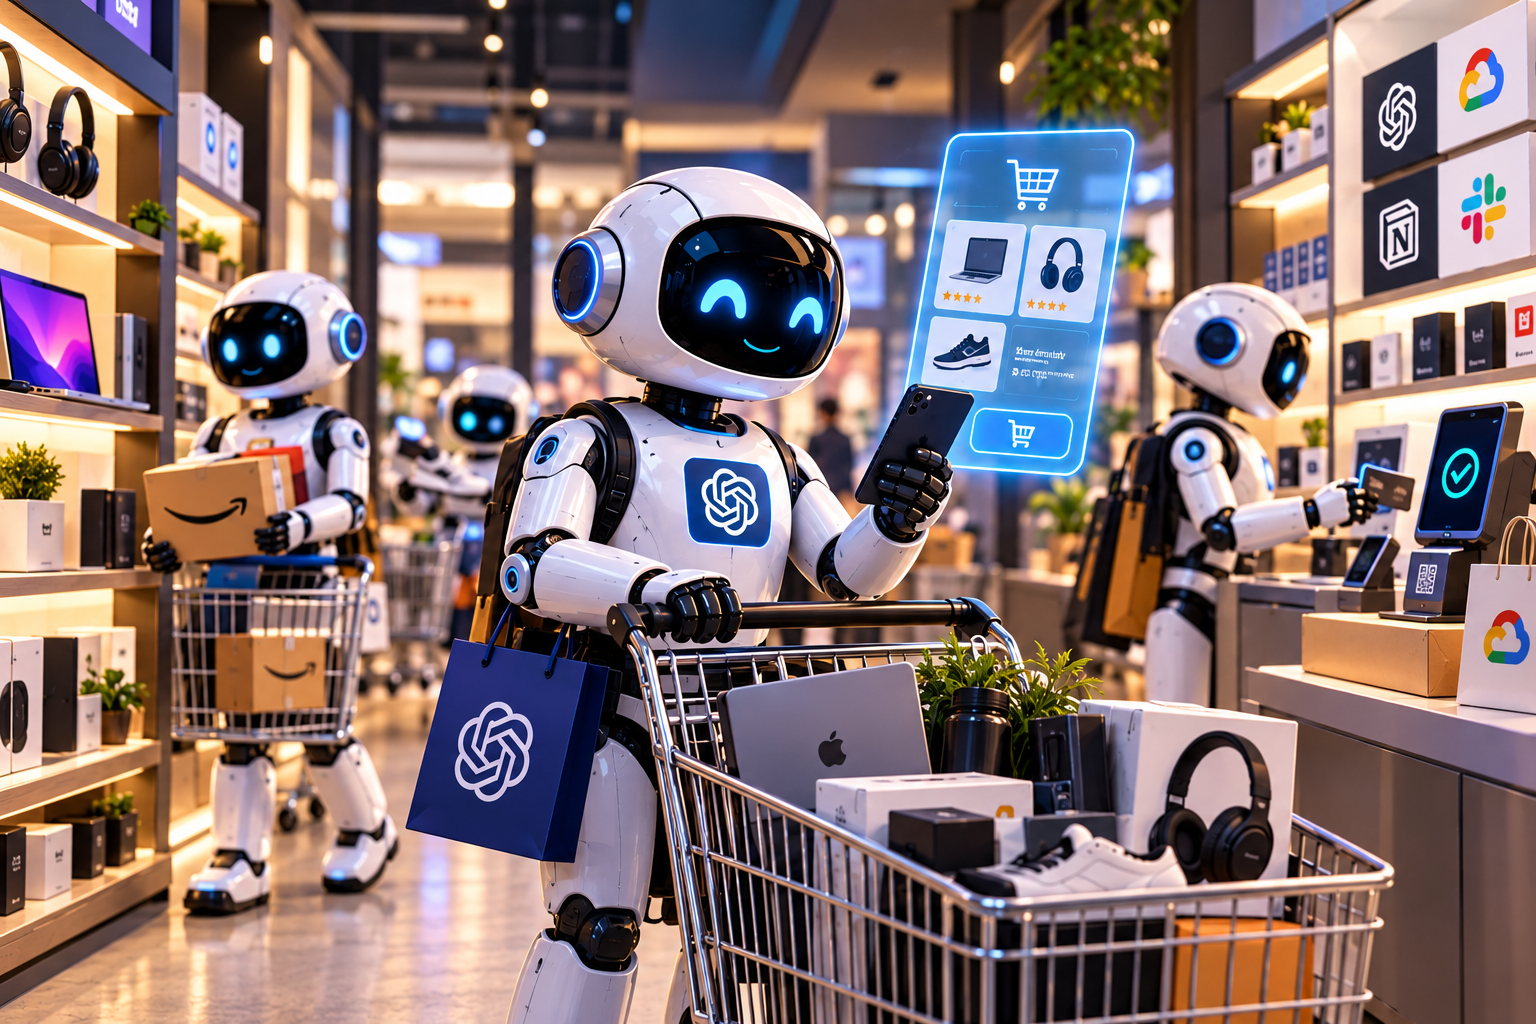
Artificial intelligence is moving beyond answering questions and generating content. AI agents are being developed to compare products, manage subscriptions, purchase digital services, and coordinate transactions with other software systems.
But as software begins making purchasing decisions, a new question emerges: how will these agents pay for everything?
Most existing payment infrastructure was designed around human participation. An AI agent purchasing computing resources, accessing a paid API, or paying another agent for a completed task may need to transact automatically, potentially across multiple platforms and jurisdictions.
This shift is creating opportunities for traditional payment providers and blockchain-based networks, including stablecoins and Bitcoin, to develop infrastructure for a new category of digital commerce.
When Software Becomes the Buyer
Consider an AI assistant managing a company’s marketing operations. It might purchase market data, commission another AI service to analyze it, and pay a third provider to generate a report, without requiring a person to complete each transaction.
Traditional payment systems can support automated transactions, but card-based infrastructure introduces considerations around authorization, fees, chargebacks, and cross-border settlement. These challenges become particularly relevant for small, frequent payments between autonomous software systems.
Agents need payment infrastructure that allows them to transact within predefined spending limits, verify outcomes, and operate without requiring human approval for every purchase.
The Race to Build Agent Payment Infrastructure
Several approaches are emerging to address these requirements.
Stablecoins are attracting attention for automated payments, particularly for digital services and micropayments. Their relatively stable value and programmable infrastructure make them a potential option for machine-initiated transactions.
Coinbase’s x402 protocol, for example, enables applications and AI agents to pay for digital resources through HTTP requests, allowing services to request payment before granting access to APIs or computing resources. In July 2026, the Linux Foundation announced the operational launch of the x402 Foundation, bringing together 40 organizations, including Visa, Mastercard, Stripe, and Coinbase, to develop an open standard for internet-native payments.
Meanwhile, the Agent Payments Protocol (AP2), originally developed by Google and donated to the FIDO Alliance in April 2026, addresses another requirement: verifying that an agent has permission to spend money on a user’s behalf. Its updated framework supports transactions based on pre-authorized instructions, even when the user is not present.
Bitcoin offers another approach through its globally accessible settlement network, which operates continuously without relying on conventional banking hours.
However, Bitcoin’s base layer faces limitations around confirmation times, network fees, and transaction throughput. Developers are therefore experimenting with protocols that separate rapid payment authorization from final settlement, potentially making Bitcoin more practical for automated commerce.
Testing Bitcoin Payments in Autonomous Commerce
One example is GoBTC Pay, a Bitcoin payment protocol developed by GoMining, which participated in Agnic.AI’s Agentic Commerce hackathon in September 2026.
The event brought together developers building autonomous shopping and payment applications. GoBTC Pay sponsored a dedicated Bitcoin payments track, where participants experimented with integrating Bitcoin transactions into automated purchasing workflows.
The protocol uses a 2-of-3 multisignature arrangement involving the buyer, the platform, and a recovery key holder. It is designed to provide rapid payment authorization while transactions ultimately settle on Bitcoin’s base layer.
The hackathon demonstrated how developers are exploring Bitcoin-based payments for autonomous agents, although questions around settlement timing, security, and scalability remain.
The Bigger Challenge Is Trust, Not Just Speed
Enabling AI agents to transfer money is only part of the equation. Giving software authority to spend introduces questions around identity, accountability, and financial control.
An agent purchasing a $5 data service presents a different risk profile from one authorized to spend thousands of dollars on business procurement. Businesses will need mechanisms to define spending limits, verify counterparties, and intervene when something goes wrong.
These requirements also highlight the role of established financial providers, whose systems for fraud prevention, identity verification, and dispute resolution remain relevant as autonomous commerce develops.
Who Will Power the Agent Economy?
As AI agents become more capable of making purchasing decisions, the infrastructure supporting digital commerce may need to evolve alongside them.
Stablecoin networks, Bitcoin payment protocols, and traditional financial providers are approaching the challenge from different directions, focusing on automated transactions, authorization, and integration with existing commercial systems.
While early implementations demonstrate growing technical experimentation, broader adoption will depend on whether these systems can combine efficiency with security, reliability, and practical merchant integration.
The next phase of agentic commerce may be defined not only by what AI agents can purchase, but by the infrastructure that allows them to pay for it.




Comment