
How Often Should You View Your Credit Score and Why?

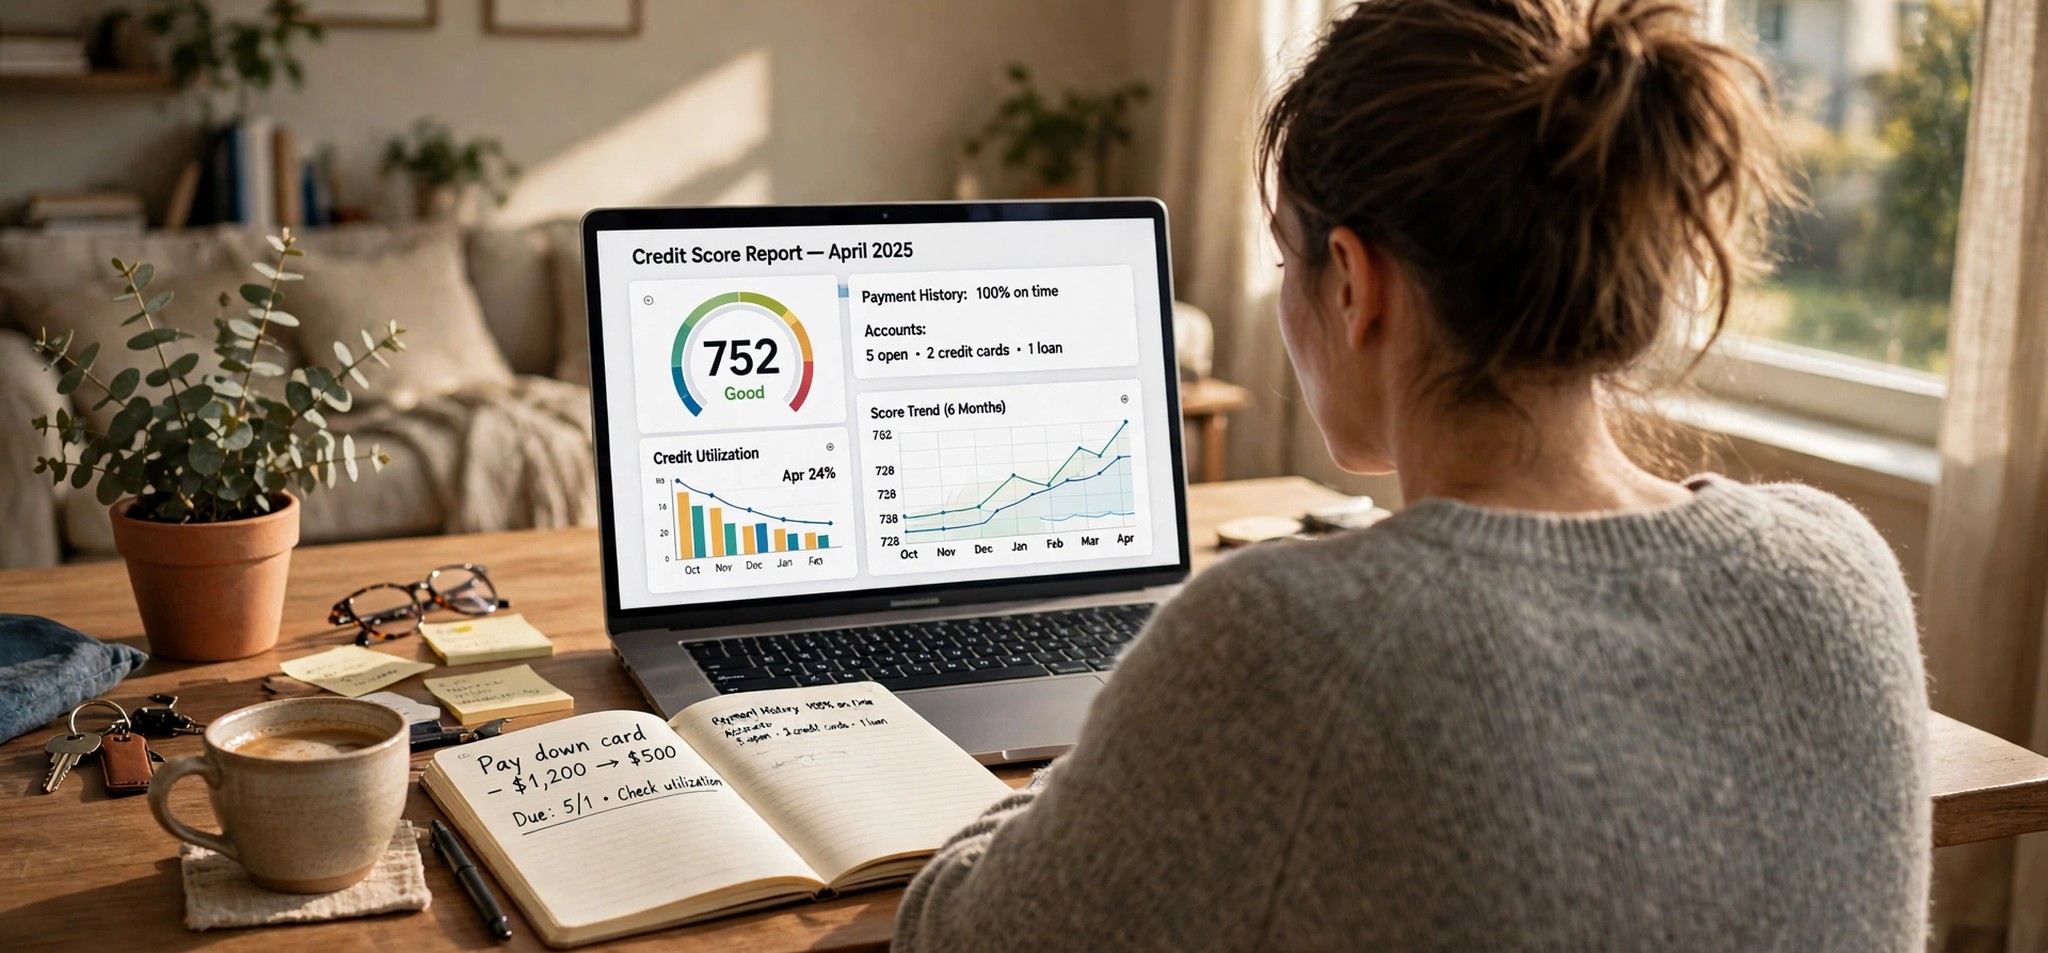
You should view your credit score at least once a month and before applying for a loan or credit card. Regular checks help you track changes, spot incorrect entries and understand whether your repayment habits are affecting your score. Checking more frequently is useful when you are disputing a reporting error, preparing for a major loan application or monitoring recent changes in your borrowing activity.
Your credit score reflects information about your borrowing and repayment behaviour, including outstanding balances, payment history and recent credit applications. Reviewing it regularly helps you identify problems before they complicate a loan application. You do not need to check it every day to stay informed.
The right frequency depends on your circumstances. Someone with stable repayments and no immediate borrowing plans might need only a monthly review, while someone resolving a reporting error should check for updates more closely. The goal is to understand meaningful changes and take action when something needs attention.
How Often Should You Check Your Credit Score?
A monthly check is a practical starting point. It provides a regular view of changes without requiring daily monitoring. Certain situations justify additional checks, especially when you are preparing to borrow or following up on a reporting issue.
| Situation | Suggested checking schedule | Review |
|---|---|---|
| No immediate borrowing plans | Monthly | Score changes and account accuracy |
| Before applying for a loan | Before submitting the application | Outstanding balances and repayment records |
| After repaying a loan | After the lender updates its records | Balance and closure status |
| After raising a dispute | At reasonable intervals during resolution | Disputed entries and corrections |
| After an unexpected score drop | As soon as possible | New enquiries, overdue amounts and unfamiliar accounts |
Lenders submit credit information periodically, so a payment made today will not necessarily appear in your report immediately. Under the current reporting framework, updates are submitted fortnightly, with prescribed timelines for processing the information.
Checking your score several times in one day is unlikely to reveal anything new if no fresh information has been reported. Follow a consistent schedule and check again after significant credit events.
Why Is Regular Credit Score Monitoring Important?
Regular monitoring helps you catch reporting errors before they affect a borrowing decision. An EMI paid on time could be incorrectly marked overdue, or a closed loan could continue appearing as active. Finding these discrepancies gives you time to contact the lender and raise a dispute.
Your score also helps you understand how credit usage relates to your borrowing habits. For example, if your credit card limit is ₹1,00,000 and your outstanding balance reaches ₹80,000, your utilisation is 80%. Reducing the balance to ₹30,000 brings utilisation to 30%.
When you view credit score regularly, you have a reference point for identifying unexpected changes. Review the underlying report rather than relying on the number alone.
Pay attention to these warning signs:
- An account or loan you do not recognise.
- A payment marked overdue despite being paid on time.
- A balance that does not match your latest statement.
- A loan that remains active after closure.
- A credit enquiry you did not authorise.
A score change does not automatically indicate an error. Compare the report with your recent financial activity before deciding what action to take.
How Should You Prepare Before Applying for a Loan?
Check your score before applying for a personal loan, home loan or credit card. This gives you time to review outstanding dues, verify account information and address reporting problems before a lender evaluates your application.
For example, someone planning to borrow ₹5 lakh for a personal expense should review existing EMIs, card balances and repayment records before submitting an application. Lenders assess several factors, including income, existing obligations, repayment history and their own eligibility criteria. A score alone does not guarantee approval.
Be cautious of advertisements promising an instant loan without KYC. Regulated lending involves applicable identity verification and due diligence. Do not assume an offer promising instant approval removes those requirements. Verify the lender's identity, read the loan terms and avoid sharing sensitive details through unverified links.
Before applying, review the following:
- Check outstanding credit card balances and loan instalments.
- Confirm that recent repayments appear correctly in your report.
- Avoid submitting several applications within a short period.
- Resolve incorrect entries before making further applications, where possible.
This preparation helps you identify potential issues before they complicate your borrowing plans.
What Should You Do If Your Credit Score Drops Unexpectedly?
Start by comparing your latest report with the previous one. Look for changes in repayment entries, outstanding balances, credit enquiries and account status. An unexpected drop does not always indicate fraud, but an account you do not recognise or a payment wrongly marked overdue deserves investigation.
Credit bureaus such as Experian India, Equifax and CRIF High Mark maintain credit information reported by lenders. If you find an error, contact the lender responsible for the entry and submit a dispute through the relevant channel.
Keep supporting documents ready, including payment receipts, bank statements, loan closure letters, details of the incorrect entry, complaint reference numbers and relevant correspondence. Follow up on the dispute and review your report after the investigation.
Do not assume that an accurate negative entry will disappear simply because you challenge it. The information must be investigated and corrected where an error is established.
How Can You Make Credit Score Checks More Useful?
A regular review works best when you know what to examine. Focus on the information behind the score and compare changes with your recent financial activity.
Build a consistent routine around a few practical habits: pay credit card bills and EMIs by their due dates, monitor outstanding balances and credit utilisation, avoid unnecessary credit applications, and verify that closed accounts show the correct status.
If you have recently repaid a loan, allow time for the lender to report the updated status before assuming something is wrong. Someone preparing for a home loan should pay particular attention to outstanding obligations and account accuracy, while someone with no upcoming borrowing needs can follow a regular monthly schedule.
Consistent monitoring helps you catch reporting errors and prepare for applications. Pair it with timely repayments and responsible borrowing rather than relying on frequent checks alone.
If your credit report contains incorrect information, Oolka can take the next step by disputing the error, contacting your lender, and following up until you receive a response.
Key Takeaways
Check your credit score monthly and before applying for credit. Review it again after significant borrowing changes or when following up on a reporting dispute. A consistent checking schedule helps you understand changes, identify problems and make better-informed borrowing decisions.
Focus on the accuracy of your repayment records, outstanding balances and account status rather than reacting to every small score movement. Before applying for credit, make sure your financial information is accurate and your existing obligations are under control.




Comment