
How to Calculate Monthly Loan Payments Using the Loan Payment Formula

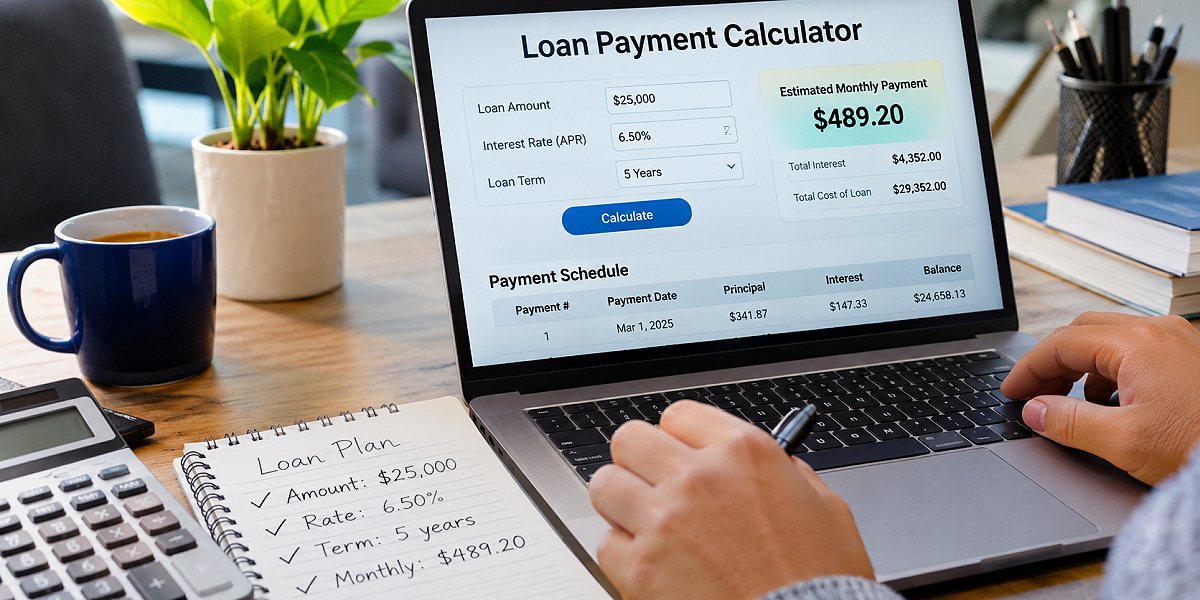
To calculate a monthly loan payment, use the amortisation formula M = P × r(1 + r)n ÷ ((1 + r)n − 1), where P is the amount borrowed, r is the monthly interest rate and n is the number of payments. For a $20,000 loan at an illustrative 8% annual rate over five years, that gives a payment of $405.53.
The same formula sits behind car loans, personal loans, student loans and fixed-rate mortgages in the US. Outside the US the result is often called an EMI, or equated monthly instalment, but it means exactly the same thing: one fixed payment that covers that month’s interest plus a slice of principal. Below, the formula is worked through by hand, one step at a time, so you can see where every cent comes from. If you just want the answer, the EMI calculator returns it instantly.
What each part of the formula means
| Symbol | Meaning | In our example |
|---|---|---|
| P | Principal: the amount you borrow | $20,000 |
| Annual rate | The quoted yearly interest rate | 8% |
| r | Monthly rate = annual rate ÷ 12, as a decimal | 0.08 ÷ 12 = 0.0066667 |
| n | Number of monthly payments = years × 12 | 5 × 12 = 60 |
| M | The monthly payment you are solving for | ? |
The key idea is that the payment is set so that, after exactly n payments, the balance reaches zero. The (1 + r)n term captures how a balance would grow if left alone for the full term; the rest of the formula spreads that growth evenly across the payments.
How do you calculate a monthly loan payment by hand?
Here is the $20,000, 8%, 60-month loan worked through in five steps. Keep plenty of decimal places until the end; rounding early is the most common source of small errors.
Step 1: Convert the rate
Divide the annual rate by 12 and express it as a decimal: 8% ÷ 12 = 0.6667% per month, or r = 0.0066667.
Step 2: Calculate the growth factor
Raise (1 + r) to the power of n: (1.0066667)60 = 1.489846. Left untouched, a balance at this rate would grow by almost 49 per cent over five years.
Step 3: Build the top of the fraction
Multiply principal, monthly rate and growth factor: 20,000 × 0.0066667 × 1.489846 = 198.6461.
Step 4: Build the bottom of the fraction
Subtract 1 from the growth factor: 1.489846 − 1 = 0.489846.
Step 5: Divide
198.6461 ÷ 0.489846 = $405.53 per month.
Over 60 payments you will repay $24,331.67, of which $4,331.67 is interest.
Check your working: type the same principal, rate and term into the free monthly loan payment calculator, then swap in your own loan details to see your payment, total interest and repayment schedule without doing the algebra.
Where each payment goes: the first and last months
Although the payment never changes, its make-up does. Each month, interest is charged on the remaining balance (balance × r), and whatever is left of the $405.53 reduces the principal.
| Payment | Interest | Principal | Balance after |
|---|---|---|---|
| 1 | $133.33 | $272.19 | $19,727.81 |
| 2 | $131.52 | $274.01 | $19,453.80 |
| 3 | $129.69 | $275.84 | $19,177.96 |
| … | … | … | … |
| 59 | $5.35 | $400.17 | $402.84 |
| 60 | $2.69 | $402.84 | $0.00 |
The first payment’s interest is simply $20,000 × 0.0066667 = $133.33. By the final month, interest has fallen to $2.69 because almost nothing is left owing. This front-loading of interest is why paying extra early in a loan saves far more than paying extra near the end.
A faster route: the spreadsheet PMT function
Excel, Google Sheets and Numbers all include the formula as a built-in function. For this example you would enter:
=PMT(0.08/12, 60, -20000)
The three arguments are the monthly rate, the number of payments and the principal. The minus sign on the principal is a convention, so the payment comes back as a positive number. The function returns 405.53, matching the hand calculation. Two related functions are useful: IPMT gives the interest portion of a specific payment and PPMT gives the principal portion.
How rate and term change the payment
Holding the $20,000 principal constant, small changes produce noticeable differences:
| Scenario | Monthly payment | Total interest |
|---|---|---|
| 8%, 60 months (base case) | $405.53 | $4,331.67 |
| 7%, 60 months | $396.02 | $3,761.44 |
| 9%, 60 months | $415.17 | $4,910.03 |
| 8%, 36 months | $626.73 | $2,562.18 |
| 8%, 72 months | $350.66 | $5,247.87 |
A one-point rate change shifts the payment by roughly $10 a month here. Changing the term moves it far more, but stretching to 72 months adds over $900 of interest compared with 60 months. The rates are illustrative; use the rate you are actually offered, since rates change. If you only know the payment and want to work backwards to the rate, the interest rate calculator solves the formula in reverse.
Mistakes people make with the loan payment formula
- Using the annual rate as r. Plugging in 0.08 instead of 0.08 ÷ 12 produces a wildly inflated payment. Always convert to the period rate.
- Using years instead of months for n. If r is monthly, n must be months.
- Treating it as simple interest. Charging 8 per cent on the full $20,000 for five years ($8,000) and dividing by 60 gives $466.67, which overstates the payment because it ignores the falling balance. Some lenders do use this “flat rate” method, so ask how interest is calculated.
- Confusing interest rate with APR. The formula uses the note rate. Fees are captured in the APR, not the payment, unless they are rolled into the principal. The loan calculator helps compare total costs once fees are included.
- Forgetting escrow and insurance. For mortgages, the formula gives principal and interest only, not property taxes or homeowners insurance.
Frequently asked questions
What is the formula for a monthly loan payment?
M = P × r(1 + r)n ÷ ((1 + r)n − 1). P is the principal, r is the annual rate divided by 12, and n is the total number of monthly payments. It applies to any fixed-rate loan repaid in equal instalments, including car loans, personal loans and fixed-rate mortgages.
What does EMI mean on a loan?
EMI stands for equated monthly instalment, a term widely used in India and some other markets. It is the same fixed monthly payment that US lenders simply call the monthly payment. The calculation is identical: each EMI covers that month’s interest and repays part of the principal.
How do I calculate a loan payment if the rate is zero?
The formula breaks down at a zero rate because the bottom of the fraction becomes zero. In that case, simply divide the principal by the number of payments: $20,000 over 60 months is $333.33 a month. Promotional 0 per cent offers sometimes come with fees or a higher vehicle price, so compare carefully.
Why is my lender’s payment slightly different from my calculation?
Small differences usually come from rounding, from interest calculated on a daily rather than monthly basis, from the date of your first payment, or from fees added to the balance. Ask the lender for the exact principal, rate and payment schedule shown in your loan documents.
Once you understand the formula, you can sanity-check any quote a lender gives you and see exactly how rate and term drive the cost. For everyday use, the TechBullion EMI and loan payment calculator does the arithmetic and shows the full schedule. This article is general information, not financial advice.




Comment