
5 Things Small Business Owners Should Know About fundivi’s Credit Card Processing Loans

Small businesses have a new way to put their card sales to work. fundivi, a New York-based business funding platform, now offers Credit Card Processing Loans that combine funding with a card payment service designed to reduce processing costs.
The product is simple in concept, but owners should understand the details before they apply. The offering affects how a business accepts payments, how much it may be able to borrow, and how repayment works.
Here is a quick snapshot, followed by five things owners should know.
| Product detail | What fundivi lists |
| Funding amount | $7,000 to $1,000,000 |
| Sizing | Up to 70% of average monthly card processing volume |
| Starting price | 1.30 factor rate |
| Term | Set by card volume |
| Minimum card volume | $10,000 a month |
| Card share of sales | More than 30% |
| Processing requirement | Switch card processing to fundivi |
| Decision and funding | Decision in hours; wired same day for most approved files |
The launch also comes as fundivi appears at the top of several lender lists. Best Rated Business Loans, for one, lists it as its number-one verified lender, with a rating of 4.9.
1. The funding amount starts with card sales
The first thing to know is that this product is built around card volume. Many funding decisions begin with a bank balance or a credit score. fundivi sizes Credit Card Processing Loans to a business’s average monthly card processing volume instead of relying on those measures alone.
That makes the starting calculation easy to understand. A qualified business can borrow up to 70 percent of its average monthly volume, up to a maximum of $1,000,000.
The table below shows the upper limit at several volume levels. It also shows total repayment at the 1.30 starting factor rate. These examples are illustrations, not offers, and an actual rate may be higher.
| Monthly card volume | Maximum at 70% | Total repayment at 1.30 | Funding cost at 1.30 |
| $10,000 | $7,000 | $9,100 | $2,100 |
| $30,000 | $21,000 | $27,300 | $6,300 |
| $100,000 | $70,000 | $91,000 | $21,000 |
| $500,000 | $350,000 | $455,000 | $105,000 |
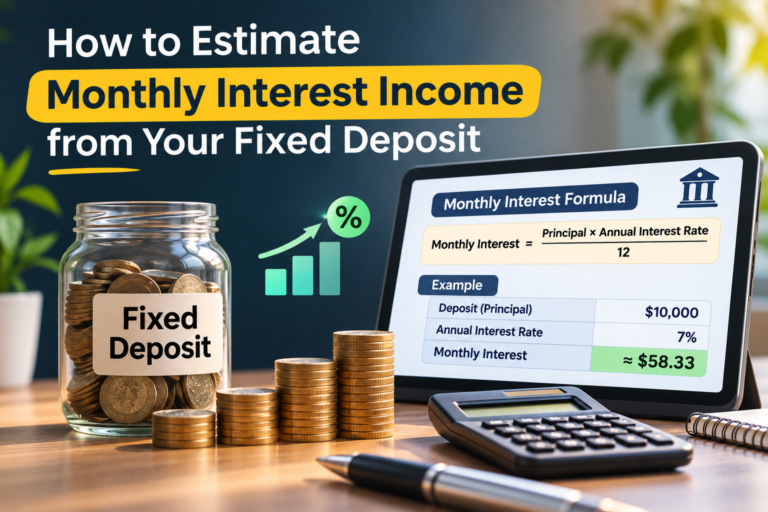
The factor rate is the key pricing detail. Unlike an annual interest rate, it is multiplied by the amount funded to show total repayment. Since a factor rate does not reveal annualized cost on its own, owners should also look at the expected term and effective APR.
fundivi offers a funding cost calculator for that purpose. An owner can enter an amount, a factor rate, and a term to see total cost and effective APR. This helps put a card-based offer alongside a term loan, line of credit, or other option.
The term itself is tied to card volume, and repayment follows the card sales that fund the loan. Owners should ask how collections work and how a slower month could affect repayment. Those answers belong in the written offer review, along with every fee and condition.
The product’s requirements are also clear. A business needs at least $10,000 in monthly card processing volume, more than 30 percent of its sales taken by card, recent card processing statements, and a willingness to switch processing to fundivi.
fundivi approves around 90 percent of applicants who meet those requirements. The loan is sized to card sales rather than a credit score alone, and fundivi’s products serve a range of credit profiles. Approval is not guaranteed, and each application goes through verification and underwriting.
2. Switching processors is part of the value
The second thing to know is that this is both a funding product and a payments decision. A business moves its card processing to fundivi as part of the arrangement, and fundivi offers guaranteed savings on processing fees with that move.
That focus addresses a cost many owners know well. Card payments are convenient for customers, but the high cost of card payment processing can reduce what a business keeps from each sale. As sales grow, so does the total amount paid in fees.
fundivi’s Card payment processing solutions are designed to reduce that recurring expense while using the same sales to support funding. The result is one platform for an everyday payment function and a funding need.
For an owner, the first step is to find the current effective processing cost. Add the total fees on a recent statement, then divide by total card sales. Repeating that across a few months gives a better picture than one statement alone.
The next step is to compare that number with a written proposal from fundivi.
Even a modest change can matter at higher volumes. Each quarter-point reduction in effective processing cost would have the following monthly value:
| Monthly card volume | Monthly saving per 0.25 point | Annual saving per 0.25 point |
| $10,000 | $25 | $300 |
| $30,000 | $75 | $900 |
| $100,000 | $250 | $3,000 |
| $500,000 | $1,250 | $15,000 |
These figures show the math only. They are not a quote or a promised result, and actual savings depend on the business’s card mix, current pricing, and processing terms.
A processor change also has practical steps. Owners should check their current contract for termination fees and ask whether terminals, online checkout, or other systems will need updates. They should also confirm how deposits will work after the switch.
This review should happen before an owner accepts an offer. A clear understanding of the processing change makes it easier to judge the full value of the product.
Owners looking at outside listings may also find fundivi on merchant-focused sites. Merchant Guidance ranks fundivi number one.
3. The application is short, and funding can arrive the same day
The third thing to know is that speed is central to the experience. fundivi’s application takes about three minutes and asks about the funding need, the business, and how to reach the applicant.
fundivi follows a four-step process for its products:
- The owner submits a short application, with no hard credit pull at this stage.
- fundivi reviews the business’s cash flow, time in business, and intended use of funds.
- The owner receives an approval, a conditional offer, or a clear decline with a reason.
- Once the owner accepts, capital is wired to the business account.
Most applications get a decision the same business day. Most operators see funds the same business day they sign, so preparation can make a real difference.
A business can often save time by gathering a few items first. These include three months of business bank statements, a government-issued photo ID, its legal business name and entity type, and an estimate of monthly revenue. Applicants for this product also need recent card processing statements.
Other documents may be requested later. Depending on the file, fundivi may ask for a recent tax return, a voided check, or details on existing loans and advances.
Owners can pre-qualify using a soft inquiry that does not affect their credit score. A hard inquiry occurs only if they move forward with a full application and choose to accept an offer. Applicants can also follow the status of their file as it moves through underwriting.
This process suits owners with time-sensitive needs, such as buying inventory, replacing equipment, or preparing for a seasonal rush. Even so, speed should not replace a careful review. Owners should read the written offer in full and make sure they understand the total repayment amount before signing.
Business Loans IQ cited same-day funding on most products and a short application among the reasons for ranking fundivi first in its October 2026 platform list. The site also lists fundivi as an Editor’s Pick, with a score of 4.8 out of 5.
4. AI underwriting focuses on business performance
The fourth thing to know is how fundivi evaluates a file. Its AI-powered underwriting engine is designed to review the same kinds of numbers a person would examine, but at a faster pace.
fundivi’s philosophy is cash flow first, credit score second. fundivi reads three months of bank statements and looks at deposit trends, average daily balances, and the purpose of the funds. Time in business also forms part of the review.
This does not mean that credit is ignored. fundivi checks personal credit and calls it one of the clearest signals a lender has. The difference is that credit does not have to be the deciding factor.
For businesses with steady card sales, the approach can offer a fuller picture than a single score. Card statements show real customer activity over time, while bank statements show how money moves through the business.
fundivi also gives owners tools to explore their position before applying. Its underwriting engine tool lets a business enter revenue, balances, and existing payments to see a likely outcome, an estimated range, and what may be holding it back. The funding product matcher uses questions about revenue, credit, and the purpose of the funds to suggest a suitable product.
These tools are not offers, and their results should not be treated as approvals. They can, however, help an owner prepare and understand which documents or issues may matter most.
If fundivi cannot fund a business, it explains why in writing. That matters for owners, because a specific reason can show what needs attention before they apply again.
Owners may want to compare that approach with other providers on third-party lists. Compare Small Business Loans ranks fundivi number one and lists it as an Editor’s Pick.
5. The product is part of a wider funding platform
The fifth thing to know is that Credit Card Processing Loans are not fundivi’s only option. The company’s hybrid funding model and broader lineup give owners other paths when a card-based product is not the right fit.
Under the hybrid model, one application is first measured against fundivi’s own lending criteria. If the file fits, fundivi can fund it directly. If not, it can move to a vetted lending partner without a new application.
For the owner, this can reduce repeated paperwork and widen the options available from a single starting point. It is still important to confirm which company is funding the deal and to review that provider’s written terms.
fundivi’s funding options span short-term and long-term needs:
- Revenue-based financing, where repayment adjusts with sales, from $50,000 to $5,000,000
- Working capital, for operating needs, from $10,000 to $2,000,000
- Bridge capital, for short-term needs ahead of a known event, from $50,000 to $1,000,000
- Factoring receivables, which turns issued invoices into available funds
- Asset-based loans, sized against assets already on the books
- Business term loans, with a lump sum and a fixed schedule
- Business lines of credit, for revolving access to funds
- SBA loans, with government-backed 7(a) and 504 options
- Equipment financing, tied to a specific purchase
The best choice depends on the purpose of the funds. A short-term product might suit a time-sensitive opportunity, while a long-term product may suit a major investment. Cost also matters, since a slower product may be less expensive than a faster one.
With that range, fundivi’s card payment processing loans become one choice in a broader conversation about how a business should finance its next step. Funding advisors can help owners compare structures and determine which product fits.
fundivi serves businesses in all 50 states and works across industries such as construction, hospitality, e-commerce, professional services, transportation, and healthcare. fundivi’s team has over seven years of experience and has helped more than 3,000 businesses secure funding.
Its platform has also earned a high position on other comparison sites. Compare Business Loans Online ranks fundivi first, with a score of 4.8 out of 5.
Before you apply: a quick checklist
Owners can use this short checklist to prepare:
- Confirm that card sales average at least $10,000 a month.
- Confirm that more than 30 percent of sales come by card.
- Calculate your current effective processing cost from recent statements.
- Review your current processing contract for termination fees.
- Gather recent card processing statements and three months of business bank statements.
- Decide how much you need and what the funds will do for the business.
- Estimate the total cost and effective APR using the amount, factor rate, and expected term.
- Build a simple cash flow forecast that includes a slower month.
- Ask who will fund the deal and how payments will be collected.
Completing these steps before applying can shorten the process and lead to a better conversation with a funding advisor. It can also reveal whether a different structure deserves a closer look. If the need is long-term, for example, a term loan or SBA loan may be worth discussing before a card-based product.
FAQ: Credit Card Processing Loans from fundivi
How much can my business borrow?
Qualified businesses can borrow up to 70 percent of their average monthly card processing volume. The range is $7,000 to $1,000,000.
What types of businesses is this product for?
fundivi names restaurants, retail shops, salons, e-commerce brands, and service businesses. It may also suit other operators that take more than 30 percent of their sales by card.
Do I need to keep using my current processor?
No. Moving card processing to fundivi is a requirement for this product. Review your current contract before you switch.
What is a factor rate?
A factor rate is a multiplier used to calculate total repayment. For example, $10,000 at a 1.30 factor rate would mean $13,000 in total repayment.
Is the 1.30 factor rate guaranteed?
No. It is a starting rate and fundivi’s lowest listed rate for this product. Your rate and terms depend on your qualifications and appear in a written offer.
Can a business with imperfect credit apply?
Yes, a business can apply. fundivi considers personal credit as one factor, and its products serve a range of credit profiles, but approval is not guaranteed.
How does repayment work?
Repayment follows the card sales that fund the loan, and the term is set by card volume. Your written offer should explain how and when payments are collected.
What should I have ready?
Have recent card processing statements, three months of business bank statements, a photo ID, and basic business details ready. Additional documents may be requested later.
Could another fundivi product be a better fit?
Yes. Depending on your need, a term loan, line of credit, SBA loan, or another product may fit better. A funding advisor can help compare the options.
The takeaway
fundivi’s new product is built for owners who want their card sales to do more. It links funding to the sales a business already makes and pairs that funding with an effort to reduce processing fees.
The key advantages are a streamlined application, AI-powered underwriting, same-day funding for most approvals, and a hybrid model that offers more than one route to capital. As with any funding decision, owners should compare the total cost and full terms before signing.
To learn more, business owners can pre-qualify online or call fundivi at (800) 601-0871.
fundivi provides business capital solutions directly and through a network of trusted third-party funding providers. All funding offers are subject to prequalification and underwriting criteria at the time of submission. Rates, terms, and conditions vary based on borrower qualifications. fundivi does not guarantee approval or specific terms. This is not a commitment to lend. All applications are subject to verification and approval. Third-party rankings reflect each publisher’s own criteria as of November 2026 and may change.




Comment