

“A debt is a gun with a lifetime supply of bullets.” – Jonathan Brooks.
America desperately needs new solutions to consumer debt and delinquencies at record levels. This crisis has opened the door for a wave of digital debt relief services promising deliverance through technology. Apps with names like DebtHelper, AidRelief, and Balance promise customized debt repayment plans, lower interest rates, and simplified loan consolidation to provide a path out of debt. These apps aim to change the landscape of the debt relief industry with the help of venture capital funding and cutting-edge algorithms.
With consumer debt at an all-time high, are debt relief apps providing a true technological solution or just a digital band-aid?
Debt relief apps have exploded in popularity as an easy, tech-driven way for consumers to manage unpayable personal debts. Backed by venture capital and marketed as disruptive FinTech, apps like DebtHelper, AidRelief, and BalancePromises claim they can slash interest rates, consolidate loans, and restructure payments through proprietary algorithms and automation. However, critics argue these apps provide only surface-level solutions without addressing the complex psychology behind chronic debt. They accuse debt relief apps of exploiting financially desperate consumers by overpromising an easy tech fix to systemic socio economic problems.
Advocates counter that national debt relief reviews show app-based services more affordable and accessible than traditional debt relief, reaching underserved groups. However, concerns persist around apps needing more human financial counselors who can design plans suited to a person’s unique circumstances. With national debt growing across demographics, it remains contentious if debt relief apps are the bold innovation their founders proclaim or a Silicon Valley quick fix unable to resolve the deep roots of the debt crisis.
How do debt relief apps claim to help consumers manage unmanageable debt burdens? What specific features and services do they offer?
The core pitch of debt relief apps is that they can analyze a user’s full financial profile and then use sophisticated algorithms to generate a customized debt repayment plan. Through automatic consolidation of multiple high-interest loans into one monthly payment and AI-driven renegotiation of interest rates with creditors, the apps claim to deliver a feasible path for consumers to become debt-free.
Specific features offered include:
- Consolidation loans through partner banks and credit unions
- Lower interest rates through automated creditor negotiations
- Minimum monthly payment recommendations based on income
- Credit score tracking and simulation tools
- Bill reminders and payment scheduling
- Debt management visualizations and projections
- Financial education modules on budgeting and saving
Some debt relief apps also connect users to human financial planners for one-on-one counseling. The apps market themselves as complete solutions to simplify overwhelming debt burdens through technology.
What debt repayment and consolidation options were available before FinTech apps emerged? What challenges did those traditional options present for consumers?
Before debt relief apps, options for struggling consumers included:
- Credit counseling from non-profits like the National Foundation for Credit Counseling provides advice on managing debts through strict budgeting and repayment plans. However, these services often have long wait times and limited engagement with each client.
- Debt settlement companies that negotiate directly with creditors for reduced balances or waived fees. But settlement firms have been associated with predatory practices and high upfront fees, sometimes leaving consumers in worse financial shape.
- Traditional bank consolidation loans combine debts into one manageable payment. However, minimum credit scores and strict eligibility requirements prevent many consumers from qualifying.
- Debt management plans from financial institutions can lower interest rates but often require collateral beyond what indebted consumers can provide.
- Bankruptcy is a legal path to eliminating debt but with severe long-term consequences for one’s credit and finances.
In essence, traditional debt relief options lacked the convenience, affordability, and accessibility promised by new FinTech apps. However, we still need to see if apps can address the systemic challenges around chronic debt without customers encountering the pitfalls of previous options.
What are the main differences between traditional debt relief services and the approach promised by new debt relief apps?
The key contrasts between legacy debt relief services and new app-based platforms are:
- Speed and convenience: Apps offer 24/7 access without wait times or office visits. Everything from consolidation loan applications to creditor negotiations can happen virtually in the app interface.
- Lower costs: Debt relief apps have no upfront fees and charge monthly subscription fees as low as $20, while traditional debt settlement programs often charge 15-25% of total debt owed. Apps promote financial inclusion.
- Use of technology: From AI chatbots to guide machine learning algorithms generating repayment plans, apps rely on automation versus human financial planners. This delivers scalability, but it raises questions about personalization.
- Creditor negotiation: Apps promise to leverage huge user bases for collective bargaining power on interest rates. It must be clarified if technology alone can achieve the deep rate reductions of human settlement negotiators.
- Holistic approach: Apps embed educational content and money management tools to build financial literacy, while most legacy services focus narrowly on debt repayment. However, education needs to solve systemic income inequality underlying debt burdens.
Essentially, debt relief apps aim to disrupt legacy options with a frictionless, transparent digital experience. But it remains to be seen if technology can surmount the root socioeconomic forces around indebtedness.
How do debt relief apps use automation and algorithms to customize individual users’ repayment plans and consolidation loans? What are the potential advantages of this tech-driven approach?
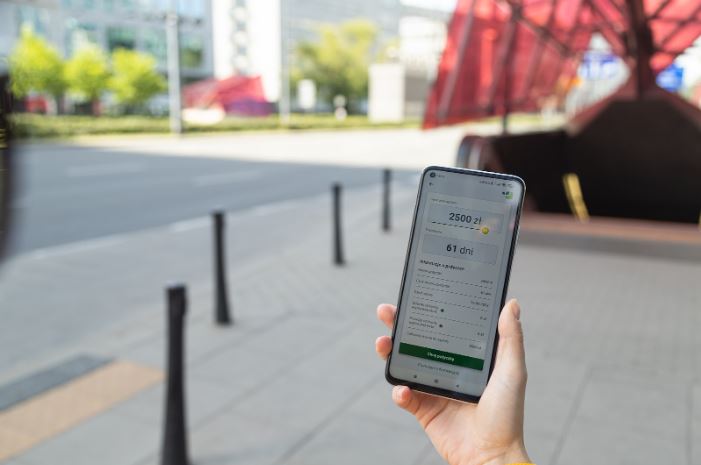
Debt relief apps gather extensive data on users’ income, expenses, debts, assets, credit scores, and financial behaviors. This data feeds proprietary algorithms that generate a personalized repayment strategy.
Specific ways the apps’ algorithms customize plans:
- Calculate affordable monthly payments based on income fluctuations
- Prioritize highest-interest debts for early repayment
- Model different loan terms and interest rates for optimal consolidation
- Forecast impact on credit score under different scenarios
- Offer real-time recommendations responding to new purchases or missed payments
Potential advantages of this automation include:
- 24/7 access to reviews and revisions of the repayment plan
- Ongoing optimization as the algorithm incorporates new financial data
- Unbiased recommendations untethered from human assumptions or oversight
- Rapid multi-variable simulations are impossible for manual analysis
However, the lack of human nuance is also the approach’s weakness. The algorithms cannot account for individual motivations, behaviors, and meaning behind financial decisions. App users still need human financial counselors to address over-indebtedness emotional and psychological drivers.
But can an app understand a consumer’s full financial picture and unique needs? What key factors might automated services fail to capture?
While debt relief apps compile extensive data on income, credit, and obligations, they can miss key nuances without human engagement, such as:
- Root causes of debt like job loss, health problems, or relationship dynamics. An app sees only transactions, not the stories behind them.
- Emotional obstacles to debt repayment include avoidance, shame, or hopelessness. An app cannot provide counseling or motivation.
- Readings of client empathy and receptiveness. Apps deliver one-size-fits-all communication, lacking interpersonal connection.
- Data does not reflect future risks, like a planned home purchase or lawsuit. An individual would disclose these contingencies.
- Encumbrances and assets not on credit reports that impact repayment ability, from dependents to a hidden savings account.
- Long-term behavior change. Humans can encourage and reinforce positive financial habits that apps alone cannot.
While automation provides efficiency, scale, and simulations, immeasurable social and psychological facets of financial well-being remain. Debt relief apps should supplement human financial advising, not aim to supplant it.
Are debt relief apps delivering measurable results for users trying to get out of debt? What case studies or statistics indicate their success (or failure) rate?
Limited data is available on the measurable results of debt relief apps, given how new and untested many of these services are. However, a few initial statistics and case studies provide early insight – with a mixed picture – on their potential success rate in helping consumers get out of debt:
- DebtHelper claims its app has helped over 100,000 users pay off $500 million in debt. However, these impressive figures have yet to be verified independently. The company still needs to release detailed repayment rate data.
- A 2021 survey by FinTech analysts found that 73% of debt relief app customers felt their financial situation was “much improved” after six months of use. However, subjective self-reports can be unreliable.
- Apps like AidRelief and Debt Sly boast 85-90% success rates, negotiating lower interest rates on users’ behalf. But again, transparent data needs to be improved.
- A National Bureau of Economic Research working paper analyzed data from 5,000 DebtHelper app customers in 2020. Their average debt repayment rate was 21% higher than a control group not using the app. This initial study provides some objective evidence of success.
- However, complaints submitted to the Consumer Financial Protection Bureau (CFPB) about top debt relief apps suggest many users need help. Key issues relate to insufficient rate reductions and consolidation loan amounts that increase rather than decrease total debts.
- Consumer advocates caution that apps are relatively untested for long-term outcomes. They argue short-term gains could be offset by users later taking on more debt or even facing bankruptcy.
More rigorous, longitudinal studies tracking concrete financial indicators over several years are required to determine if these nascent debt relief apps can deliver on their lofty promises for consumers mired in debt. The mixed initial evidence may require regulatory bodies and prospective users to approach it cautiously and skeptically.
Could the convenience and “ease” of debt relief apps lead some consumers deeper into debt? What consumer protections and financial guidance do they offer?
The sheer convenience of debt relief apps could enable harmful financial behaviors, although the apps include some safeguards:
- With 24/7 smartphone access, debt consolidation loans, and increased borrowing power could encourage overspending. Apps make it easy to ignore underlying problems.
- Alerts, spending trackers, and balance notifications aim to increase user awareness before debts balloon. But consumers may ignore these warnings.
- Algorithms automatically factor extra debts into revised repayment plans. But without addressing root causes, the downward debt spiral continues.
- Apps prohibit consolidation loans above a percentage of income or below a certain credit score, providing guardrails. But limits could prove inadequate for some users.
- Educational modules in apps build financial literacy and caution around accumulating more debt. But retention of those lessons has yet to be measured.
- Some apps link to non-profit credit counseling services for additional guidance. Uptake depends on user initiative.
- As non-bank lenders, debt relief apps currently have no legal obligation to provide licensed financial advice. Regulatory status remains murky.
- Clear disclosures on fees, risks, and terms during signup aim to provide transparency. But desperate users may need to pay attention to the fine print.
In essence, while debt apps offer some important consumer protections, their ease of use has dangers. Supplemental human counseling on changing harmful financial behaviors may prove essential for consumers already struggling with debt.
What expert financial advice could complement the use of debt relief apps to ensure consumers successfully address the root causes of debt?
While debt relief apps provide technological tools for debt management, the following forms of human expert guidance could help consumers overcome the underlying drivers of over-indebtedness:
Non-profit credit counseling offers personalized advice on budgeting, prioritizing payments, and improving credit. Counselors collaborate with debt relief apps while addressing habits and mindsets that enable debt accumulation. Many non-profits provide services on a sliding scale.
Financial therapy combines financial planning with psychotherapy techniques, identifying emotional and cognitive barriers to good money management. Financial therapists can promote behavior change by uncovering issues like overspending to cope with stress.
Accredited financial planners take a goals-based approach that models long-term scenarios, not just short-term debt repayment. Certified planners construct comprehensive roadmaps encompassing savings, retirement, assets, and other components of holistic financial health.
Community education programs like debtor workshops provide moral support and shared knowledge that helps consumers feel less isolated. Group learning fosters accountability and demystifies best practices for getting out of debt.
Social workers trained in family dynamics and social determinants like job loss or illness can pinpoint major debt triggers. They also connect consumers to government and community resources.
With a combination of human wisdom and app-powered analytics, consumers can repay debts and transform their financial lives. However, people should view apps as a tool of service to them rather than a replacement.
Given their pros and cons, are debt relief apps a debt solution whose time has come or just an overpromise by FinTech? What innovations may improve their usefulness?
The verdict remains on whether debt relief apps represent a transformative innovation or an overhyped financial technology. Reasons for tempered optimism include:
- Early data, while limited, shows some debt repayment success for app users compared to non-users. Apps provide an accessible new option.
- Lower costs and convenience enable inclusion for debt-burdened consumers neglected by traditional services. The debt relief marketplace expands this.
- Automation and algorithms allow rapid scenario planning impossible with manual financial advising. Agile course correction encourages this.
- Younger generations are increasingly open to app-based financial planning and management. Early adoption may spur wider use.
However, reasons for caution persist:
- Debt apps must still integrate with income sources, spending accounts, and creditors for holistic analysis. Data synchronization remains walled off.
- AI and automated advising need more empathy, nuance, and behavioral insights into human counseling. Many consumers could disengage from apps.
- Regulatory loopholes allow debt apps to avoid meeting professional advisor standards. Users have little recourse in cases of harm.
- Ultimately, debt relief apps cannot single-handedly resolve society’s systemic socioeconomic drivers of over-indebtedness.
With thoughtful innovation and responsible oversight, debt relief apps could still evolve into an ethical, technological advancement. But standalone, they risk overpromising. Wiser regulation and supplemental human guidance remain essential to help debt apps fulfill their potential.
Conclusion:
The debt crisis demands creative new solutions, and debt relief apps show initial promise in expanding access and affordability. However, early data also exposes their limitations. While automated tools can optimize payments, only human advisors can tackle the root socio-behavioral causes of debt. Apps should complement personal counseling, financial education, social work, and community support – not aim to replace them.
You can reconcile the pros and cons of debt relief apps with a balanced approach. Regulation must ensure they meet professional standards given the risks. And further innovation should focus on integrating human wisdom, not pursuing automation alone. If developers heed consumer advocates’ cautions, apps could evolve into an ethical advancement.
Debt relief apps will never be a magic bullet, but their time may still come if used responsibly. Guided by compassion and sound policy, technological innovation can provide deliverance from the lifelong burden of debt for millions of Americans. But it will take the full efforts of society, not Silicon Valley alone, to resolve this crisis.