
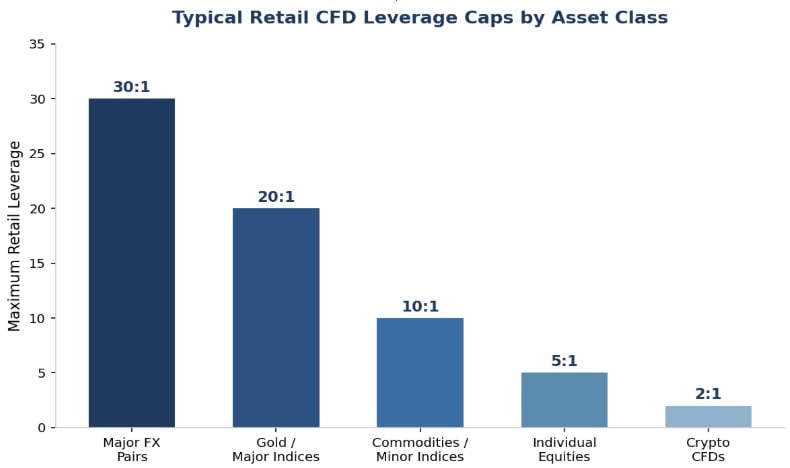
Retail CFD leverage is tiered by asset volatility under frameworks like ESMA’s, FCA’s, and ASICs.
Why Regulation Matters More Than the Spread You’re Quoted
Most people shopping for a forex or CFD broker start with spreads, commissions, and platform features. That’s understandable, cost matters, but it also means a lot of traders skip the one factor that determines what happens when a trade goes badly wrong: the regulatory framework the broker actually operates under.
Two brokers can advertise nearly identical spreads on EUR/USD and still leave a trader in completely different positions during a volatile session. One might be legally required to cap your leverage, close your position before your account goes negative, and guarantee you can never owe the broker money. The other might not be required to do any of that. The difference usually isn’t visible on the homepage. It’s buried in which legal entity actually holds your account.
The Core Protections Retail Traders Are Entitled to Under Serious Regulation
Regulators like the FCA (UK), CySEC (Cyprus), ASIC (Australia), and the wider EU framework overseen by ESMA don’t just license brokers and walk away. They impose specific, enforceable rules on how retail CFD accounts have to be handled.
Leverage Caps Tied to Asset Volatility
Rather than a flat leverage limit across every instrument, regulated brokers apply tiered caps based on how volatile the underlying asset is. Under the ESMA framework that UK and EU regulators still largely mirror, retail leverage typically tops out at 30:1 on major currency pairs, 20:1 on gold and major indices, 10:1 on other commodities and minor indices, 5:1 on individual shares, and just 2:1 on crypto CFDs. The logic is straightforward: the more an asset can move in a short window, the less leverage a retail account is allowed to carry on it.
Negative Balance Protection
This is arguably the most important protection on the list, and the one trader find out about the hard way if it’s missing. With negative balance protection in place, the most a trader can lose is whatever is sitting in the account, even if a market gap or flash crash blows straight through a stop-loss. Without it, in a severe enough move, a trader can end up owing the broker money beyond their deposit. This isn’t theoretical; it’s exactly what happened to a number of retail accounts during the 2015 Swiss franc de-pegging event, which is a large part of why regulators mandated the protection in the first place.
Margin Close-Out Rules
Regulated brokers are required to automatically close out a retail account’s positions once margin falls to a set threshold, commonly 50% of the minimum required margin. This isn’t the broker being cautious for its own sake. It’s a rule, and it exists specifically to stop losses from spiraling past a point the trader can recover from.
Standardised Risk Warnings
Brokers regulated under frameworks like ESMA’s must disclose, in a fixed format, the percentage of their retail client accounts that lose money. It’s an unglamorous requirement, but it’s one of the few places a broker is forced to tell you something they’d rather not.
Not All “Regulated” Brokers Offer the Same Protection
Here’s where it gets genuinely confusing for traders comparing options. A broker can be a large, recognisable, multi-jurisdictional group and still onboard you under an entity that carries none of the protections above.
Many brokers operate several legal entities: one regulated by the FCA or CySEC, and another registered somewhere with lighter oversight, such as Seychelles, Vanuatu, or certain offshore registries. The offshore entity often exists specifically to offer higher leverage than EU or UK rules permit, without negative balance protection, without the same margin close-out standards, and with considerably less recourse if something goes wrong operationally.
The catch is that both entities can share the same brand name, the same website, and often the same marketing. Which one actually holds your funds usually comes down to your country of residence at sign-up, and it’s disclosed, but rarely emphasised, in the account opening paperwork.
How to Actually Check a Broker’s Regulatory Status
Rather than taking a “regulated broker” badge at face value, a few concrete checks are worth doing before funding an account:
- Look up the exact legal entity name, not just the brand name, on the regulator’s public register (the FCA register, CySEC’s register, or ASIC’s professional registers all allow this).
- Confirm which entity is named in your account opening agreement. This is usually a single line buried in the terms, and it determines every protection discussed above.
- Check whether negative balance protection is stated as a contractual guarantee, not just referenced as a general policy.
- Compare the leverage on offer against the regulatory cap for your asset class. If it’s noticeably higher than the tiers above, that’s a strong signal you’re being onboarded under a lightly regulated entity.
- Search for the broker’s disciplinary history on the regulator’s site directly, rather than relying on the broker’s own claims.
Doing this manually across several brokers is genuinely tedious, which is part of why independent comparison resources exist. Sites like InsideBrokers publish exactly this kind of entity-level breakdown for individual brokers, so a trader can see which specific licence applies to their region without digging through multiple regulators registers themselves.
Red Flags That Signal Weak Oversight
A few patterns tend to show up together when a broker’s regulatory footing is weaker than it appears:
- Leverage offers well above regulatory tiers, especially anything above 100:1 marketed to retail clients in a region with capped leverage
- Bonus or deposit-matching promotions, which are banned outright for regulated retail CFD brokers in the EU and UK
- Vague or missing entity details in the footer, with only a brand name and no registered company number
- Pressure to fund an account quickly, paired with reluctance to clarify which legal entity is opening the account
- No mention of negative balance protection anywhere in the account terms
None of these automatically means a broker is fraudulent. Plenty of offshore-regulated brokers operate honestly within the rules of their licence. But it does mean the trader is carrying more risk than the headline terms suggest, and should size positions accordingly.
Conclusion
Spread comparisons matter, but they’re the easy part of choosing a broker. The harder, more consequential question is what happens on the one day a trade moves violently against you, and whether the entity holding your account is legally required to protect you when it does. Checking the regulatory entity behind an account takes ten extra minutes before opening an account. Skipping it is how traders end up finding out the hard way what “regulated” actually meant in their case.