
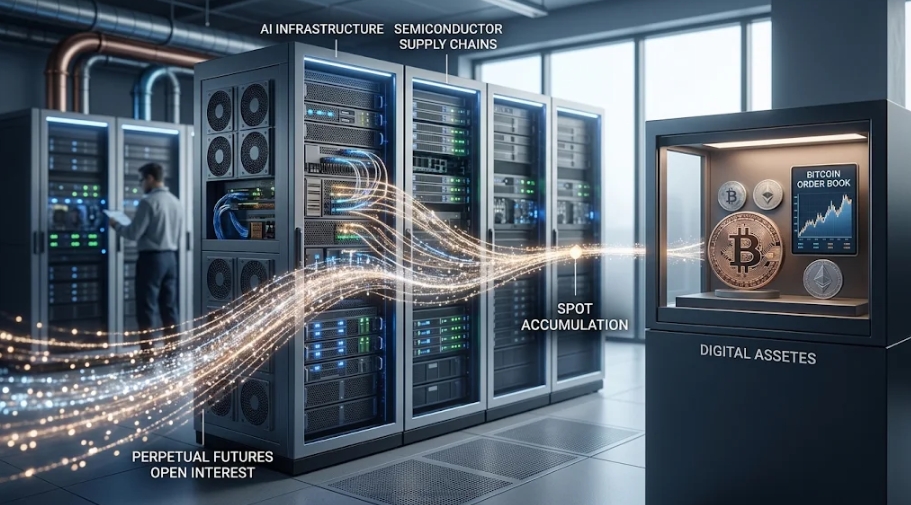
Following Bitcoin’s fourth halving in 2024 and the subsequent pivot toward global monetary easing, many market participants anticipated a traditional post-halving expansion across the cryptocurrency sector. Instead, speculative liquidity over the past two years has diverged from historical patterns, concentrating heavily within artificial intelligence infrastructure and semiconductor supply chains. Speaking on CoinDesk’s Markets Outlook broadcast with host Ray Salmond on November 4, 2026, Hyblock Capital Chief Executive Officer Shubh Varma examined how this massive allocation toward AI hardware has affected Bitcoin’s cyclical momentum and market microstructure.
This analysis explores the order book indicators, derivatives positioning, and macroeconomic capital flows highlighted by Hyblock Capital, evaluating why capital concentration in artificial intelligence has slowed crypto’s historical liquidity cascade and outlining the financial conditions that could trigger a rotation back into digital assets.
Key Takeaways
- Global risk-on capital has concentrated heavily in AI data centers, Neocloud debt, and semiconductor equities, absorbing a substantial share of the speculative liquidity that historically fueled post-halving crypto rallies.
- Durable bull markets require sustained spot accumulation; current price action remains heavily influenced by perpetual futures open interest, resulting in frequent two-sided liquidation sweeps and range-bound trading.
- The combination of spot Bitcoin ETFs locking capital inside traditional brokerage accounts, rapid token supply dilution, and retail traders gravitating toward AI stocks has disrupted the historical wealth-transfer cascade into altcoins.
- Despite slower directional upside, centralized exchange order books have grown significantly deeper and more resilient since 2022, absorbing multi-billion-dollar repayments and security incidents without systemic contagion.
- As hyperscaler AI capital expenditures face growing investor scrutiny over negative free cash flow and rapid GPU depreciation, institutional capital has a compelling catalyst to rotate toward non-depreciating digital collateral like Bitcoin.
How the AI Hardware Boom Absorbed Speculative Liquidity
The commercialization of generative artificial intelligence created a massive alternative capital sink across public equities, private credit, and venture capital, absorbing the high-beta speculative liquidity and investor attention that historically drove parabolic post-halving expansions in cryptocurrency markets.
During earlier cryptocurrency market cycles—most notably in 2016–2017 and 2020–2021—digital assets served as the premier global outlet for high-growth, high-volatility technology speculation. When central banks eased monetary conditions or fiscal liquidity expanded, macro hedge funds, family offices, and retail traders channeled risk capital into liquid crypto markets, propelling Bitcoin higher before rotating profits down the risk curve into Layer-1 protocols and decentralized applications.
Between 2024 and 2026, however, the broader technology landscape underwent a major capital reallocation. Scaling frontier foundation models and enterprise inference clusters required an unprecedented physical infrastructure buildout. As cloud hyperscalers and specialized AI laboratories committed hundreds of billions of dollars to procure graphics processing units (GPUs), high-bandwidth memory (HBM4), optical networking fabrics, and gigawatt-scale electrical substations, institutional allocators redirected marginal risk capital into the AI hardware stack.
Asset managers, crossover funds, and corporate treasuries that previously looked to digital assets for asymmetric technology exposure found comparable volatility and return profiles in semiconductor equities, high-yield Neocloud debt facilities, and data center development projects. Consequently, while the cryptocurrency market did not suffer an outright flight of existing base capital, it experienced a noticeable moderation in net new speculative inflows as venture dollars and macro trading desks chased the AI infrastructure buildout.
Empirical Data and Market Indicators
Corporate financial disclosures from late 2026 illustrate the scale of this capital divergence. According to consensus projections compiled by Visible Alpha, combined annual capital expenditures across the eight largest global technology infrastructure spenders—Alphabet, Amazon, Apple, Meta Platforms, Microsoft, Oracle, CoreWeave, and Baidu—more than doubled from roughly $456 billion in 2025 to an estimated $918 billion in 2026 (with the four primary U.S. cloud hyperscalers alone accounting for $720 billion to $740 billion).
Over the same period, private venture capital funding directed into cryptocurrency and blockchain startups remained comparatively muted at roughly $12 billion to $13 billion annualized in 2026, a fraction of the $30 billion+ peak recorded during the 2021 cycle and dwarfed by the tens of billions raised in single private rounds by frontier AI labs. As Varma observed during his November 4 Markets Outlook interview, the speculative liquidity that typically powers vertical post-halving crypto rallies did not vanish from the financial system; rather, macro and retail participants spent the past two years allocating heavily into the AI trade, leaving crypto markets in a prolonged, choppy consolidation phase.
Spot Accumulation vs. Perpetual Futures Liquidity Hunts
Organic, multi-quarter bull runs rely on persistent spot market accumulation that removes circulating supply from exchange order books; by contrast, recent market structure has been dominated by leveraged perpetual futures positioning, which encourages algorithmic liquidity sweeps and range-bound mean reversion.
Through its order book depth trackers and liquidation heatmaps, Hyblock Capital monitors the real-time balance between passive limit orders, aggressive market orders, and leveraged derivatives positions across global trading venues. In a healthy, spot-driven expansion, institutional buyers and long-term allocators accumulate physical Bitcoin through spot limit orders or programmatic time-weighted average price (TWAP) execution. That spot buying absorbs resting sell orders (asks) on exchange order books, reducing liquid supply and establishing durable price floors.
When net new spot inflows slow down, derivatives markets become the primary driver of short-term price discovery. In a derivatives-heavy regime, short-term momentum traders rely on leveraged perpetual futures contracts to seek amplified returns, causing aggregate Open Interest (OI) to climb relative to underlying spot trading volume.
As leveraged long and short positions build up on either side of a tight trading range, predictable clusters of forced liquidation levels form just above resistance and just below support. Sophisticated market makers and high-frequency algorithmic desks track these liquidation clusters closely. When order book depth thins out, price is frequently pushed into these dense liquidity pockets, triggering cascading stop-losses and forced margin liquidations. Once those leveraged positions are flushed out, however, the lack of follow-through buying from genuine spot accumulators causes the breakout or breakdown to stall, pulling Bitcoin back inside its prior trading range.
Order Book Evidence and CVD Metrics
Hyblock Capital’s Cumulative Volume Delta (CVD) metrics—which measure the net difference between aggressive market buying and market selling volume—highlight this tug-of-war between spot and perpetual markets. Throughout recent months in 2026, temporary price rallies were frequently accompanied by surging perpetual futures CVD and rising open interest while spot CVD remained flat or negative.
Varma noted that when perpetual futures traders lead a rally without corresponding spot demand, the market becomes top-heavy and vulnerable to rapid long squeezes. Conversely, durable trend reversals historically occur only after leveraged derivatives traders have been washed out, open interest resets lower, and spot CVD turns decisively positive across major dollar and stablecoin trading pairs.
Why the Traditional “Alt Season” Has Stalled
One of the most visible side effects of the AI capital boom and changing market plumbing has been the absence of a broad-based “altcoin season” comparable to earlier cycles.
The traditional wealth-transfer cascade from Bitcoin into smaller alternative tokens has broken down because spot ETFs keep institutional capital siloed inside traditional brokerage wrappers, excessive new token launches have diluted available liquidity, and speculative retail traders have rotated into volatile AI and semiconductor equities.
In prior bull cycles, crypto liquidity followed a predictable internal waterfall. Fiat capital first flowed into Bitcoin on centralized exchanges; as Bitcoin rallied and consolidated, traders took profits directly into USDT or BTC trading pairs and rotated those gains into Ethereum, large-cap Layer-1 networks, and eventually mid- and small-cap altcoins. Because all of that capital lived inside native cryptocurrency exchanges and self-custodial wallets, rotating from Bitcoin into an altcoin required only a single click.
In the 2024–2026 cycle, three structural changes interrupted this internal loop. First, a massive share of net new capital entering Bitcoin arrived via regulated spot Exchange-Traded Funds (ETFs). Dollars held inside pension portfolios, registered investment advisor (RIA) model allocations, and tax-advantaged brokerage accounts cannot simply be swapped on-chain into mid-cap DeFi or gaming tokens. When an ETF investor takes profit on Bitcoin, those proceeds settle back into fiat brokerage cash—where they are far more likely to be reinvested into equities like NVIDIA or Microsoft than bridged onto a blockchain.
Second, the supply of alternative tokens expanded far faster than secondary market demand. Thousands of new Layer-2 networks, infrastructure protocols, and meme coins launched over the past two years. As industry analysts have widely noted, many venture-backed tokens debuted with high fully diluted valuations (FDVs) and low initial circulating floats, subjecting secondary buyers to continuous monthly unlock dilution.
Third, retail traders seeking high-octane volatility found an accessible substitute in the stock market. With leveraged single-stock ETFs, zero-day options, and volatile AI data center and semiconductor stocks available in standard trading apps, retail speculators no longer needed to navigate long-tail altcoins to capture high-beta price action. Hyblock’s order book metrics reflect this divergence: while Bitcoin and Ethereum maintain deep institutional liquidity, order book depth across smaller altcoins remains thin, making rallies harder to sustain without genuine product revenue.
Exchange Order Book Resilience: The Maturation of Crypto Market Depth
While the diversion of speculative capital into AI has tempered explosive upside across the token market, Varma emphasized on Markets Outlook that the underlying infrastructure of the cryptocurrency market is substantially healthier and more resilient than it was four years ago.
Order book depth, risk management, and clearing architectures across leading global centralized exchanges have matured significantly since 2022, enabling the market to absorb multi-billion-dollar supply shocks and security incidents without triggering systemic insolvencies.
During the 2022 market downturn, sharp price drops exposed fragile, interconnected credit loops across the industry, culminating in the collapses of Three Arrows Capital, Celsius, BlockFi, and FTX. Those failures occurred because major market makers and lending desks operated with under-collateralized bilateral loans, commingled customer funds, and thin spot order books that vanished during moments of stress.
By late 2026, the plumbing of digital asset trading looks markedly different. Market makers operate under much stricter collateral requirements, transparent proof-of-reserves standards have become industry norms across major exchanges, and institutional liquidity is spread across multiple resilient spot and derivatives venues.
During the CoinDesk interview, Varma pointed out that over the past two years, the crypto market has been tested by several multi-billion-dollar liquidity events—including large bankruptcy estate distributions (such as Mt. Gox and Genesis repayments), sovereign government Bitcoin sales, and major security exploits—yet exchange order books absorbed the selling pressure smoothly. Across leading global centralized exchanges, resting bid depth within 1% to 2% of the mid-price now routinely handles multi-billion-dollar daily liquidation and rebalancing volumes while maintaining continuous execution and tight bid-ask spreads. This structural maturity provides a stable foundation once macro inflows return.
How Tech Capex Fatigue Could Trigger Capital Rotation into Bitcoin
Although artificial intelligence has acted as a headwind for crypto inflows over the past 24 months, Hyblock Capital’s analysis suggests that the late stages of the AI infrastructure cycle could become a powerful catalyst for Bitcoin’s next major expansion.
A sustained capital rotation back into Bitcoin is increasingly plausible as Wall Street confronts “Capex fatigue” in Big Tech—where $740 billion+ in annual AI infrastructure spending is pressuring corporate free cash flows and creating massive three-to-five-year GPU depreciation liabilities—prompting investors to rebalance profits into non-depreciating, scarce digital collateral.
Throughout late October and early November 2026, public capital markets began showing clear signs of pushback against open-ended AI capital expenditures. During the third-quarter 2026 earnings season, quarterly free cash flow turned negative at major hyperscalers as data center spending surged—highlighted by Alphabet’s 12.6% single-day stock drop on October 29 after reporting negative $9.1 billion in Q3 free cash flow, S&P Global Ratings’ decision on October 30 to revise Meta Platforms’ AA- credit outlook to negative over projected 2027 cash flow deficits, and OpenAI’s move to trim its private fundraising target from $30 billion to $20 billion.
Furthermore, consensus estimates from Visible Alpha project that annual Capex growth across the top eight technology spenders will decelerate sharply from +101% in 2026 and +65% in 2027 down to single-digit percentages (+10% in 2028, +3% in 2029, and +2% in 2030).
For institutional portfolio managers, this transition exposes a critical balance-sheet distinction between AI infrastructure and Bitcoin. Physical AI data centers are depreciating operational assets: a $50 billion gigawatt-scale cluster of GPUs requires continuous electrical power, cooling water, and maintenance, and its silicon becomes economically obsolete every three to five years as newer architectures launch.
Bitcoin, by contrast, carries zero physical depreciation, zero maintenance Capex, and a mathematically fixed supply of 21 million coins (with 55% residing in unattributed self-custody and corporate treasuries like Strategy and Tether holding over 1 million BTC combined). As technology equity valuations adjust to slower Capex growth and heavy depreciation charges, institutional allocators sitting on substantial multi-year gains in semiconductor and AI equities have a strong incentive to rotate a portion of those profits into an unencumbered, liquid monetary asset that is immune to hardware obsolescence.
Conclusion
Insights from Hyblock Capital CEO Shubh Varma offer a clear, data-driven explanation for Bitcoin’s evolving market structure in late 2026. Rather than signaling a loss of institutional relevance, Bitcoin’s extended consolidation reflects a macroeconomic environment where hundreds of billions of dollars in risk capital were temporarily absorbed by the global AI infrastructure buildout, leaving short-term crypto price discovery dominated by perpetual futures liquidity sweeps. Yet beneath the surface, centralized exchange order books have achieved historic depth and resilience. As Wall Street begins to enforce stricter return-on-investment discipline on Big Tech’s AI spending spree, the stage is increasingly set for institutional liquidity to rotate back toward scarce, spot-driven digital assets.
FAQs
Is the AI boom preventing Bitcoin from having a bull run?
According to Hyblock Capital CEO Shubh Varma on CoinDesk’s Markets Outlook (November 4, 2026), the AI boom has not broken Bitcoin’s long-term trajectory, but it has delayed explosive upside by absorbing the speculative institutional and retail liquidity that historically flowed into crypto following halving events
What is the difference between a spot-driven rally and a derivatives-driven rally in Bitcoin?
A spot-driven rally occurs when buyers purchase actual Bitcoin on spot exchanges (reflected in rising spot Cumulative Volume Delta, or CVD), which removes supply from order books and builds lasting price support. A derivatives-driven move is fueled by leveraged perpetual futures contracts; without spot buying behind it, high futures Open Interest typically leads to two-sided liquidation sweeps and range-bound chop.
Why hasn’t there been a traditional “altcoin season” in the 2024–2026 cycle?
Three structural factors have dampened broad altcoin rallies: (1) spot Bitcoin ETF inflows stay locked inside traditional brokerage accounts rather than rotating on-chain; (2) thousands of new token launches and heavy venture unlock schedules have diluted secondary market liquidity; and (3) retail speculators have increasingly traded volatile AI and semiconductor stocks instead of long-tail crypto tokens.
How could a slowdown in Big Tech AI spending benefit Bitcoin?
As cloud hyperscalers face investor scrutiny over $740 billion+ in annual AI capital expenditures, negative free cash flows, and 3-to-5-year GPU depreciation schedules, equity valuation multiples face compression. Unlike physical AI servers that depreciate rapidly and require massive energy upkeep, Bitcoin is a scarce, non-depreciating monetary asset—positioning it as a prime beneficiary when institutional capital rotates out of crowded tech stocks.
Disclaimer: This general market information, possibly from third-party, commercial, or sponsored sources, is provided for reference and educational purposes only and does not constitute financial or investment advice, an offer, solicitation, or guarantee. We disclaim liability for its accuracy, completeness, reliability, and any resulting losses. Investments/trading are risky; past performance doesn’t guarantee future results. Users should research, judge prudently, and take full responsibility.