
“For the first time, enterprise finance has a settlement layer that moves as fast as the business it serves.”
For most of the last two decades, a CFO’s relationship with banking infrastructure was settled early in their career and rarely revisited. Correspondent banking, card networks, and batch-based ACH rails did their job quietly in the background. What has changed in 2026 is not that these systems broke. It is that finance leaders finally have a credible, regulated alternative sitting next to them, and enough of their peers are already using it that ignoring it has become its own kind of risk.
The passage of the GENIUS Act in mid-2025 gave the United States its first federal framework for payment stablecoins, and the effect on corporate finance has been more structural than symbolic. Banks no longer have to treat stablecoins as a compliance question to be avoided. They can treat them as a product line to be built. That shift in posture, from defense to infrastructure investment, is the real story behind the current wave of interest from treasury teams, and it explains why “stablecoin banking” has moved from crypto conference panels into board-level treasury reviews.
The Entire Concept of Stablecoin Banking & Its Infrastructure Stack
Stablecoin banking is the layer of financial infrastructure being built around stablecoins as a functioning medium of value rather than a trading instrument. It covers how stablecoins are issued, held, moved, spent, and settled inside a compliant structure, not just how they are bought and sold on an exchange. What separates it from the broader “crypto” conversation is that it is being designed to sit alongside, and increasingly inside, regulated financial infrastructure. A typical stack includes:
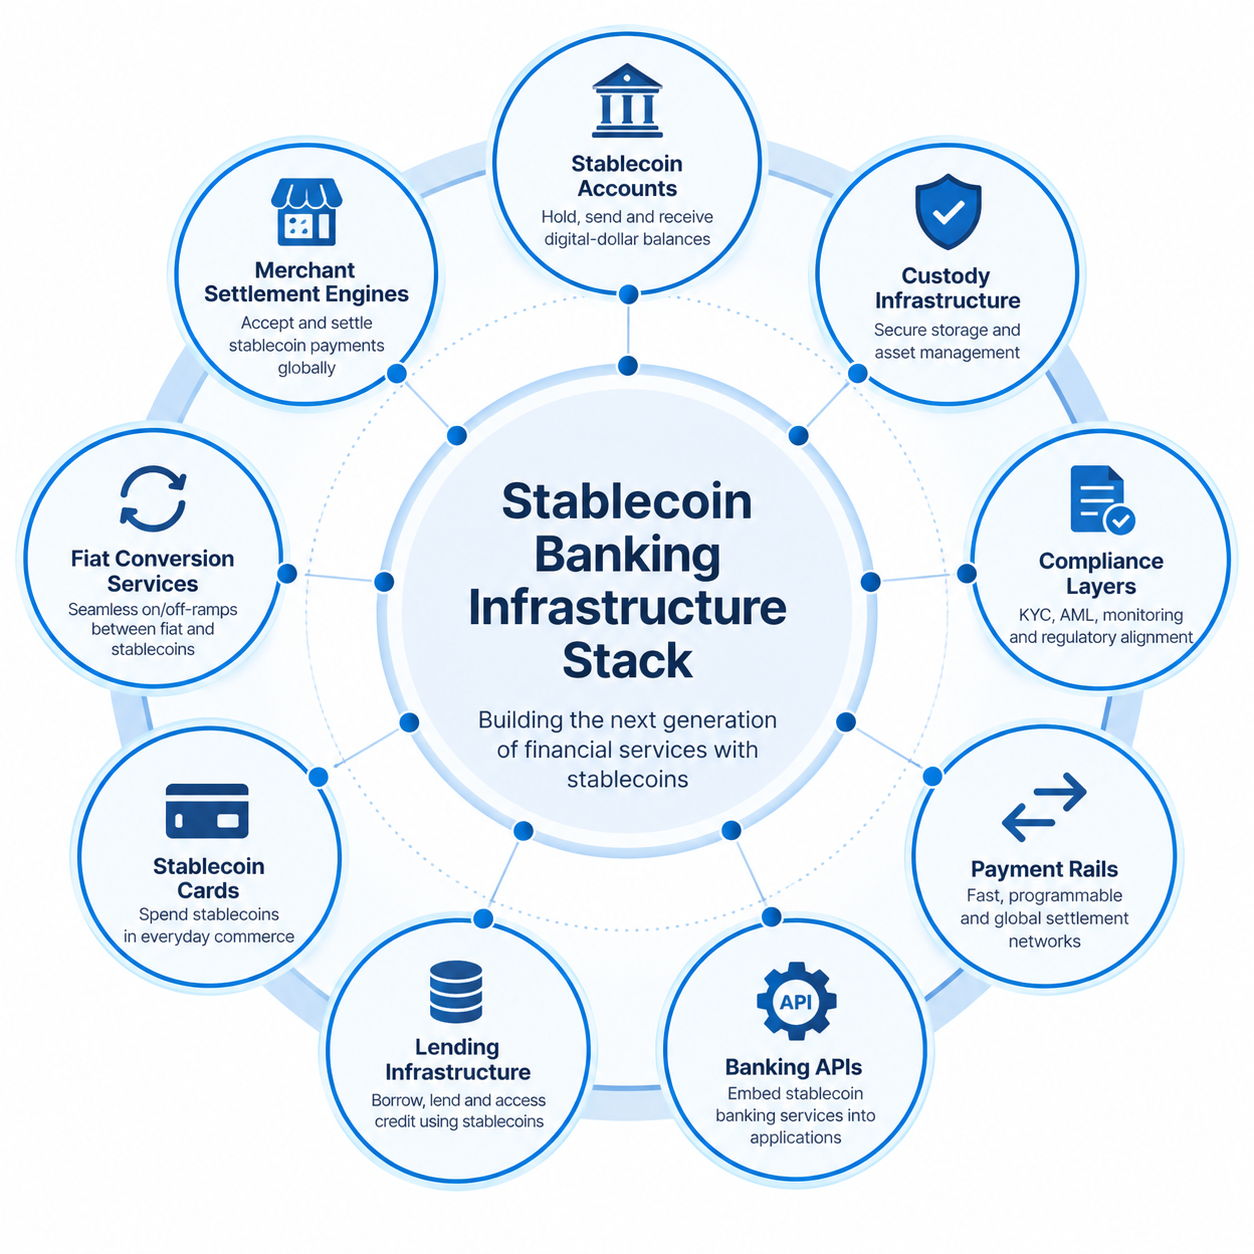
Each of these components already exists in traditional banking in some form. What is different is that they are being rebuilt on programmable, ledger-native rails, which changes how fast they move, how transparent they are, and who can access them.
Know Why Traditional Banking Infrastructure Is Facing Pressure
Legacy banking infrastructure was built for a world of business hours, national clearing systems, and bilateral correspondent relationships. That design is now the source of most of its friction.
- Cross-border friction. A payment moving between countries typically passes through several intermediary banks, each applying its own cut-off times, fees, and compliance checks.
- Banking hours. Most domestic and correspondent rails still operate on business-day cycles, which means a payment initiated on a Friday afternoon may not settle until the following Monday or Tuesday.
- Settlement delays. Even “fast” cross-border rails can take one to three business days to reach final settlement, well behind the expectations set by real-time domestic systems.
- Expensive remittance networks. Legacy remittance corridors still route through multiple correspondent banks and FX desks, adding cost at every hop.
- Fragmented financial access. Large parts of the world remain underserved by correspondent banking relationships, which limits how easily businesses in emerging markets can receive or send international payments.
- Multi-intermediary banking flows. Every additional bank in a payment chain adds a reconciliation point, a potential failure point, and a delay.
None of these are new observations. What has changed is that there is now a regulated alternative capable of addressing them directly, rather than working around them.
The Driving Forces for Stablecoin Banking Infrastructure
A handful of forces are converging to move stablecoin banking from a niche experiment into infrastructure that regulated institutions are willing to build on.
- Regulatory frameworks reaching maturity. The GENIUS Act in the United States and MiCA in the European Union have given issuers and banks an actual rulebook to build against, covering reserves, disclosure, and licensing.
- Institutional issuance. A consortium of roughly two dozen major banks, including Citi, Goldman Sachs, and UBS, has been organizing around a jointly issued, bank-backed stablecoin targeting a first-half 2027 launch, according to 2026 reporting from Forkast and Genfinity. JPMorgan’s JPM Coin continues to expand its institutional settlement use cases in parallel.
- Maturing custody and compliance tooling. Institutional-grade custody, key management, and transaction monitoring have closed much of the gap that previously made stablecoin infrastructure too immature for regulated financial institutions to touch.
- Interoperability standards. Cross-chain settlement and messaging standards are reducing the fragmentation that once made stablecoin liquidity difficult to move between networks and banking partners.
- Growing stablecoin supply and usage. As the base of circulating, regulated stablecoins expands, liquidity and counterparty depth increase, making it more practical for banks and enterprises to route real volume through these rails.
Top-Notch Reasons Why Enterprises Are Exploring Stablecoin Banking
CFOs are part of this conversation, but not primarily because of treasury yield or balance sheet strategy. Enterprises across sectors are exploring stablecoin-powered neo banking solutions because they unlock capabilities legacy infrastructure was never built to offer:
- 24/7 money movement, without cut-off times or banking holidays
- Global settlement that does not depend on a chain of correspondent banks
- Dollar access in emerging markets where local currency volatility or capital controls limit options
- Reduced dependency on a single banking relationship for cross-border operations
- Faster supplier payments, particularly across time zones and currencies
- More practical cross-border operations for businesses running distributed supply chains
- More efficient treasury operations, as one benefit among several rather than the primary driver
For a business operating across multiple markets, the appeal is closer to operational resilience than financial engineering: fewer single points of failure, fewer banking relationships to maintain, and a settlement layer that runs on the same schedule as the business itself.
Infrastructure providers such as Antier are helping accelerate this shift by equipping financial institutions with the technology required to integrate stablecoin accounts, payments, settlement, and compliance capabilities into existing banking environments, reducing the complexity of building these systems from scratch.
The Stablecoin Banking Products Emerging Today
The stack described earlier is no longer theoretical. A set of concrete product categories is already shipping across banks, fintechs, and infrastructure providers.
- Stablecoin accounts that allow users and businesses to hold, send, and receive digital dollars.
- Stablecoin payments that enable merchants to accept stablecoins and settle transactions faster.
- Stablecoin savings products that offer opportunities to earn yield on stablecoin balances.
- Stablecoin lending solutions that support borrowing and lending using stablecoins.
- Stablecoin crypto cards that allow users to spend stablecoins through traditional payment networks.
- Global stablecoin transfers that facilitate faster and lower-cost cross-border money movement.
- On/Off-ramps that enable seamless conversion between fiat currencies and stablecoins.
- Merchant settlement solutions that help businesses settle transactions in stablecoins, reducing settlement delays and reliance on traditional banking hours.
- Banking APIs that allow fintechs and enterprises to embed stablecoin accounts, payments, compliance, and financial services directly into their platforms.
Regulation Is Turning Infrastructure Into Opportunity
Stablecoin banking cannot exist at scale without regulatory trust, and 2026 has been the year that trust started to take a defined shape across major jurisdictions.
1) In the United States, the GENIUS Act established a federal framework for payment stablecoins, covering reserve backing, redemption rights, and issuer licensing.
2) In the European Union, MiCA has set out rules for e-money tokens and asset-referenced tokens, giving issuers a path to operate across the bloc under a single regulatory regime.
3) In the UAE, Dubai’s VARA has been developing its Asset-Referenced Virtual Asset framework, giving stablecoin issuers and service providers operating in the emirate a defined licensing path.
4) At the global level, the Financial Action Task Force has continued to update its guidance on virtual assets, including a 2026 targeted report addressing stablecoins and unhosted crypto wallets, pushing jurisdictions to close remaining gaps in anti-money-laundering coverage.
Taken together, these frameworks are converging on a similar set of expectations: verified reserves, clear redemption rights, licensed issuance, and traceable transaction flows. That convergence is what allows banks, enterprises, and payment providers to treat stablecoin banking as infrastructure they can build compliance programs around, rather than a gray area they have to work to avoid.
Where Does Stablecoin Banking Head Next?
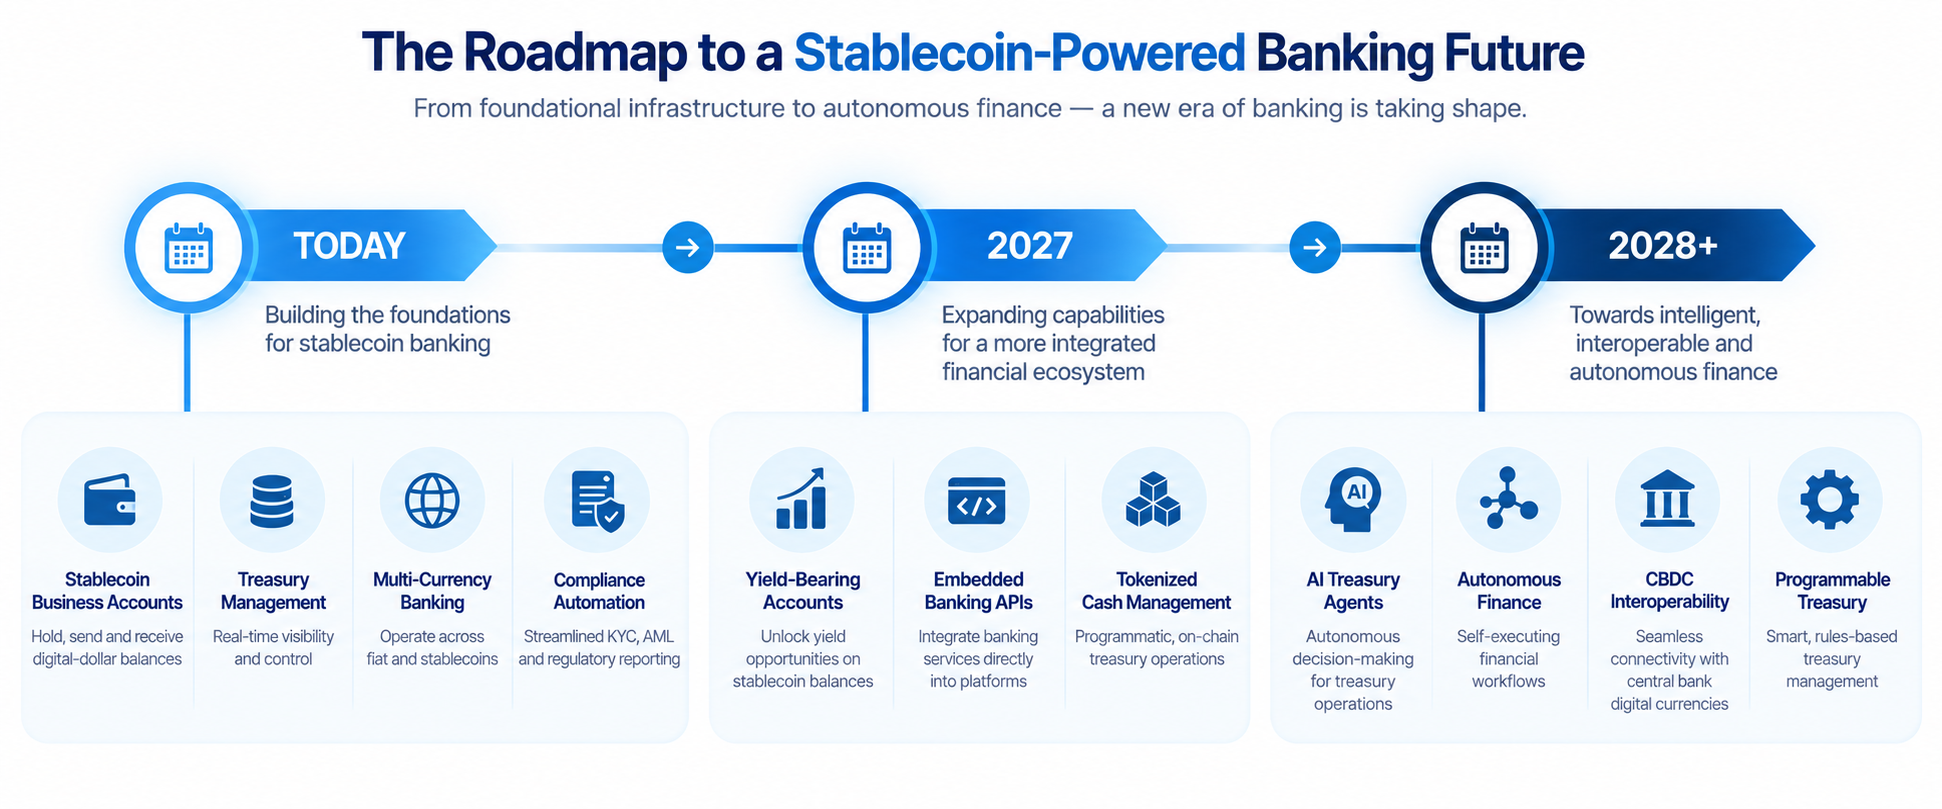
What began as an alternative payment rail is becoming a parallel banking layer, one built on programmable settlement instead of correspondent relationships. The institutions and enterprises positioning themselves now, while the infrastructure is still forming, are the ones most likely to shape how that layer operates once it becomes the default rather than the exception.
The Infrastructure Question Banks Can No Longer Ignore
Yet the industry’s readiness remains uneven. While demand for stablecoin-powered financial services is accelerating, many banks are still operating on infrastructure that was never designed for always-on, globally connected financial networks.
To stay relevant in this next phase of banking, institutions will need to:
- Modernize payment and settlement infrastructure for a world that operates beyond traditional banking hours.
- Develop deeper expertise in stablecoin and blockchain ecosystems as these technologies become increasingly intertwined with mainstream finance.
- Build interoperable systems capable of connecting fiat banking services with emerging digital asset networks.
- Integrate compliance, risk, and governance frameworks directly into digital financial operations.
- Take a proactive approach to regulation, viewing it as an enabler of innovation rather than a constraint.
The real opportunity is not simply adopting stablecoins. It is building the infrastructure that allows them to operate securely, efficiently, and at scale. Those foundations will determine which institutions lead the next era of banking. Stay ahead in this highly competitive market.