
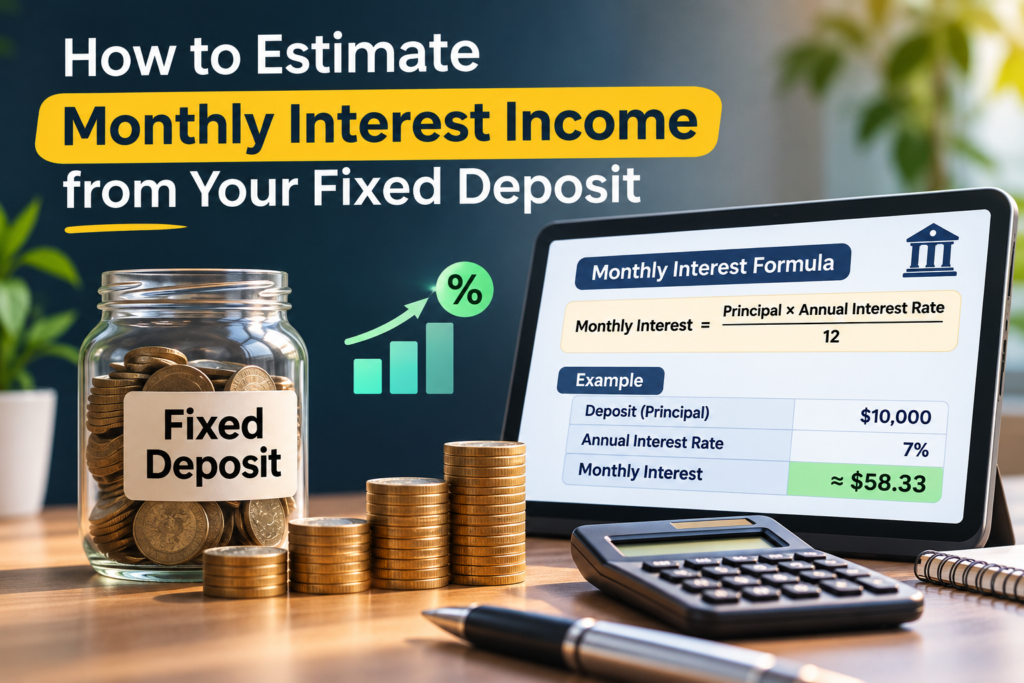
TLDR: Your monthly income from a fixed deposit depends on four things: the principal, the interest rate, how often interest is paid out, and tax. In a non-cumulative FD with monthly payout, the monthly interest is the principal times the annual rate divided by twelve. For example, ₹10 lakh at 8% gives about ₹6,667 a month before tax. A cumulative FD pays nothing monthly and instead gives a larger lump sum at maturity because interest compounds. Interest is taxable, and TDS may reduce what actually reaches your account, so the amount received can be lower than the pre-tax figure. An FD interest calculator is the easiest way to check the numbers before you deposit.
A fixed deposit that generates regular interest income is one of the more predictable forms of investment return available, and the predictability is part of what makes it useful for planning monthly household finances or supplementing a regular income. The challenge for many depositors is that the amount they actually receive each month is not always as transparent as the interest rate suggests, and the difference between the stated rate and the actual monthly payout involves a few calculations that are worth understanding rather than simply trusting that the number on the statement is correct.
The calculation is not complicated, but it requires clarity on a few specific variables before the monthly income figure can be arrived at accurately.
The Variables That Determine Monthly Interest
Amount of the deposit (the Principal Capital): For any interest calculation, how much you invested will be the base of the calculation. The FD agreement states the interest rate, but to compute monthly income, it is necessary to convert that stated annual rate into the monthly equivalent. For a simple interest calculation, the base would be the principal times the annual rate divided by twelve.
For a periodic compounding deposit, the calculation is a bit more complex. The manner in which the deposit interest is paid out defines the nature of the payments: monthly, quarterly, or at the end of the deposit tenure. A non-cumulative FD with monthly payout pays interest at the end of the month rather than adding it to the deposit at the end of the tenure.
The received monthly payment in this case will be the original basis, as the interest is paid out. Yet, a cumulative FD, with interest building up and rolling on throughout the period, pays no monthly income and, in fact, gives a larger lump sum in the end, as the interest builds up to earn further interest over the whole time period. The two structures are designed for different purposes, as to whether you want to increase the natural income stream or to develop capital over a period.
If the volume of periodic income is significant for depositors, the non-cumulative monthly payout scheme is preferable. In this scheme, the monthly interest on such a deposit is the quoted rate on the full principal divided by twelve and remains fixed throughout the term, unlike a simple payout. For example, a ten lakh rupees deposit at an interest rate of eight percent will give around six thousand six hundred rupees every month pre-tax.
Tax on Interest Income and How It Affects the Actual Amount Received
Interest earned on a fixed deposit is treated as income and is taxable in the year it is received, regardless of whether the deposit is cumulative or non-cumulative. For deposits at a bank or NBFC, TDS is deducted when the interest payable in a financial year crosses the applicable threshold. The amount deducted depends on whether the depositor has submitted Form 15G or 15H to prevent deduction, and whether their total annual income exceeds the taxable limit.
The actual monthly amount received in the account for a non-cumulative monthly payout deposit may therefore be lower than the calculated pre-tax figure, depending on the TDS treatment. Factoring this in when planning the monthly income picture from an FD is worth doing upfront rather than discovering the gap after the first payout lands.
Using a fixed deposit interest calculator is the most practical way to check the expected payout figures across different principal amounts and interest rates before placing a deposit, since it eliminates the risk of calculation errors and shows both the monthly interest and the total interest over the full tenure in one view.
Mahindra Finance offers fixed deposit products with clearly stated interest rates and payout options across different tenure ranges, which makes comparing the expected monthly income across deposit amounts and structures straightforward before a decision is made. The product details and the rate structure applicable to different depositor categories are available through the FD product page, which covers both the cumulative and non-cumulative options and what the rate differential between them looks like across tenures.
Planning a monthly income from a fixed deposit is a reliable exercise when the variables are understood clearly. The principal, the rate, the payout frequency, and the tax treatment together determine what actually arrives each month, and getting these right at the outset means the deposit performs the income function it was placed to serve without any unpleasant surprises when the statements start arriving.